
ACCT-352 · Lesson 12 of 12 · 23 min
Business tax compliance and a capstone
This final lesson does two things. First, it sets out the compliance calendar of a small business owner with an S corporation and a partnership interest: when Forms 1120-S, 1065 and 1040 are due, extensions, estimated tax, payroll and information returns, state filings, and the audit rules that apply to each kind of entity. Second, it assembles Brandt Aerial LLC's 2027 results and the Brandts' 2027 joint return from the pieces computed in lessons 5 to 9, reviews the year and identifies planning points for 2028. As throughout, the figures are invented and illustrative, and they apply 2026 rates on the assumption that they continue to 2027.
Filing deadlines
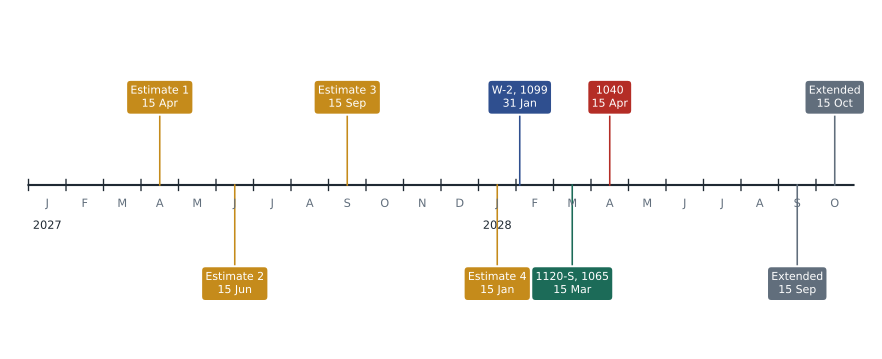
An S corporation files Form 1120-S, and a partnership Form 1065, by the 15th day of the third month after its year-end: 15 March 2028 for Brandt Aerial LLC and SkyGrid Data LLC. A C corporation files Form 1120 by the 15th day of the fourth month, 15 April for a calendar-year corporation. Each entity can obtain an automatic six-month extension (Form 7004), to 15 September for S corporations and partnerships and 15 October for C corporations. The entities must give each owner a Schedule K-1 by the return's due date, including any extension, and individual owners often must extend their own returns while waiting for K-1s. Late filing of Form 1120-S or 1065 brings a penalty for each month or part of a month, up to 12 months, multiplied by the number of shareholders or partners, even if no tax is due. The Brandts' 2027 Form 1040 is due on 15 April 2028, or 15 October with an extension, which extends only the time to file.
Estimated tax
Corporations pay estimated tax as described in lesson 3, and individuals with income not covered by withholding, such as S corporation and partnership income, must pay estimated tax on 15 April, 15 June and 15 September of the year and 15 January of the next year. The underpayment addition to tax is avoided if total withholding and timely estimated payments equal at least 90 percent of the current year's tax or 100 percent of the prior year's tax, 110 percent if the prior year's AGI exceeded $150,000. Withholding is treated as paid evenly through the year regardless of when it was withheld, so an owner-employee can catch up on a shortfall late in the year by increasing withholding from salary, which is often easier than making estimated payments. Iowa and most other states have similar estimated tax rules, and an entity that elects a PTET may have to make estimated payments of that tax.
Payroll, information returns and state filings
As an employer, Brandt Aerial LLC must withhold income tax and the employee share of FICA from Leah's wages, deposit them with its own share under the semiweekly or monthly deposit schedule, file Form 941 quarterly and Form 940 annually for federal unemployment tax, and give Forms W-2 to employees and the Social Security Administration by 31 January 2028. Payments of $600 or more to contractors were reportable on Form 1099-NEC; the 2025 act raised that threshold to $2,000 for payments made after 2025, indexed from 2027. The trust fund recovery penalty under section 6672 makes responsible persons personally liable for withheld taxes the business fails to pay over. At the state level, Brandt Aerial must file Iowa's S corporation return, with its PTET election, Iowa withholding returns, and nonresident or composite returns in Nebraska and Minnesota, and must register for sales tax wherever its services are taxable. The beneficial ownership reporting that the Corporate Transparency Act once required of small companies was limited by FinCEN in 2025 to foreign reporting companies, so domestic companies such as Brandt Aerial LLC are no longer required to report under it, a rule worth rechecking.
Audits of entities
S corporation items are examined at the shareholder level: the IRS examines the corporation's return and adjusts each shareholder's return, within each shareholder's assessment period (generally three years from the filing of the individual return). Partnerships are examined under the centralized audit regime described in lesson 7, unless they have elected out: adjustments are determined at the partnership level, and the partnership pays an imputed underpayment unless it elects to push the adjustments out to the partners of the reviewed year. C corporations are examined like individuals, with a three-year period that extends to six years for substantial omissions; larger corporations face continuous examination programs. Disputes go to the IRS Independent Office of Appeals and then to the Tax Court, a district court or the Court of Federal Claims, as described in ACCT-351. Keeping the basis computations, the reasonable compensation file and the PTET election documents in order shortens any examination.
| Obligation | Due date for 2027 | Lesson |
|---|---|---|
| Leah's estimated tax payments for 2027 | 15 April, 15 June, 15 September 2027; 15 January 2028 | 12 |
| Payroll deposits and Form 941 | Monthly or semiweekly; Form 941 quarterly | 12 |
| Forms W-2 and 1099-NEC | 31 January 2028 | 12 |
| Form 1120-S with K-1s (Brandt Aerial LLC) | 15 March 2028 (15 September with extension) | 8 |
| Form 1065 with K-1s (SkyGrid Data LLC) | 15 March 2028 (15 September with extension) | 7 |
| Iowa S corporation return and PTET | Iowa due dates (check the year's calendar) | 9 |
| Form 1040 for the Brandts | 15 April 2028 (15 October with extension) | 12 |
| Nebraska and Minnesota nonresident or composite returns | State due dates | 9 |
Capstone: Brandt Aerial LLC and the Brandts in 2027
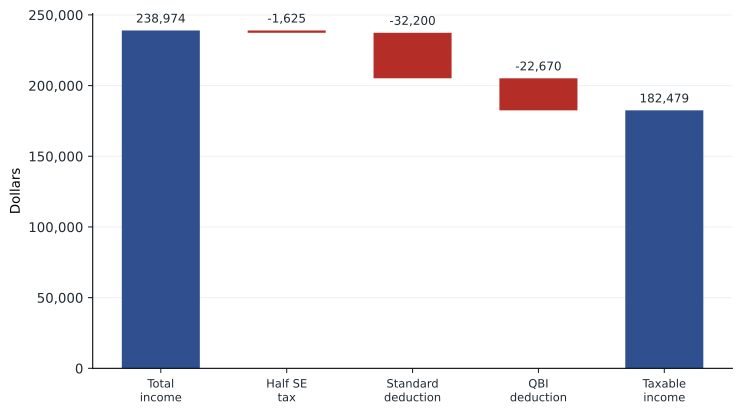
The program brings the year together. Brandt Aerial LLC's ordinary business income of $94,836 from lesson 8 is reduced by the Iowa PTET of $2,862.25 from lesson 9, and its interest, qualified dividends and capital gain pass through as separately stated items. SkyGrid Data LLC's K-1 adds $23,000 of ordinary income subject to self-employment tax, from lesson 7. Leah's W-2 shows her $70,000 salary and Tomás's W-2 his $38,000. The QBI deduction applies to both businesses' ordinary income, the qualified dividends and capital gain are taxed at 15 percent, and the Brandts claim the standard deduction and the child tax credit for Nora. Leah's withholding and Tomás's total $11,600, and they paid $18,000 of estimated tax during 2027.
# Capstone: Brandt Aerial's 2027 Form 1120-S and the Brandts' 2027 Form 1040, married filing
# jointly, using 2026 rates (illustrative; federal only)
BR = [(24_800, 0.10), (100_800, 0.12), (211_400, 0.22), (403_550, 0.24),
      (512_450, 0.32), (768_700, 0.35), (float('inf'), 0.37)]
def bracket(x):
    tax, lo = 0.0, 0.0
    for hi, r in BR:
        if x > lo:
            tax += (min(x, hi) - lo) * r
        lo = hi
    return tax

obi = 94_836 - 2_862.25          # S corporation ordinary income after the Iowa PTET (lesson 9)
interest, qual_div, ltcg = 4_000, 6_000, 6_000
partnership = 23_000             # SkyGrid Data LLC, K-1 box 1 (lesson 7)
wages = 70_000 + 38_000          # Leah's W-2 from Brandt Aerial and Tomas's W-2
se_tax = 0.153 * 0.9235 * partnership
total_income = wages + obi + interest + qual_div + ltcg + partnership
agi = total_income - se_tax / 2
std = 32_200
pref = qual_div + ltcg
qbi_base = obi + partnership - se_tax / 2
qbi = min(0.20 * qbi_base, 0.20 * (agi - std - pref))
taxable = agi - std - qbi
ordinary = taxable - pref
zero = max(0.0, min(pref, 98_900 - ordinary))
income_tax = bracket(ordinary) + 0.15 * (pref - zero)
ctc = 2_200
total_tax = income_tax - ctc + se_tax
withholding, estimates = 11_600, 18_000
rows = [("Wages (two Forms W-2)", wages), ("S corporation ordinary income (K-1)", obi),
        ("Partnership ordinary income (K-1)", partnership), ("Interest", interest),
        ("Qualified dividends", qual_div), ("Net long-term capital gain", ltcg),
        ("Total income", total_income), ("Less half of SE tax", -se_tax / 2),
        ("Adjusted gross income", agi), ("Less standard deduction", -std),
        ("Less QBI deduction", -qbi), ("Taxable income", taxable),
        ("Income tax (ordinary and 15% rates)", income_tax), ("Less child tax credit", -ctc),
        ("Plus self-employment tax", se_tax), ("Total federal tax", total_tax),
        ("Less withholding and estimated tax paid", -(withholding + estimates)),
        ("Amount owed, due 15 April 2028", total_tax - withholding - estimates)]
for k, v in rows:
    print(f"{k:<44}{v:>11,.2f}")
prior_year_tax = 15_502.18       # the Brandts' 2026 total tax (ACCT-351 capstone)
safe = 1.10 * prior_year_tax     # 2026 AGI exceeded $150,000
print(f"Prior-year safe harbor {safe:,.2f} met by payments of {withholding + estimates:,}: "
      f"{withholding + estimates >= safe}")
print(f"NIIT applies? MAGI {agi:,.0f} vs $250,000 threshold: {agi > 250_000}")Wages (two Forms W-2) 108,000.00 S corporation ordinary income (K-1) 91,973.75 Partnership ordinary income (K-1) 23,000.00 Interest 4,000.00 Qualified dividends 6,000.00 Net long-term capital gain 6,000.00 Total income 238,973.75 Less half of SE tax -1,624.90 Adjusted gross income 237,348.85 Less standard deduction -32,200.00 Less QBI deduction -22,669.77 Taxable income 182,479.08 Income tax (ordinary and 15% rates) 28,729.40 Less child tax credit -2,200.00 Plus self-employment tax 3,249.80 Total federal tax 29,779.19 Less withholding and estimated tax paid -29,600.00 Amount owed, due 15 April 2028 179.19 Prior-year safe harbor 17,052.40 met by payments of 29,600: True NIIT applies? MAGI 237,349 vs $250,000 threshold: False
Total income is $238,973.75 and AGI $237,348.85. The standard deduction and a QBI deduction of $22,669.77 bring taxable income to $182,479.08, in the 22 percent bracket. Income tax is $28,729.40; after the $2,200 child tax credit and with $3,249.80 of self-employment tax on the SkyGrid income, total federal tax is $29,779.19. Payments of $29,600 leave $179.19 owing on 15 April 2028, and because they exceed 110 percent of the 2026 tax of $15,502.18, no estimated tax penalty applies. Modified AGI is below the $250,000 threshold for the net investment income tax. Compared with the C corporation and sole proprietorship alternatives in lesson 5, the S corporation and PTET structure keeps the family's federal tax low while leaving Leah exposed mainly to the reasonable compensation question.
| Item | Amount | Lesson |
|---|---|---|
| Brandt Aerial LLC ordinary income after the Iowa PTET | $91,973.75 | 8, 9 |
| Separately stated: interest, qualified dividends, capital gain | $16,000.00 | 8 |
| SkyGrid Data LLC ordinary income (Leah's share) | $23,000.00 | 7 |
| Adjusted gross income | $237,348.85 | 12 |
| QBI deduction | $22,669.77 | 5, 12 |
| Taxable income | $182,479.08 | 12 |
| Self-employment tax on SkyGrid income | $3,249.80 | 7 |
| Total federal tax | $29,779.19 | 12 |
| Iowa PTET paid by Brandt Aerial LLC | $2,862.25 | 9 |
Reviewing the year and planning for 2028
A review of the year suggests several points for 2028. Leah's $70,000 salary is below the range suggested by market data, so raising it toward $90,000 to $100,000, documented by a compensation study, reduces the reasonable compensation risk, increases her 401(k) contribution base and costs relatively little. Because their 2027 AGI exceeded $150,000, the Brandts' prior-year safe harbor for 2028 requires payments of 110 percent of the 2027 tax of $29,779.19, about $32,757. Brandt Aerial should continue the Iowa PTET election and confirm whether Nebraska and Minnesota offer similar elections. SkyGrid Data LLC should decide whether to elect out of the centralized partnership audit regime and confirm both members' self-employment tax treatment. If outside investors are expected or the Brandts plan to reinvest for a sale in five years or more, they should revisit the C corporation and section 1202 analysis from lessons 4 and 5. A gift of nonvoting shares to a trust for Nora, using the annual exclusion, could begin shifting future growth. And the corporation should keep its basis schedules, Form 7203 support and payroll records current.
Worked problem
The Brandts' 2028 estimated tax
The Brandts expect 2028 income similar to 2027 and withholding of $13,000 after Leah's raise. What estimated payments keep them inside the prior-year safe harbor?
Show solution
- The prior-year safe harbor requires payments of 110% × $29,779.19 = $32,757.11, because 2027 AGI exceeded $150,000.
- Expected withholding of $13,000 leaves $19,757.11 to pay.
- Four equal payments of about $4,939.28 are due on 15 April, 15 June and 15 September 2028 and 15 January 2029.
- Alternatively, Leah could increase withholding from her salary, which is treated as paid evenly through the year.
- If 2028 income turns out lower, the 90 percent of current-year tax test may require less, but the prior-year safe harbor gives certainty.
Answer: About $19,757 of estimated tax, four payments of about $4,939, or extra withholding.
Common mistakes
MistakeAssuming an extension of Form 1120-S extends the shareholders' time to pay.
InsteadExtensions extend filing only; individual tax and estimated tax are due on their normal dates.
MistakeForgetting Forms W-2 for the owner-employee.
InsteadW-2s are due by 31 January; S corporation shareholder health insurance is included in wages.
MistakeIgnoring per-shareholder late filing penalties.
InsteadLate Forms 1120-S and 1065 bring monthly penalties per owner even with no tax due.
MistakeAssuming the business is protected from unpaid payroll taxes.
InsteadThe trust fund recovery penalty makes responsible persons personally liable.
MistakeTreating the return as the end of the work.
InsteadA review of the return is the start of planning for the next year.
Summary and key terms
- Forms 1120-S and 1065 are due 15 March; Form 1120 and Form 1040 on 15 April for calendar years.
- Six-month extensions are available but extend only the time to file.
- Individuals pay estimated tax quarterly; safe harbors are 90 percent current or 100/110 percent prior-year tax.
- Employers deposit payroll taxes, file Forms 941 and W-2, and issue 1099s; the 1099-NEC threshold is $2,000 from 2026.
- S corporations are examined at the shareholder level; partnerships under the centralized regime.
- Responsible persons are liable for unpaid trust fund taxes.
- The Brandts' 2027 total federal tax is $29,779.19, with $179.19 owing.
- Reviewing the finished returns is the start of planning for the next year.
- Schedule K-1
- The schedule reporting each owner's share of an S corporation's or partnership's items.
- Form 7004
- The form for an automatic extension of time to file business returns.
- Trust fund recovery penalty
- A penalty making responsible persons personally liable for unpaid withheld taxes.
- Form 941
- The employer's quarterly federal tax return for withheld income and FICA taxes.
- Centralized partnership audit regime
- The system under which partnership adjustments are determined and generally assessed at the partnership level.
- Information return
- A return reporting payments made to others, such as wages, dividends or contractor fees.
Practice problems
Work each problem on paper first, then reveal the answer to check.
When are Brandt Aerial LLC's Form 1120-S and the Brandts' Form 1040 due?
Show answer
15 March 2028 and 15 April 2028.
What are the two estimated tax safe harbors for the Brandts in 2028?
Show answer
90 percent of 2028 tax, or 110 percent of 2027 tax.
Under which regime are SkyGrid Data LLC's returns examined?
Show answer
The centralized partnership audit regime, unless it elects out.
By when must Forms W-2 for 2027 be furnished?
Show answer
31 January 2028.
What is the 1099-NEC reporting threshold for payments made in 2026?
Show answer
$2,000.
In the capstone, what is the Brandts' taxable income?
Show answer
$182,479.08.
Why does no estimated tax penalty apply for 2027?
Show answer
Their payments of $29,600 exceed 110 percent of their 2026 tax.
Name two planning points for 2028.
Show answer
For example raising Leah's salary, paying 110 percent safe harbor estimates, continuing the PTET and revisiting section 1202.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.