
ACCT-212 · Lesson 9 of 12 · 25 min
Employee future benefits and pensions
Northlake's employees earn more than salary while they work. Many will receive pensions after they retire, some will keep health and dental benefits in retirement, and all have earned vacation and other benefits that will be paid later. These promises are compensation for service rendered now, so their cost belongs in the periods when employees work, not when cash is eventually paid decades later. Measuring that cost is hard: it depends on how long employees will work, how much their salaries will rise, how long they will live and what interest rates and investment returns will be. This lesson explains how pension and other post-employment benefits are accounted for, focusing on defined benefit plans, where the frameworks differ most.
Defined contribution and defined benefit plans
In a defined contribution plan, the employer promises only to contribute a specified amount, for example 5 per cent of salary, to an account for each employee. The employee's eventual pension depends on the contributions and the investment returns earned on them; the employee bears the investment risk. Accounting is simple: the employer recognizes the required contribution as an expense in the period the employee works, and a liability for any contribution not yet paid. Most new private-sector plans in both countries are defined contribution plans, including group registered retirement savings plans in Canada and 401(k) plans in the United States.
In a defined benefit plan, the employer promises a specified pension at retirement, typically based on years of service and final or average salary, for example 2 per cent of the average of the best five years' salary for each year of service. The employer bears the investment and longevity risk: if plan assets earn less than expected or retirees live longer, the employer must contribute more. Defined benefit plans remain common in the public sector, in large unionized companies and among older employers. Their accounting requires actuarial estimates and is the subject of the rest of this lesson.
In Canada, registered pension plans are regulated by provincial pension standards acts or, for federally regulated employers, the Pension Benefits Standards Act, 1985. These set funding rules, typically requiring going-concern and solvency valuations at least every three years, which determine the cash contributions required. The accounting cost is measured separately and usually differs from the funding contribution. Canada Pension Plan and Quebec Pension Plan contributions (lesson 1) are payroll taxes, not employer pension plans.
Measuring a defined benefit obligation
The defined benefit obligation (called the projected benefit obligation in US GAAP) is the present value of the benefits employees have earned to date, taking into account expected future salary increases. Actuaries measure it using the projected unit credit method: each year of service earns one unit of benefit, projected to retirement using expected salary growth, and discounted to the present. The main assumptions are demographic (employee turnover, retirement age, mortality, using tables such as the Canadian Pensioners' Mortality tables or the US Pri-2012 tables with improvement scales) and financial (salary growth, inflation and the discount rate).
IAS 19, Employee Benefits, requires the discount rate to be determined by reference to market yields at the end of the reporting period on high-quality corporate bonds, usually interpreted as bonds rated AA, with currency and term consistent with the obligation. Because the obligation is long-dated, small changes in the discount rate have large effects: a one-point fall in the rate can increase the obligation of a mature plan by 12 to 15 per cent. Plan assets, the investments held in a separate trust to pay benefits, are measured at fair value. The net defined benefit liability (or asset) is the obligation minus plan assets; a surplus is limited by the asset ceiling, the present value of economic benefits available as refunds or reductions in future contributions.
Recognizing the cost under IAS 19
IAS 19 splits the change in the net defined benefit liability into three components. Service cost, the present value of benefits earned in the year plus any past service cost from plan amendments and gains or losses on settlements, is recognized in profit or loss. Net interest on the net defined benefit liability, the discount rate times the net liability at the start of the year (adjusted for contributions and benefits during the year), is recognized in profit or loss. Because net interest uses the discount rate for both the obligation and the assets, IAS 19 does not reward a company for assuming high investment returns. Remeasurements, actuarial gains and losses on the obligation from changes in assumptions and experience, and the difference between the actual return on plan assets and the interest income included in net interest, are recognized in other comprehensive income and never reclassified to profit or loss. They may be transferred within equity, for example to retained earnings.
Worked problem
One year of Northlake's pension plan
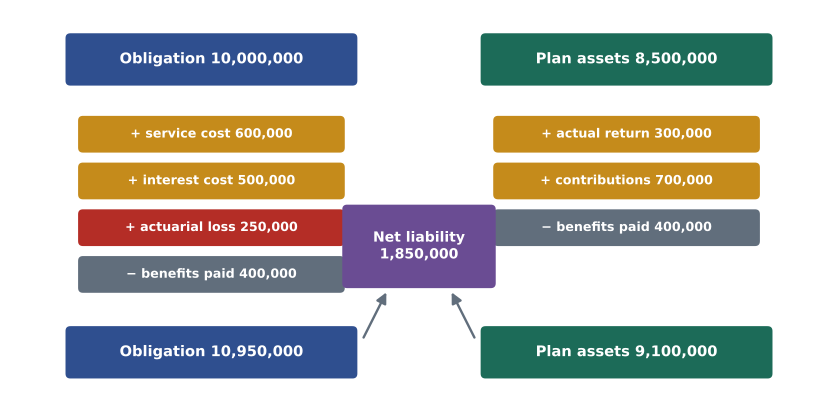
At 1 January 2027, Northlake's defined benefit obligation is $10,000,000 and plan assets are $8,500,000. The discount rate is 5 per cent. During 2027: service cost $600,000; contributions $700,000 (paid at year end); benefits paid $400,000 (at year end); actual return on assets $300,000; an actuarial loss of $250,000 on the obligation from lower assumed mortality.
Show solution
- Service cost in profit or loss: $600,000.
- Net interest: 5% × (10,000,000 − 8,500,000) = $75,000 in profit or loss (interest cost $500,000 less interest income $425,000).
- Remeasurements in OCI: actuarial loss $250,000 plus return shortfall (425,000 − 300,000) $125,000 = $375,000.
- Closing obligation 10,950,000; closing assets 9,100,000; net liability $1,850,000 (opening 1,500,000 + 675,000 + 375,000 − 700,000).
Answer: Pension cost in profit or loss $675,000; remeasurement loss in OCI $375,000; net liability $1,850,000.
# One year of a defined benefit plan: IAS 19 compared with ASC 715
dbo0, assets0, rate = 10_000_000, 8_500_000, 0.05
service, contrib, benefits = 600_000, 700_000, 400_000
actual_return, actuarial_loss = 300_000, 250_000
expected_rate, aoci_loss0, service_years = 0.065, 1_400_000, 10

dbo1 = dbo0 + service + dbo0 * rate - benefits + actuarial_loss
assets1 = assets0 + actual_return + contrib - benefits
print(f"Closing obligation {dbo1:,.0f}; closing assets {assets1:,.0f}; net liability {dbo1 - assets1:,.0f}")

# IAS 19
net_interest = rate * (dbo0 - assets0)
remeasure = actuarial_loss + (assets0 * rate - actual_return)
print(f"IAS 19: profit or loss {service + net_interest:,.0f} (service {service:,} + net interest {net_interest:,.0f}); OCI loss {remeasure:,.0f}")

# ASC 715
interest_cost = dbo0 * rate
expected_return = assets0 * expected_rate
corridor = 0.10 * max(dbo0, assets0)
amort = max(0, aoci_loss0 - corridor) / service_years
npc = service + interest_cost - expected_return + amort
oci_loss = actuarial_loss + (expected_return - actual_return)
print(f"ASC 715: net periodic cost {npc:,.0f} (operating {service:,}, other {npc - service:,.0f})")
print(f"ASC 715: OCI loss {oci_loss:,.0f}; amortization out of AOCI {amort:,.0f}; closing AOCI loss {aoci_loss0 + oci_loss - amort:,.0f}")Closing obligation 10,950,000; closing assets 9,100,000; net liability 1,850,000 IAS 19: profit or loss 675,000 (service 600,000 + net interest 75,000); OCI loss 375,000 ASC 715: net periodic cost 587,500 (operating 600,000, other -12,500) ASC 715: OCI loss 502,500; amortization out of AOCI 40,000; closing AOCI loss 1,862,500
The program confirms that both frameworks report the same net liability, $1,850,000, because both recognize the funded status in full. They differ in how much goes through profit or loss. IAS 19 charges $675,000 to profit or loss and $375,000 to OCI, and the OCI amount never returns to profit or loss. ASC 715 charges $587,500 to net income, lower because the 6.5 per cent expected return exceeds the 5 per cent discount rate, and records a $502,500 loss in OCI, of which a portion will be amortized into future pension cost through the corridor. The choice of expected return is a management assumption under US GAAP, which is why analysts scrutinize it; IAS 19 removed that judgement from profit or loss in 2013.
Past service cost, settlements and curtailments
When a plan is amended to increase or reduce benefits for past service, the change in the obligation is past service cost. IAS 19 recognizes it immediately in profit or loss, at the earlier of when the amendment or curtailment occurs and when related restructuring costs or termination benefits are recognized. A settlement, such as buying annuities from an insurer to transfer the obligation for a group of retirees, produces a gain or loss equal to the difference between the obligation settled and the price paid, also recognized in profit or loss. Before measuring past service cost or a settlement, the net liability is remeasured using current assumptions.
Other post-employment and long-term benefits
Post-employment benefits other than pensions, such as retiree health, dental and life insurance, are accounted for like defined benefit pensions under IAS 19, using actuarial assumptions about health cost trends. Because Canada's public health system covers hospital and physician care, these plans usually cover drugs, dental and supplementary care, so they are smaller than in the United States but still material for many employers. Other long-term employee benefits, such as long-service leave and long-term disability, are measured similarly, but all remeasurements go to profit or loss. Termination benefits are recognized when the entity can no longer withdraw the offer or recognizes related restructuring costs (lesson 2).
Employee future benefits under ASPE
ASPE Section 3462, Employee Future Benefits, requires a private enterprise to recognize the full defined benefit obligation less plan assets on its balance sheet, as under IAS 19, but with all remeasurements and other items recognized immediately in net income rather than OCI, because ASPE has no OCI. A private enterprise may measure the obligation using the most recent funding valuation prepared for regulators, rather than a separate accounting valuation, which saves cost but usually produces a different number because funding valuations use different assumptions. Multi-employer plans, such as many union plans, are often accounted for as defined contribution plans when the employer cannot obtain enough information.
| Feature | IAS 19 | ASC 715 (for comparison) |
|---|---|---|
| Balance sheet | Net liability or asset, with asset ceiling | Funded status, no ceiling |
| Return on assets in profit | Discount rate (within net interest) | Expected long-term rate |
| Actuarial gains and losses | OCI, never recycled | OCI, amortized through the corridor |
| Past service cost | Immediately in profit or loss | OCI, then amortized |
| Presentation | Entity chooses where to present net interest | Only service cost in operating income |
Reading pension disclosures
Pension notes are long but informative. They show reconciliations of the obligation and plan assets, the components of cost, the major assumptions and a sensitivity analysis showing how the obligation would change if the discount rate, salary growth or life expectancy changed. Readers should compare the discount rate with those of peers, check whether the plan's deficit is growing, and look at expected contributions for the coming year, which affect cash flow. A large deficit is effectively debt: analysts often add the net pension liability, after tax, to borrowings when computing leverage.
Common mistakes
MistakeExpensing only the cash contributed to a defined benefit plan.
InsteadRecognize the service cost and interest (and, under US GAAP, expected returns and amortization) regardless of funding.
MistakeUsing management's expected return on assets in profit or loss.
InsteadIAS 19 uses the discount rate in net interest; the excess actual return goes to OCI.
MistakeReclassifying past remeasurements from OCI to profit or loss.
InsteadIAS 19 remeasurements are never recycled.
MistakeIgnoring a plan amendment that raises benefits for past service.
InsteadRecognize past service cost immediately in profit or loss.
MistakeTreating the funding valuation as the accounting measure for every entity.
InsteadOnly ASPE allows a funding valuation; IFRS and US GAAP require an accounting valuation using their own assumptions.
Summary and key terms
- Defined contribution plans are expensed as contributions are required; the employee bears the investment risk.
- Defined benefit plans promise a pension formula; the employer bears investment and longevity risk.
- The obligation is measured actuarially using the projected unit credit method and a high-quality corporate bond discount rate.
- Both frameworks recognize the net funded status on the balance sheet.
- IAS 19 recognizes service cost and net interest in profit or loss and remeasurements in OCI, never recycled.
- Past service cost is recognized immediately; ASPE recognizes everything in net income.
- Pension deficits and assumptions deserve the same attention as borrowings.
- Defined benefit obligation
- The present value of benefits earned to date, including expected salary growth.
- Net interest
- The discount rate applied to the net defined benefit liability or asset.
- Remeasurements
- Actuarial gains and losses and the return on plan assets beyond interest income, recognized in OCI.
- Asset ceiling
- The limit on a recognized pension surplus to the economic benefits available.
- Defined contribution plan
- A plan in which the employer's obligation is limited to specified contributions.
- Defined benefit plan
- A plan that promises a pension determined by a formula, usually based on service and salary.
- Projected unit credit method
- An actuarial method that attributes benefits to each year of service, projected with expected salary growth.
- Plan assets
- Investments held by a separate fund to pay employee benefits.
- Service cost
- The present value of benefits earned by employees in the period.
- Actuarial gains and losses
- Changes in the obligation from experience and changes in assumptions.
- Settlement
- A transaction that eliminates further obligation for some or all benefits, such as an annuity purchase.
- Funded status
- The difference between the benefit obligation and plan assets.
Practice problems
Work each problem on paper first, then reveal the answer to check.
An employer must contribute 6 per cent of a $50,000 salary to a defined contribution plan. Expense?
Show answer
$3,000.
Opening obligation $4 million, assets $3.4 million, discount rate 4 per cent. IAS 19 net interest?
Show answer
$24,000.
Same plan: actual return $100,000. IAS 19 remeasurement on assets?
Show answer
Interest income $136,000; shortfall of $36,000 to OCI.
Under ASC 715, expected return 6 per cent on $3.4 million. Expected return?
Show answer
$204,000.
Opening AOCI net loss $900,000; obligation $5 million; assets $4.2 million; service period 12 years. Amortization?
Show answer
(900,000 − 500,000) ÷ 12 = $33,333.
Rerun the pension program with an expected return of 5 per cent. What happens to ASC 715 cost?
Show answer
The expected return falls to $425,000, so net periodic cost rises to $715,000; IAS 19 cost is unchanged.
A plan amendment raises past benefits by $300,000. IFRS treatment?
Show answer
Past service cost of $300,000 in profit or loss immediately.
Same amendment under US GAAP?
Show answer
Prior service cost in OCI, amortized over remaining service.
Why does a fall in the discount rate increase the obligation?
Show answer
Future benefits are discounted at a lower rate, raising their present value.
How might an analyst treat a $1.85 million pension deficit when computing leverage?
Show answer
Add it, after tax, to debt.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.