
ACCT-212 · Lesson 2 of 12 · 28 min
Provisions, contingent liabilities and contingent assets
Some obligations come with a known amount and due date: an invoice, a loan instalment, a payroll remittance. Others are uncertain. A customer sues; a product may fail under warranty; a mine site must be restored when operations end; a factory is to be closed and its workers paid severance. These obligations are real, but their timing, amount or even existence is uncertain. This lesson explains how each framework decides whether to recognize such an obligation, how to measure it, and what to disclose when it is not recognized. It is one of the areas where IFRS, ASPE and US GAAP use different words and different thresholds, so the same lawsuit can produce different numbers in Canada and the United States.
Provisions under IAS 37
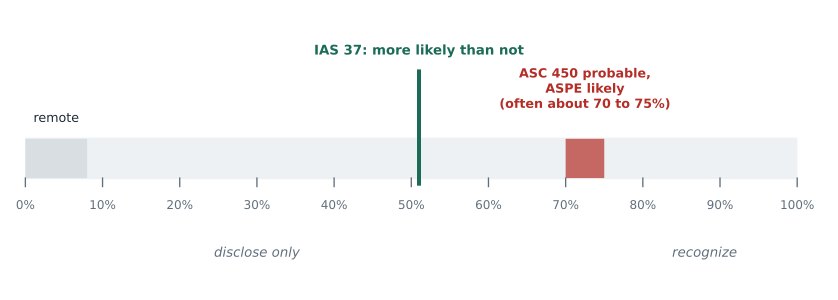
IAS 37, Provisions, Contingent Liabilities and Contingent Assets, defines a provision as a liability of uncertain timing or amount. A provision is recognized when three conditions are met: the entity has a present obligation, legal or constructive, as a result of a past event; it is probable, meaning more likely than not, that an outflow of resources will be required to settle it; and a reliable estimate of the amount can be made. If any condition fails, no provision is recognized. A possible obligation, or a present obligation that is not probable or cannot be measured reliably, is a contingent liability: it is disclosed unless the possibility of an outflow is remote. Words matter here. IFRS uses 'provision' for a recognized liability and 'contingent liability' only for an unrecognized one.
ASPE Section 3290, Contingencies, follows the older North American approach. A contingent loss is accrued when it is likely that a future event will confirm that an asset has been impaired or a liability incurred and the amount can be reasonably estimated. 'Likely' means the chance of occurrence is high, a stricter threshold than IFRS's more-likely-than-not. Contingencies that are not accrued are disclosed unless remote. In 2024 the IASB published an exposure draft of targeted improvements to IAS 37, mainly clarifying the present obligation test and the discount rate; as of 2026 the Board was still redeliberating, so the requirements described here remain in force.
Measuring the obligation
A provision is measured at the best estimate of the expenditure required to settle the present obligation at the reporting date: the amount the entity would rationally pay to settle it or transfer it to a third party. For a large population of similar items, such as product warranties, the best estimate is the expected value, weighting each outcome by its probability. For a single obligation, the most likely outcome is often the best estimate, adjusted if other outcomes are mostly higher or mostly lower. Where outcomes fall within a continuous range and every point is equally likely, IAS 37 uses the mid-point of the range. When the time value of money is material, the provision is discounted at a pre-tax rate reflecting current market assessments of the time value of money and the risks specific to the liability. Expected reimbursements, for example from an insurer, are recognized as a separate asset only when virtually certain.
Worked problem
A lawsuit under both frameworks
A customer has sued Northlake, claiming that a failed air-quality station caused it to miss regulatory reporting deadlines. Northlake's lawyers estimate a 60 per cent chance of losing. If it loses, damages are equally likely to be anywhere between $800,000 and $1,200,000. What is recognized at year end?
Show solution
- Present obligation: the failure occurred before year end, and an outflow is more likely than not (60 per cent).
- Reliable estimate: the range is known. With every point equally likely, IAS 37 uses the mid-point.
- Provision = (800,000 + 1,200,000) ÷ 2 = $1,000,000, charged to profit or loss.
- Under ASPE, a 60 per cent chance would usually not meet the higher 'likely' threshold, so a private enterprise would disclose rather than accrue.
Answer: Provision of $1,000,000 under IAS 37; disclosure only under ASPE.
Warranties and other expected-value provisions
ACCT-211 lesson 5 distinguished assurance-type warranties, which promise only that a product works as specified, from service-type warranties, which provide an extra service and are a separate performance obligation. Assurance-type warranties are a cost of the sale: a provision is recognized when the product is sold, measured at the expected cost of repairs and replacements for the units under warranty. Because Northlake sells hundreds of stations, the expected value approach fits.
# Assurance-type warranty provision for stations sold this year (expected value)
units_sold = 1_250
outcomes = [            # (share of units, cost per unit if it occurs)
    ("No claim",            0.82,      0),
    ("Minor repair",        0.13,    450),
    ("Sensor replacement",  0.04,  2_100),
    ("Full station swap",   0.01,  9_800),
]
assert abs(sum(p for _, p, _ in outcomes) - 1) < 1e-9
ev_per_unit = sum(p * c for _, p, c in outcomes)
provision = units_sold * ev_per_unit
for name, p, c in outcomes:
    print(f"{name:<20} {p:>5.0%}  x {c:>6,}  = {p * c:>8,.2f} per unit")
print(f"Expected cost per unit {ev_per_unit:,.2f}")
print(f"Warranty provision for {units_sold:,} units: {provision:,.0f}")
claims_paid = 180_000
print(f"Claims paid during the year reduce the provision to {provision - claims_paid:,.0f}")No claim 82% x 0 = 0.00 per unit Minor repair 13% x 450 = 58.50 per unit Sensor replacement 4% x 2,100 = 84.00 per unit Full station swap 1% x 9,800 = 98.00 per unit Expected cost per unit 240.50 Warranty provision for 1,250 units: 300,625 Claims paid during the year reduce the provision to 120,625
The expected cost per station is $240.50, so a provision of $300,625 is recognized for the year's sales, debited to warranty expense in cost of sales. As claims are paid, the provision is reduced; if actual experience differs from the estimate, the change is recognized in profit or loss of the period, not by restating past years. The same expected-value thinking applies to other large populations of small obligations, such as refunds for defective products and some environmental remediation programs.
Onerous contracts and restructurings
A contract is onerous when the unavoidable costs of meeting its obligations exceed the economic benefits expected under it. IAS 37 requires a provision for the lower of the cost of fulfilling the contract and any compensation or penalty for failing to fulfil it. A 2020 amendment, effective in 2022, clarified that the cost of fulfilling includes both incremental costs, such as direct labour and materials, and an allocation of other costs that relate directly to fulfilling contracts, such as depreciation of equipment used. Before recognizing an onerous contract provision, the entity first recognizes any impairment of assets dedicated to the contract.
A restructuring, such as closing a business line or relocating operations, gives rise to a provision only when the entity has a constructive obligation: a detailed formal plan identifying the business affected, locations, employees, expenditures and timing, and either the plan has started or its main features have been announced to those affected, raising a valid expectation that it will be carried out. A board decision alone is not enough. The provision includes only direct expenditures necessarily entailed by the restructuring, such as severance and contract termination costs, and excludes retraining, relocating continuing staff, marketing and future operating losses.
Decommissioning provisions
Many assets must be removed, dismantled or the site restored at the end of their lives: drilling rigs, mines, pipelines, nuclear plants, telecommunications towers and leased premises with make-good clauses. Under IAS 37 and IAS 16, a decommissioning provision is recognized when the obligation arises, usually on installation, at the present value of the expected cost. The same amount is added to the cost of the related asset and depreciated over its useful life. Each year the discount unwinds, increasing the provision, and the unwinding is a finance cost. Under IFRIC 1, changes in the estimated cost, timing or discount rate adjust both the provision and the asset. ASPE Section 3110 requires an asset retirement obligation for legal obligations only, measured similarly.
Worked problem
Station removal obligation
Northlake installs a network of remote monitoring stations on Crown land under a ten-year permit that requires removal of all equipment and restoration of the sites. The expected removal cost in ten years is $400,000. The pre-tax discount rate reflecting the risks of the liability is 5 per cent. What is recorded?
Show solution
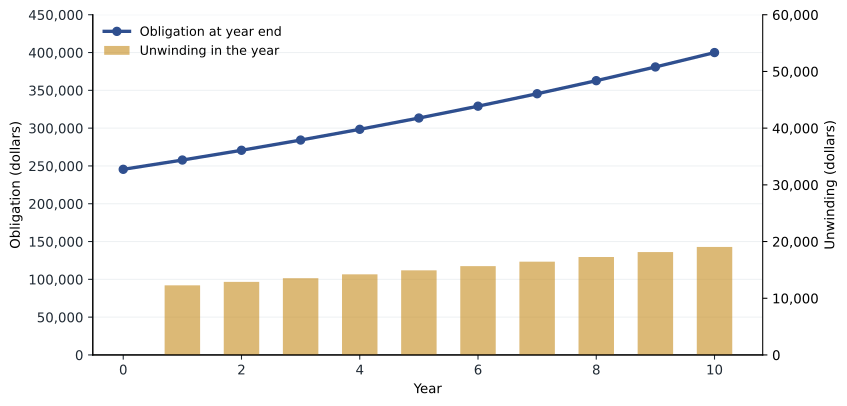
- Present value: 400,000 ÷ 1.05¹⁰ = $245,565.
- Debit the stations (property, plant and equipment) $245,565; credit the decommissioning provision $245,565.
- Depreciate the capitalized amount over ten years with the stations: $24,557 a year on a straight-line basis.
- Year 1 unwinding: 245,565 × 5% = $12,278, a finance cost.
Answer: Provision of $245,565 at installation, growing to $400,000 by year 10 as the discount unwinds.
# Unwinding the removal obligation: PV 245,565 at 5% over ten years
cost, rate, years = 400_000, 0.05, 10
balance = cost / (1 + rate) ** years
print(f"{'Year':>4} {'Opening':>10} {'Unwinding':>10} {'Closing':>10}")
for y in range(1, years + 1):
    unwind = balance * rate
    print(f"{y:>4} {balance:>10,.0f} {unwind:>10,.0f} {balance + unwind:>10,.0f}")
balance += unwindYear Opening Unwinding Closing 1 245,565 12,278 257,844 2 257,844 12,892 270,736 3 270,736 13,537 284,273 4 284,273 14,214 298,486 5 298,486 14,924 313,410 6 313,410 15,671 329,081 7 329,081 16,454 345,535 8 345,535 17,277 362,812 9 362,812 18,141 380,952 10 380,952 19,048 400,000
Contingent assets
A contingent asset is a possible asset arising from past events whose existence will be confirmed only by uncertain future events, such as a claim Northlake has filed against a supplier. Contingent assets are never recognized; when an inflow becomes virtually certain, the asset is no longer contingent and is recognized. A contingent asset is disclosed when an inflow is probable. The asymmetry, a provision at more likely than not but an asset only when virtually certain, reflects prudence in the face of uncertainty.
| Likelihood of outflow | IFRS (IAS 37) | ASPE (Section 3290) |
|---|---|---|
| Remote | No recognition or disclosure | No recognition or disclosure |
| Possible but not probable | Disclose as a contingent liability | Disclose if not remote |
| Probable (more likely than not), but not likely | Recognize a provision | Disclose |
| Likely (high probability) | Recognize a provision | Accrue if reasonably estimable |
| Range, no best estimate | Mid-point of the range | Minimum of the range, disclose the rest |
Disclosure and judgement
Disclosures about provisions and contingencies are among the most read notes in a set of financial statements. IAS 37 requires a reconciliation of each class of provision (opening balance, additions, amounts used, unused amounts reversed, unwinding and closing balance), a description of the nature and expected timing of outflows, and the major assumptions. US GAAP requires disclosure of the nature of accrued contingencies and, often, the amount, and of reasonably possible losses. Both frameworks allow an entity, in extremely rare cases, to withhold information that would seriously prejudice its position in a dispute, but it must still describe the general nature of the dispute.
Provisions involve more judgement than almost any other liability, which makes them a target for earnings management. A company can overstate a provision in a good year and release it in a bad one, smoothing profits; this was part of the pattern regulators found at Nortel Networks in the early 2000s. Auditors respond by testing management's estimates against legal letters, historical claims data and subsequent events, and by reviewing reversals of provisions recognized in earlier years. Readers should compare the reconciliation of provisions from year to year: large unused amounts reversed, or provisions that rise and fall with profits, deserve questions.
Common mistakes
MistakeRecognizing a provision because the board decided to restructure.
InsteadA constructive obligation needs a detailed plan that has started or been announced to those affected.
MistakeUsing the minimum of a range when every point is equally likely.
InsteadIAS 37 uses the mid-point in that case; US GAAP uses the minimum.
MistakeNetting an expected insurance recovery against the provision.
InsteadRecognize the recovery as a separate asset when it meets the framework's threshold.
MistakeRecognizing a contingent asset when a favourable outcome is probable.
InsteadContingent assets are recognized only when realization is virtually certain, or realized, depending on the framework; until then, disclose.
MistakeExpensing the full removal cost at the end of the asset's life.
InsteadRecognize the obligation when incurred at present value, add it to the asset and unwind the discount over time.
Summary and key terms
- A provision is a liability of uncertain timing or amount, recognized when an outflow is more likely than not and can be measured reliably.
- ASPE uses a higher 'likely' threshold for accruing contingencies.
- Provisions are measured at the best estimate: expected value for populations, most likely outcome for single obligations, mid-point for equally likely ranges.
- Assurance-type warranty costs are provided for when the product is sold.
- Onerous contracts and restructurings require provisions only in defined circumstances.
- Decommissioning provisions are capitalized, discounted and unwound as a finance cost; IFRIC 1 remeasures them for changes in estimates and rates.
- Contingent assets and gain contingencies are not recognized until realization is virtually certain or realized.
- Provision
- A liability of uncertain timing or amount.
- Contingent liability
- A possible obligation, or a present obligation that is not recognized because it is not probable or cannot be measured reliably.
- Contingent asset
- A possible asset whose existence will be confirmed only by uncertain future events.
- Decommissioning provision
- An obligation to dismantle an asset and restore its site.
- Remote
- Having only a slight chance of occurring.
- Best estimate
- The amount an entity would rationally pay to settle or transfer an obligation at the reporting date.
- Expected value
- A probability-weighted average of possible outcomes.
- Assurance-type warranty
- A promise that a product will work as specified, provided for as a cost of sale.
- Onerous contract
- A contract whose unavoidable costs exceed the benefits expected from it.
- Unwinding of the discount
- The annual increase in a discounted liability as settlement approaches.
- Constructive obligation
- An obligation arising from an entity's actions that create a valid expectation it will act.
- Restructuring
- A program planned and controlled by management that materially changes the scope or manner of a business.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A customer sues after year end over a product shipped before year end. Is there a past event?
Show answer
Yes; the shipment of a defective product occurred before year end.
Probability of losing 55 per cent; loss most likely $300,000. IFRS treatment?
Show answer
Recognize a provision of $300,000.
Range $2 million to $3 million, all points equally likely, outflow probable. Amount?
Show answer
$2.5 million.
Warranty: 90 per cent no claim, 8 per cent $200, 2 per cent $1,500 on 2,000 units. Provision?
Show answer
2,000 × (16 + 30) = $92,000.
Rerun the warranty program with 1,500 units. New provision?
Show answer
1,500 × 240.50 = $360,750.
Removal cost of $1 million in 20 years at 4 per cent. Initial obligation?
Show answer
1,000,000 ÷ 1.04²⁰ = $456,387.
Under IFRS, where is the unwinding of a decommissioning provision presented?
Show answer
As a finance cost.
A company has filed a claim that it will probably win. Recognize an asset?
Show answer
No; disclose it. Recognize only when realization is virtually certain or realized.
Which restructuring costs are included in the provision?
Show answer
Direct costs such as severance and contract termination; not retraining, relocation or future losses.
Why compare provision reconciliations across years?
Show answer
Large reversals or provisions that move with profits can signal earnings smoothing.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.