
ACCT-212 · Lesson 8 of 12 · 26 min
Income taxes II: losses, valuation, uncertainty and presentation
Lesson 7 assumed that Northlake was profitable every year, so every deferred tax asset would be used. Real companies make losses, take tax positions that tax authorities may challenge, and operate in several jurisdictions with different rates. This lesson covers the accounting for tax losses, the recognition and valuation of deferred tax assets, uncertain tax positions, the reconciliation of statutory and effective rates and other disclosures, the global minimum tax, and the simpler taxes payable method available to Canadian private enterprises.
Tax losses: carrybacks and carryforwards
When a company's deductions exceed its income, it has a net operating loss (NOL). Under federal law as amended by the Tax Cuts and Jobs Act of 2017, NOLs arising in tax years beginning after 31 December 2017 cannot generally be carried back (farming losses are an exception), but can be carried forward indefinitely, and may offset only 80 percent of taxable income in a future year. The CARES Act temporarily allowed five-year carrybacks for 2018 to 2020 losses. A carryback, where allowed, produces a current receivable; a carryforward produces a deferred tax asset. State NOL rules differ and must be tracked separately.
Worked problem
A tax loss in a difficult year
In 2029 a fire closes one of Northlake's plants for months, and the company has a net operating loss of $2,000,000. Taxable income in earlier years was $1,200,000 a year, taxed at 25 percent. How is the loss accounted for?
Show solution
- No carryback is allowed for a post-2017 loss.
- NOL carryforward: $2,000,000, giving a deferred tax asset of 2,000,000 × 25% = $500,000, recognized in full.
- Assess whether a valuation allowance is needed: is it more likely than not that some of the asset will not be realized? Northlake has a long record of profits and the loss was caused by an identifiable event, so none is recorded.
- In 2030, if taxable income before the NOL is $1,500,000, Northlake can use only 80 percent: $1,200,000 of the NOL, leaving $800,000 to carry forward.
Answer: Deferred tax asset of $500,000, with no carryback and an 80 percent annual limit on use.
Valuation allowances
ASC 740 recognizes a deferred tax asset for all deductible temporary differences and carryforwards, then reduces it by a valuation allowance if, based on the weight of available evidence, it is more likely than not (a likelihood of more than 50 percent) that some portion will not be realized. Positive evidence includes existing taxable temporary differences that will reverse, a strong earnings history and tax planning strategies; negative evidence includes cumulative losses in recent years, which is significant negative evidence that is difficult to overcome, a history of carryforwards expiring unused and losses expected in early future years. The gross asset and the allowance are both disclosed. Releasing an allowance when a company returns to profit can produce a large one-time tax benefit.
Both frameworks reach similar answers in most cases, but presentation differs: a US company discloses a gross deferred tax asset and a valuation allowance, while an IFRS company reports only the net amount it recognizes, with the unrecognized amount disclosed in the notes. Readers should watch for changes in these amounts. A company that reverses a large valuation allowance, or recognizes previously unrecognized losses, can report a tax benefit that makes net income look far better than operating results. Conversely, recording a new allowance signals that management has lost confidence in future profits.
Uncertain tax positions
Tax law is complex, and companies often take positions on their returns, such as the deductibility of an expense or the pricing of transactions between related companies in different countries, that a tax authority may challenge. The question for financial reporting is how much of the benefit of such a position to recognize before it is settled.
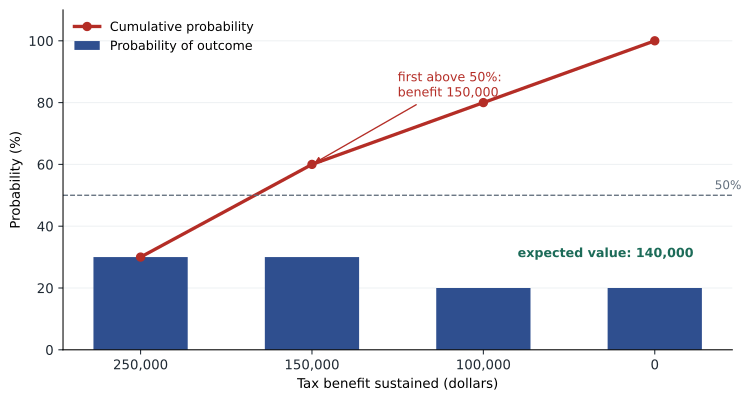
ASC 740-10 uses a two-step approach to uncertain tax positions. Recognition: a benefit is recognized only if it is more likely than not, based on its technical merits, that the position will be sustained on examination, assuming the authority has full knowledge. Measurement: the benefit recognized is the largest amount that is more than 50 percent likely to be realized on settlement, determined from the cumulative probabilities of possible outcomes. The difference between the benefit claimed on the return and the benefit recognized is an unrecognized tax benefit, recorded as a liability (or a reduction of a deferred tax asset). Interest and penalties are accrued, and companies disclose a tabular roll-forward of unrecognized tax benefits.
# Uncertain tax position: a deduction worth $250,000 of tax if fully sustained
outcomes = [   # (tax benefit sustained, probability)
    (250_000, 0.30),
    (150_000, 0.30),
    (100_000, 0.20),
    (      0, 0.20),
]
expected = sum(b * p for b, p in outcomes)
print(f"Expected value of the benefit: {expected:,.0f}")
most_likely = max(outcomes, key=lambda o: o[1])
print(f"Highest single probability: {most_likely[1]:.0%} (ties possible)")

# ASC 740: largest amount with cumulative probability above 50%
cum = 0
for benefit, p in sorted(outcomes, reverse=True):
    cum += p
    print(f"  benefit {benefit:>8,}  cumulative probability {cum:.0%}")
    if cum > 0.5:
        print(f"ASC 740 measures the benefit at {benefit:,}; unrecognized tax benefit {250_000 - benefit:,}")
breakExpected value of the benefit: 140,000 Highest single probability: 30% (ties possible) benefit 250,000 cumulative probability 30% benefit 150,000 cumulative probability 60% ASC 740 measures the benefit at 150,000; unrecognized tax benefit 100,000
Northlake's position passes the recognition step: its advisers believe the deduction is more likely than not to be sustained in some amount on its technical merits. For measurement, the cumulative probability first exceeds 50 percent at $150,000, so Northlake recognizes a $150,000 benefit and records a $100,000 unrecognized tax benefit as a liability. An IFRS reporter would usually recognize the expected value, $140,000, because full acceptance is not probable. The two answers are close here but can differ substantially.
The rate reconciliation and other disclosures
Tax disclosures explain why the effective tax rate differs from the statutory rate. The rate reconciliation starts with pre-tax profit times the statutory rate and lists the effects of permanent differences, different rates in other jurisdictions, changes in tax rates, changes in valuation allowances or unrecognized assets, and adjustments for prior years. Readers use it to judge whether a low tax rate is sustainable: a rate held down by tax credits for research may persist; one held down by releasing a valuation allowance will not.
Worked problem
Northlake's 2027 rate reconciliation
Using lesson 7's numbers: pre-tax income $6,000,000; combined rate 25 percent (21 percent federal plus state); non-deductible meals $40,000. Reconcile to tax expense.
Show solution
- Tax at the federal statutory rate: 6,000,000 × 21% = $1,260,000.
- State income tax, net of the federal benefit: $240,000 (4 percentage points).
- Non-deductible meals: 40,000 × 25% = $10,000.
- Tax expense: $1,510,000; effective rate 25.17 percent.
Answer: Effective rate 25.17 percent, reconciled to the 21 percent federal rate.
ASU 2023-09, effective for public business entities for annual periods beginning after 15 December 2024 and for other entities a year later, expanded income tax disclosures. Public business entities must present the rate reconciliation in both percentages and amounts, using specified categories (state and local tax, foreign tax effects, effects of changes in tax laws, cross-border tax laws, tax credits, valuation allowances, non-taxable or non-deductible items and changes in unrecognized tax benefits), with separate disclosure of items meeting a 5 percent threshold. All entities must disclose income taxes paid, disaggregated by federal, state and foreign jurisdictions, with separate disclosure of any jurisdiction above 5 percent of the total.
The global minimum tax
The OECD's Pillar Two rules impose a 15 percent minimum effective tax rate on large multinational groups with consolidated revenue of at least €750 million. The United States has not enacted Pillar Two, relying instead on its own minimum taxes, including the global intangible low-taxed income regime and the 15 percent corporate alternative minimum tax on adjusted financial statement income of large corporations introduced by the Inflation Reduction Act of 2022. In 2025 the G7 announced a 'side-by-side' approach intended to exempt US-parented groups from some Pillar Two rules; check the current status. US multinationals with operations in countries that have adopted Pillar Two may still owe top-up taxes there, which they treat as period costs rather than deferred taxes.
Private companies and the IFRS comparison
US private companies apply ASC 740 in full; there is no taxes payable alternative, although private companies are exempt from some disclosures, such as the tabular roll-forward of unrecognized tax benefits. By contrast, Canadian private enterprises using ASPE can choose the taxes payable method, recognizing only current tax. An IFRS reporter applies IAS 12, which differs from ASC 740 in several details covered in this lesson and lesson 7: substantively enacted rates, the initial recognition exception, uncertain tax positions under IFRIC 23, and presentation of deferred tax assets net of unrecognized amounts rather than with a valuation allowance.
| Topic | US GAAP (ASC 740) | IFRS (for comparison) |
|---|---|---|
| Deferred tax asset recognition | Recognize in full, less a valuation allowance | Recognize to the extent probable |
| Rate changes | Enacted | Substantively enacted |
| Uncertain positions | More likely than not, then largest amount above 50 percent cumulative | IFRIC 23: probable acceptance, else most likely or expected value |
| Loss carrybacks | Federal: none after 2017; indefinite forward, 80 percent limit | Canada: 3 years back, 20 forward |
| Private company option | None; full ASC 740 | Canada's ASPE allows the taxes payable method |
Reading a tax note: a short case
Suppose a competitor's notes show pre-tax income of $40 million, tax expense of $6 million and an effective rate of 15 percent against a statutory rate of about 25 percent. The rate reconciliation lists three items: research and development tax credits worth 3 percentage points, lower rates in foreign jurisdictions worth 2 points, and the release of a valuation allowance (or recognition of previously unrecognized losses) worth 5 points. The deferred tax note shows that the released amount related to losses in a subsidiary that has now been profitable for two years. A careful reader would conclude that the credits and foreign rates may persist, but the 5-point benefit is a one-time event. A normalized effective rate is about 20 percent, and normalized net income is about $32 million rather than $34 million.
The same reader would check the gross deferred tax assets, the valuation allowance and its change during the year, the expiry schedule of NOLs (state NOLs and pre-2018 federal NOLs still expire), and the tabular roll-forward of unrecognized tax benefits, including amounts that would affect the effective rate if recognized and any expected changes in the next twelve months because of audits or lapsing statutes of limitations. Under ASU 2023-09, public companies also show income taxes paid by jurisdiction, which reveals where cash taxes are actually paid. Taken together, these notes let an analyst separate recurring tax costs from accounting events.
Common mistakes
MistakeNever recording a valuation allowance because the deferred tax asset is recognized in full.
InsteadReduce the asset by a valuation allowance when realization is not more likely than not.
MistakeTreating a loss carryback refund as a deferred tax asset.
InsteadA carryback refund is a current tax receivable.
MistakeRecognizing the expected value of an uncertain tax position.
InsteadASC 740 recognizes the largest amount with a cumulative likelihood above 50 percent.
MistakeAssuming a low effective tax rate is sustainable.
InsteadRead the rate reconciliation: one-time items such as allowance releases will not recur.
MistakeAssuming the 80 percent limit applies to pre-2018 NOLs.
InsteadPre-2018 NOLs are not subject to the 80 percent limit but expire after twenty years.
Summary and key terms
- Post-2017 federal NOLs carry forward indefinitely with an 80 percent annual limit and no carryback.
- Deferred tax assets are recognized in full and reduced by a valuation allowance when realization is not more likely than not.
- Recent losses are strong negative evidence against recognizing deferred tax assets.
- ASC 740 recognizes uncertain benefits only if more likely than not, measured at the largest amount over 50 percent cumulative.
- The rate reconciliation explains differences between statutory and effective rates.
- ASU 2023-09 expands rate reconciliation and taxes-paid disclosures.
- US private companies apply ASC 740 in full.
- Net operating loss
- Tax deductions exceeding taxable income in a year.
- Valuation allowance
- A reduction of a deferred tax asset for the portion not more likely than not to be realized.
- Unrecognized tax benefit
- The difference between a benefit claimed on a return and the amount recognized in the financial statements.
- Tax loss carryforward
- An unused tax loss available to reduce future taxable income.
- Tax loss carryback
- Applying a current tax loss against prior years' taxable income to obtain a refund.
- Uncertain tax position
- A tax treatment whose acceptance by the tax authority is uncertain.
- Rate reconciliation
- A disclosure explaining differences between the statutory and effective tax rates.
- Pillar Two
- OECD rules imposing a 15 percent global minimum tax on large multinational groups.
- Top-up tax
- Additional tax that brings a group's effective rate in a jurisdiction up to 15 percent.
Practice problems
Work each problem on paper first, then reveal the answer to check.
NOL of $500,000; rate 25 percent. Deferred tax asset?
Show answer
$125,000, less any valuation allowance.
An entity has three years of cumulative losses. Valuation allowance?
Show answer
Likely; cumulative losses are significant negative evidence.
Outcomes: $100,000 at 40 percent, $60,000 at 30 percent, $0 at 30 percent. Expected value?
Show answer
$58,000.
Same outcomes. Largest amount with cumulative probability above 50 percent?
Show answer
$60,000 (40 then 70 percent).
Rerun the uncertain-position program with probabilities 0.55, 0.15, 0.15, 0.15. ASC 740 amount?
Show answer
$250,000, because the first outcome alone exceeds 50 percent.
Pre-tax profit $2 million; rate 25 percent; tax credit of $40,000. Effective rate?
Show answer
23 percent.
Why is a valuation allowance release a warning sign for analysts?
Show answer
It produces a one-time tax benefit that inflates net income.
Taxable income before NOL $1 million; NOL available $2 million (post-2017). NOL usable this year?
Show answer
$800,000 (80 percent of taxable income).
Which group size triggers Pillar Two?
Show answer
Consolidated revenue of at least €750 million.
What does the taxes-paid disclosure show?
Show answer
Income taxes paid by federal, state and foreign jurisdiction.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.