
ACCT-212 · Lesson 1 of 12 · 31 min
Current liabilities
ACCT-211 followed Northlake Instruments, the invented maker of weather and air-quality sensor stations, through the asset side of its statement of financial position. This course turns to the other side: what the company owes and what belongs to its owners. Liabilities matter to every reader of financial statements. Lenders use them to judge whether a borrower can repay; suppliers use them to decide whether to extend credit; investors use them to understand how much of the business is financed by others and how much risk that creates. Because managers sometimes have reasons to make liabilities look smaller, the rules for when to recognize them, how to measure them and how to classify them are among the most carefully argued in accounting.
This first lesson covers the liabilities a business settles within its normal operating cycle: trade payables, short-term borrowings, the current portion of long-term debt, sales taxes, payroll and benefits, customer deposits and accrued expenses. Later lessons take up estimated liabilities (lesson 2), long-term debt (lessons 3 and 4), leases (lessons 5 and 6), income taxes (lessons 7 and 8) and pensions (lesson 9), before the course turns to equity.
What a liability is
FASB Concepts Statement No. 6 has long defined liabilities as probable future sacrifices of economic benefits arising from present obligations. In December 2021 the FASB issued a revised Chapter 4 of Concepts Statement No. 8, which defines a liability more simply as a present obligation of an entity to transfer an economic benefit. The FASB removed the word 'probable' because it was often confused with the recognition threshold for loss contingencies. The IASB's 2018 framework uses almost the same wording, so the two boards now describe liabilities in nearly identical terms.
An obligation is not the same as an intention. A board decision to spend money next year on advertising creates no liability, because the company can still change its mind. A signed purchase order for goods not yet delivered is usually an executory contract: neither party has performed, so neither records an asset or liability until delivery, unless the contract has become onerous (lesson 2). By contrast, goods received before the invoice arrives create a liability at once, because the supplier has performed.
Classifying liabilities as current or non-current
Under ASC 210 and ASC 470, current liabilities are obligations expected to be settled with current assets or by creating other current liabilities, generally within one year or the operating cycle if longer. Short-term obligations expected to be refinanced may be classified as non-current if the entity intends to refinance them on a long-term basis and demonstrates the ability to do so, either by actually refinancing after the balance sheet date but before the financial statements are issued, or by entering into a qualifying financing agreement. IFRS takes a stricter view: refinancing after the reporting date is a non-adjusting event, so the liability remains current. Lesson 4 returns to covenant breaches and waivers, where the two frameworks also differ.
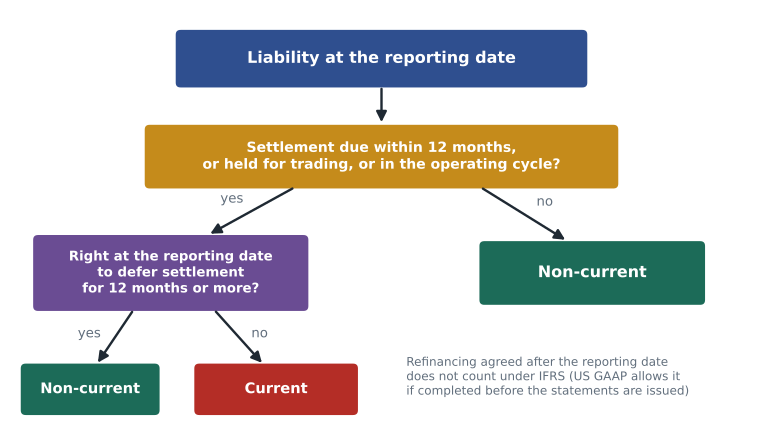
Worked problem
Classifying a maturing loan
Northlake has a $3 million bank loan due on 30 June 2027. Its year end is 31 December 2026, and the financial statements are issued on 20 February 2027. On 15 February 2027 the bank signs an agreement extending the loan to 2031. How is the loan classified at 31 December 2026?
Show solution
- At 31 December 2026 the loan is due within one year.
- ASC 470-10 allows non-current classification when a short-term obligation is refinanced on a long-term basis after the balance sheet date but before the statements are issued.
- The refinancing was completed on 15 February, before issuance on 20 February, so the loan may be classified as non-current.
- Under IFRS the same loan would be current, because the right to defer did not exist at the reporting date.
Answer: Non-current under US GAAP; it would be current under IFRS.
Trade payables, notes and accrued liabilities
Accounts payable, also called trade payables, are amounts owed to suppliers for goods and services bought on credit. They are recorded when title to goods passes or services are received, at the invoice amount. Purchase discounts can be recorded using the gross method, which records purchases at the invoice price and recognizes discounts taken, or the net method, which records purchases net of available discounts and recognizes discounts lost as a finance cost. The net method better reflects the cost of the goods and highlights the expensive financing implicit in missing a 2/10, net 30 discount, which works out to an annual rate of more than 36 percent.
Short-term notes payable are written promises to pay, often to banks. Interest-bearing notes are recorded at face value and accrue interest over time. A non-interest-bearing note carries an implicit interest charge: the borrower receives less than the face amount and records the difference as a discount that is amortized to interest expense. Lines of credit and bank overdrafts are current liabilities; under IAS 7 an overdraft repayable on demand that is an integral part of cash management may be netted with cash in the cash flow statement, but not on the statement of financial position unless the offset criteria are met.
The current portion of long-term debt is the principal due within twelve months. It is reclassified to current liabilities each year end, together with accrued interest. Dividends payable arise when the board declares a cash dividend, because declaration creates a legal obligation to shareholders (lesson 10). Accrued liabilities, also called accrued expenses, are costs incurred but not yet invoiced or paid at year end: interest, utilities, wages, professional fees and property taxes. Customer deposits and contract liabilities arise when customers pay before the entity performs; ACCT-211 lesson 4 covered their treatment under the revenue standard. Gift cards and loyalty points create contract liabilities that are reduced as they are redeemed or as breakage is recognized.
Sales taxes collected
A US business that has nexus in a state, either a physical presence or, since the Supreme Court's 2018 decision in South Dakota v. Wayfair, sufficient economic activity, must collect state and local sales tax from customers. The tax collected is not revenue: it is credited to sales taxes payable and remitted to each state on its schedule. Unlike Canada's GST/HST, US sales taxes generally do not give businesses credits for tax paid on purchases; instead, purchases for resale are exempt under resale certificates, and tax paid on other purchases is part of their cost. Many states set economic nexus thresholds at $100,000 of sales, sometimes combined with a transaction count.
Worked problem
Recording sales taxes
Northlake sells a station in a state with a 6 percent sales tax for $40,000 plus tax. In the same month it buys components for resale under a resale certificate. Record the effect on sales taxes payable.
Show solution
- Sale: debit receivable $42,400; credit revenue $40,000; credit sales taxes payable $2,400.
- Purchase for resale under a resale certificate: no sales tax is charged; debit inventory $10,000, credit payables $10,000.
- Sales tax owing: $2,400, remitted to the state by the due date.
Answer: Sales taxes payable of $2,400; none of it is revenue.
Payroll liabilities
Payroll creates several liabilities at once. The employer owes employees their net pay. It also withholds amounts from employees' gross pay, such as income tax and the employee share of social insurance contributions, and owes these to the government. On top of that it incurs its own payroll taxes and benefit costs, which are an expense in addition to gross wages. The withholdings and employer contributions are current liabilities until remitted, usually within weeks.
In the United States the main statutory items for 2026 (illustrative; confirm current rates with the IRS) are Social Security tax of 6.2 percent on wages up to the $184,500 wage base and Medicare tax of 1.45 percent on all wages, together called FICA, withheld from employees and matched by employers; an additional 0.9 percent Medicare tax withheld from employees on wages above $200,000; federal unemployment tax (FUTA) of 6.0 percent on the first $7,000 of each employee's wages, reduced to an effective 0.6 percent by credits for state unemployment taxes; state unemployment tax (SUTA) at rates set by experience rating; and federal, state and sometimes local income tax withheld under the employee's W-4.
# One employee's monthly payroll in a US state (2026 rates, illustrative)
gross = 6_000.00
ss_rate, medicare_rate = 0.062, 0.0145
futa_rate, futa_base_left = 0.006, 7_000      # first month of the year
suta_rate = 0.027                             # experience-rated (illustrative)
income_tax = 1_010.00                         # federal and state withholding (illustrative)

ss = round(gross * ss_rate, 2)
medicare = round(gross * medicare_rate, 2)
net_pay = gross - ss - medicare - income_tax
futa = round(min(gross, futa_base_left) * futa_rate, 2)
suta = round(gross * suta_rate, 2)            # state wage bases vary

print(f"Gross wages                    {gross:>10,.2f}")
print(f"  Social Security withheld     {ss:>10,.2f}")
print(f"  Medicare withheld            {medicare:>10,.2f}")
print(f"  Income tax withheld          {income_tax:>10,.2f}")
print(f"Net pay owed to the employee   {net_pay:>10,.2f}")
print(f"Employer FICA (matching)       {ss + medicare:>10,.2f}")
print(f"Employer FUTA                  {futa:>10,.2f}")
print(f"Employer SUTA                  {suta:>10,.2f}")
print(f"Total cost to the employer {gross + ss + medicare + futa + suta:>10,.2f}")Gross wages 6,000.00 Social Security withheld 372.00 Medicare withheld 87.00 Income tax withheld 1,010.00 Net pay owed to the employee 4,531.00 Employer FICA (matching) 459.00 Employer FUTA 36.00 Employer SUTA 162.00 Total cost to the employer 6,657.00
The program shows why payroll is more expensive than the salary figure suggests. Northlake's $6,000 employee costs the company about $6,657 in the first month once employer FICA, FUTA and SUTA are added, before health insurance or paid leave. Each month Northlake owes the employee $4,531.00 and owes the IRS and the state the withholdings plus its own taxes, all current liabilities until paid. FUTA stops once an employee's wages pass $7,000, so the employer's cost per employee is highest early in the year.
Compensated absences and bonuses
Under ASC 710, an employer accrues a liability for compensated absences, such as vacation, when the employees' rights relate to services already rendered, the rights vest or accumulate, payment is probable and the amount can be reasonably estimated. Sick pay that accumulates but does not vest may be accrued but need not be. There is no federal minimum vacation requirement in the United States; vacation is a matter of employer policy, contracts and state law, and some states, such as California, require accrued vacation to be paid out at termination. Bonuses are accrued when it is probable they will be paid and the amount can be estimated, typically by year end for a plan based on that year's results.
Worked problem
Accruing vacation pay
At 31 December 2026, Northlake's 120 employees have earned 1,400 days of unused vacation that carries forward to 2027. The average daily pay rate expected in 2027, when the vacation will be taken, is $310, and employer payroll costs add 9 percent. What liability is recognized?
Show solution
- Days earned but untaken: 1,400.
- Measure at the rate expected to be paid: 1,400 × $310 = $434,000.
- Add employer payroll costs that will arise when the vacation is paid: 434,000 × 9% = $39,060.
- Accrued vacation liability: $473,060, with the change from last year recognized as wage expense.
Answer: Accrued vacation of about $473,000, a current liability because the days are expected to be taken in 2027.
| Liability | Typical measurement | Usual classification |
|---|---|---|
| Trade payables | Invoice amount (net of expected discounts under the net method) | Current |
| Short-term notes and lines of credit | Face value plus accrued interest, or present value for non-interest-bearing notes | Current |
| Current portion of long-term debt | Principal due within twelve months | Current |
| Sales taxes payable | Tax collected less recoverable tax paid, where allowed | Current |
| Payroll withholdings and employer taxes | Statutory rates applied to wages | Current |
| Accrued vacation and bonuses | Amount expected to be paid, including payroll costs | Mostly current |
| Contract liabilities and deposits | Consideration received before performance | Current or non-current by expected performance |
Analyzing short-term liquidity
Readers use current liabilities to assess liquidity. The current ratio divides current assets by current liabilities; the quick ratio divides cash, short-term investments and receivables by current liabilities; and days payable outstanding, accounts payable divided by cost of sales times 365, shows how long the company takes to pay suppliers. A company can improve these ratios at year end by paying down payables just before the reporting date, delaying purchases or, where the framework allows, reclassifying debt as non-current. Readers should therefore look at the notes on refinancing, covenant compliance and the maturity analysis of financial liabilities that IFRS 7 requires, and US companies disclose under ASC 470 and SEC rules.
Supplier finance arrangements, sometimes called reverse factoring, deserve special attention. A bank pays the company's suppliers early and the company pays the bank later, often on extended terms. The company's operating cash flow looks stronger because payments to suppliers become payments to a bank. ASU 2022-04, effective for fiscal years beginning after 15 December 2022 (with a roll-forward requirement from 2024), now requires buyers to disclose the key terms of these programs, the amount outstanding and a roll-forward of obligations.
Common mistakes
MistakeTreating sales tax collected from customers as revenue.
InsteadSales tax collected is a liability to the government; only the price excluding tax is revenue.
MistakeRecording only the gross wage as payroll expense.
InsteadAdd the employer's own payroll taxes and benefit costs; withholdings are liabilities, not extra expense.
MistakeAssuming IFRS and US GAAP treat refinancing after year end the same way.
InsteadUS GAAP allows non-current classification if refinancing is completed before issuance; IFRS does not.
MistakeRecording a liability for a purchase order when no goods have been received.
InsteadAn executory contract creates no liability until one party performs, unless it is onerous.
MistakeIgnoring unused vacation at year end.
InsteadAccumulating paid absences are a liability measured at the amount expected to be paid.
Summary and key terms
- A liability is a present obligation to transfer an economic resource as a result of past events.
- Under US GAAP a short-term obligation refinanced on a long-term basis before the statements are issued may be classified as non-current.
- Trade payables, short-term notes, the current portion of long-term debt, dividends payable and accrued expenses are the core current liabilities.
- Sales taxes collected are a liability; resale purchases are exempt rather than credited.
- Payroll creates liabilities for net pay, withholdings and the employer's own payroll taxes.
- Accumulating vacation and earned bonuses are accrued at the amount expected to be paid.
- Liquidity ratios and supplier finance disclosures help readers judge short-term risk.
- FICA
- Federal Insurance Contributions Act taxes for Social Security and Medicare.
- Liability
- A present obligation of the entity to transfer an economic resource as a result of past events.
- Constructive obligation
- An obligation created by past practice or published policy that leaves the entity no realistic alternative but to settle.
- Executory contract
- A contract under which neither party has yet performed.
- Current liability
- An obligation expected to be settled within twelve months or the operating cycle.
- Accrued liability
- An expense incurred but not yet paid or invoiced at the reporting date.
- Current portion of long-term debt
- Principal of long-term borrowings due within twelve months.
- Withholdings
- Amounts deducted from employees' pay that the employer must remit to governments or others.
- Compensated absences
- Paid time off, such as vacation, earned by employees.
- Supplier finance arrangement
- A program in which a finance provider pays suppliers and the buyer pays the provider later.
- Quick ratio
- Cash, short-term investments and receivables divided by current liabilities.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Is a signed contract to buy equipment next month a liability today?
Show answer
No; it is executory until the equipment is delivered.
A loan due in six months is refinanced for five years after year end but before the statements are issued. Classification?
Show answer
Non-current under US GAAP; current under IFRS.
Terms 2/10, net 30. Approximate annual cost of skipping the discount?
Show answer
2/98 × 365/20 ≈ 37 percent.
Sales of $10,000 plus a 7 percent sales tax. Sales taxes payable?
Show answer
$700.
Gross pay of $5,000 a month. Employee Social Security and Medicare?
Show answer
$310.00 and $72.50.
Why is employer payroll tax an expense but income tax withheld from employees is not?
Show answer
Withheld tax is part of the employee's gross wage; employer tax is an extra cost.
Rerun the payroll program with gross pay of $8,000. What happens to net pay?
Show answer
Withholdings rise with gross pay, so net pay rises by less than $2,000.
Unused vacation of 500 days at $280 a day plus 10 percent payroll costs. Liability?
Show answer
500 × 280 × 1.10 = $154,000.
A board approves a voluntary advertising campaign for next year. Liability?
Show answer
No; the company can still avoid the spending.
Current assets $4.2 million; current liabilities $3.0 million; inventory $1.5 million. Current and quick ratios (assume no prepaids)?
Show answer
Current 1.4; quick (4.2 − 1.5) ÷ 3.0 = 0.9.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.