
ACCT-212 · Lesson 11 of 12 · 27 min
Share-based payment and earnings per share
Many companies pay part of their employees' compensation in shares or share options rather than cash. Options align employees' interests with shareholders', conserve cash for young companies and help retain staff who would lose unvested awards by leaving. For decades, however, most companies recorded no expense for options granted at the market price, because the options had no 'intrinsic value' on the grant date. After years of debate, both boards concluded that options are valuable compensation and must be expensed at fair value: the IASB in IFRS 2 (2004) and the FASB in what is now ASC 718 (2004). This lesson explains how, and then turns to earnings per share, where options, convertible debt and preferred shares all affect the number that investors watch most closely.
Measuring equity-settled share-based payment
ASC 718, Compensation – Stock Compensation, requires the cost of employee services received in exchange for equity-classified awards, such as stock options and restricted stock units settled in shares, to be measured at the grant-date fair value of the award. Fair value is not remeasured later for equity-classified awards. For options, fair value is estimated with an option-pricing model, such as Black–Scholes–Merton or a lattice model, using the share price, exercise price, expected term, expected volatility, expected dividends and the risk-free rate. Non-public companies may use a calculated value based on an industry index's volatility, or the intrinsic value for some liability awards. FIN-301 lesson 11 derives the Black–Scholes formula.
The cost is recognized over the vesting period, the period during which employees must work to earn the award. Service conditions, such as remaining employed for four years, and non-market performance conditions, such as reaching a revenue target, affect how many awards are expected to vest, not their fair value per unit; the entity estimates the number expected to vest and trues up to the actual number at the end. Market conditions, such as a target share price, are built into the grant-date fair value and are not trued up: the cost is recognized even if the market condition is never met, as long as the service condition is.
Worked problem
Options with four-year cliff vesting
On 1 January 2027 Northlake grants 100,000 options to senior managers with an exercise price of $24, equal to the share price. The options vest at the end of four years if the managers are still employed (cliff vesting) and expire after ten years. Northlake estimates a fair value of $7.08 per option using Black–Scholes with an expected life of five years, volatility of 30 percent, a dividend yield of 1 percent and a risk-free rate of 3.5 percent. It expects 92 percent of the options to vest.
Show solution
- Total expected cost: 100,000 × 92% × $7.08 = about $651,400.
- Annual expense: 651,400 ÷ 4 = about $162,800, debited to compensation expense and credited to contributed surplus (or APIC).
- If at the end of year 2 the expected vesting rate falls to 88 percent, cumulative expense is trued up: 100,000 × 88% × 7.08 × 2/4 = $311,520, so year 2 expense is 311,520 − 162,840 = $148,680.
- If the share price stays below $24 and the options are never exercised, the expense already recognized is not reversed.
Answer: About $162,800 of compensation expense a year, adjusted for changes in expected forfeitures.
# Black-Scholes value of an employee option and the cost recognized each year
from math import log, sqrt, exp, erf
N = lambda x: 0.5 * (1 + erf(x / sqrt(2)))
S, K, T, sigma, r, q = 24.0, 24.0, 5.0, 0.30, 0.035, 0.01
d1 = (log(S / K) + (r - q + sigma ** 2 / 2) * T) / (sigma * sqrt(T))
d2 = d1 - sigma * sqrt(T)
value = S * exp(-q * T) * N(d1) - K * exp(-r * T) * N(d2)
print(f"Fair value per option: {value:.2f}")

options, vest_years = 100_000, 4
expected_rate = [0.92, 0.88, 0.88, 0.86]       # estimate at the end of each year
cum_prev = 0
for y, rate in enumerate(expected_rate, start=1):
    cum = options * rate * round(value, 2) * y / vest_years
    print(f"Year {y}: expected vesting {rate:.0%}, cumulative cost {cum:,.0f}, expense {cum - cum_prev:,.0f}")
cum_prev = cumFair value per option: 7.08 Year 1: expected vesting 92%, cumulative cost 162,840, expense 162,840 Year 2: expected vesting 88%, cumulative cost 311,520, expense 148,680 Year 3: expected vesting 88%, cumulative cost 467,280, expense 155,760 Year 4: expected vesting 86%, cumulative cost 608,880, expense 141,600
Graded vesting, forfeitures and modifications
Many awards vest in installments, for example 25 percent at the end of each of four years (graded vesting). For awards with only service conditions, ASC 718 allows a policy choice: recognize cost straight-line over the whole vesting period, as long as cumulative cost at least equals the portion vested, or treat each tranche separately as IFRS 2 requires. Most US companies choose straight-line. Since ASU 2016-09, companies may also elect to account for forfeitures when they occur rather than estimating them. Modifications such as repricings require recognition of incremental fair value over the remaining service period.
Worked problem
Graded vesting compared
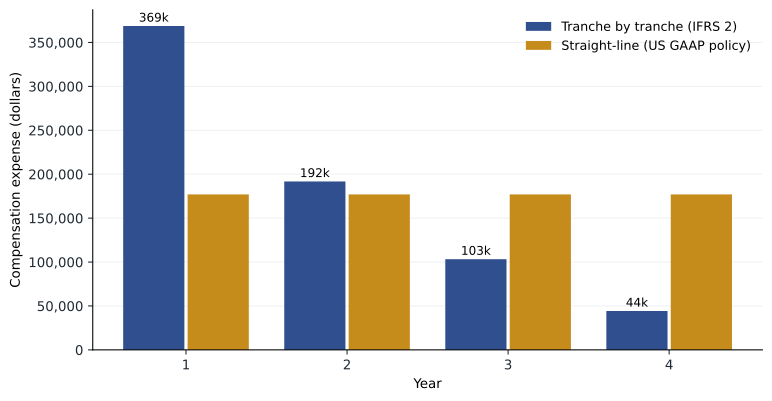
Suppose Northlake's options instead vest 25 percent a year over four years, total fair value $708,000 (ignore forfeitures, and assume each tranche has the same value). What is the year 1 expense?
Show solution
- Straight-line policy: 708,000 ÷ 4 = $177,000 a year, checking that cumulative cost covers vested tranches (year 1: $177,000 ≥ the $177,000 vested).
- Tranche-by-tranche policy (as IFRS 2 requires): 177,000 × (1 + 1/2 + 1/3 + 1/4) = $368,750 in year 1.
- Most US companies choose straight-line, so their early-year expense is lower than an IFRS reporter's.
- Total expense over four years is $708,000 either way.
Answer: $177,000 in year 1 straight-line, or $368,750 tranche by tranche.
Cash-settled awards and tax effects
Liability-classified awards, such as stock appreciation rights settled in cash, are remeasured at fair value each reporting date until settlement, with changes recognized in compensation cost. In the United States, the employer receives a tax deduction for nonqualified stock options equal to the intrinsic value at exercise. A deferred tax asset is recognized as compensation cost is booked, and since ASU 2016-09 the difference between the deduction and the recognized cost (an excess tax benefit or shortfall) is recognized in income tax expense, which can make the effective tax rate swing with the share price. Incentive stock options generally produce no deduction for the employer.
Basic earnings per share
Earnings per share (EPS) is profit attributable to ordinary (common) shareholders divided by the weighted average number of ordinary shares outstanding during the period. ASC 260 requires public entities to present basic and diluted EPS on the face of the income statement. Private companies are not required to present EPS.
The numerator deducts preferred dividends: the current year's dividend on cumulative preferred shares, whether or not declared, and dividends declared on non-cumulative preferred shares. Dividends on preferred shares classified as liabilities are already in interest expense.
The denominator weights each share by the fraction of the year it was outstanding. Shares issued for cash are weighted from the issue date; shares repurchased are removed from the repurchase date. Stock dividends, stock splits and the bonus element of rights issues change the number of shares without changing resources, so they are applied retroactively to all periods presented, as if they had occurred at the start of the earliest period, even if they happen after year end but before the statements are issued.
Diluted earnings per share
Diluted EPS shows what EPS would be if all dilutive potential ordinary shares had been issued: options and warrants, convertible debt and convertible preferred shares, and contingently issuable shares. Each potential share is included only if it is dilutive, that is, if it would reduce EPS (or increase a loss per share). Two methods are used. The treasury stock method applies to options and warrants: assume they are exercised at the start of the year (or the issue date if later), and that the proceeds, including unrecognized compensation cost, are used to buy back shares at the average market price. Only the net incremental shares are added. Options with exercise prices above the average market price are antidilutive and excluded. The if-converted method applies to convertible securities: add back the after-tax interest (or preferred dividends) to the numerator and add the shares that would be issued on conversion to the denominator.
When there are several potential ordinary shares, they are ranked from most to least dilutive by their incremental EPS, the increase in the numerator divided by the increase in shares, and included in that order, stopping when the next one would be antidilutive. Since ASU 2020-06, the if-converted method is required for convertible instruments, and the treasury stock method can no longer be used for them. Because US GAAP records interest close to the cash coupon, the add-back is smaller than under IFRS, so the same bond is more likely to be dilutive.
# Northlake 2027 EPS (US GAAP figures; tax rate 25%)
profit = 4_500_000
pref_div = 250_000                       # cumulative preferred, equity-classified
num = profit - pref_div
# shares: 2,000,000 at 1 Jan; 300,000 issued 1 Jul; 100,000 repurchased 1 Oct; 10% stock dividend 1 Dec
weighted = 2_000_000 + 300_000 * 6/12 - 100_000 * 3/12
weighted *= 1.10                        # stock dividend applied retroactively
basic = num / weighted
print(f"Weighted shares {weighted:,.0f}; basic EPS {basic:.3f}")

# Options: 100,000 at $24 (stock-dividend adjusted to 110,000 at $21.82), average price $30
opts, ex = 110_000, 24 / 1.10
incremental_opts = opts - opts * ex / 30
# Convertible bond: single liability, interest about the 150,000 coupon, converts into 200,000 shares
add_back = 150_000 * (1 - 0.25)
conv_shares = 200_000
print(f"Options add {incremental_opts:,.0f} shares; bond adds {add_back:,.0f} / {conv_shares:,} = {add_back / conv_shares:.3f} per share")
step1 = num / (weighted + incremental_opts)
print(f"After options: {step1:.3f}")
step2 = (num + add_back) / (weighted + incremental_opts + conv_shares)
print(f"After bond: {step2:.3f} -> {'dilutive, include' if step2 < step1 else 'antidilutive, exclude'}")
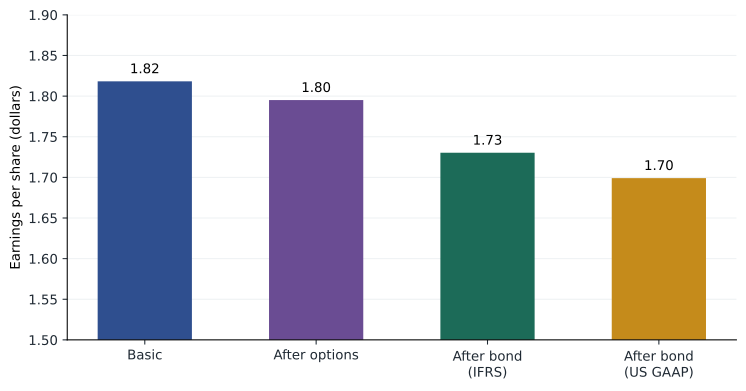
print(f"Diluted EPS {min(step1, step2):.3f}")Weighted shares 2,337,500; basic EPS 1.818 Options add 30,000 shares; bond adds 112,500 / 200,000 = 0.562 per share After options: 1.795 After bond: 1.699 -> dilutive, include Diluted EPS 1.699
Basic EPS is $1.82: $4,250,000 of earnings available to common stockholders over 2,337,500 weighted shares, after the stock dividend is applied retroactively. The options add 30,000 incremental shares under the treasury stock method. The convertible bond's incremental EPS is about 56 cents a share, well below the $1.80 EPS after options, so it is dilutive and included, giving diluted EPS of $1.70. An IFRS reporter would add back more interest because of the split liability, and report diluted EPS of $1.73.
| Item | Effect on numerator | Effect on denominator |
|---|---|---|
| Cumulative preferred dividends (equity) | Deduct the current year's dividend | None |
| Shares issued or repurchased | None | Weight by time outstanding |
| Stock dividends and splits | None | Apply retroactively to all periods |
| Options and warrants (treasury stock method) | None | Add net incremental shares if dilutive |
| Convertible debt (if-converted) | Add back after-tax interest | Add conversion shares if dilutive |
| Convertible preferred (if-converted) | Add back preferred dividends | Add conversion shares if dilutive |
Common mistakes
MistakeRecording no expense for options granted at the market price.
InsteadMeasure options at grant-date fair value and expense them over the vesting period.
MistakeRemeasuring equity-settled options to fair value each year.
InsteadEquity-settled awards keep their grant-date fair value; only the number expected to vest is trued up.
MistakeWeighting a stock dividend from the date it was issued.
InsteadApply stock dividends and splits retroactively to all periods.
MistakeIncluding out-of-the-money options in diluted EPS.
InsteadOptions with exercise prices above the average market price are antidilutive and excluded.
MistakeAdding potential shares in any order.
InsteadRank them by incremental EPS and include from most to least dilutive, stopping at the first antidilutive one.
Summary and key terms
- Equity-settled share-based payment is measured at grant-date fair value and recognized over the vesting period.
- Service and non-market performance conditions affect the number expected to vest; market conditions are in the fair value.
- US GAAP allows straight-line recognition of graded awards and accounting for forfeitures as they occur.
- Cash-settled awards are liabilities remeasured to fair value until settlement.
- Basic EPS divides earnings attributable to common shareholders by the weighted average shares outstanding.
- Diluted EPS adds dilutive options (treasury stock method) and convertibles (if-converted method).
- Potential shares are included in order of dilution and only if they reduce EPS.
- Excess tax benefit
- A tax deduction exceeding recognized compensation cost, recognized in income tax expense.
- Grant date
- The date the entity and employee agree to the terms of a share-based award.
- Vesting period
- The period over which employees must provide service to earn an award.
- Cliff vesting
- Vesting of an entire award at a single date.
- Graded vesting
- Vesting of an award in installments over several dates.
- Market condition
- A vesting condition linked to the share price, reflected in grant-date fair value.
- Basic EPS
- Earnings attributable to ordinary shareholders divided by weighted average ordinary shares.
- Diluted EPS
- EPS adjusted for all dilutive potential ordinary shares.
- Treasury stock method
- Assumes options are exercised and the proceeds repurchase shares at the average market price.
- If-converted method
- Assumes convertible securities are converted, adding back their interest or dividends.
- Antidilutive
- Having the effect of increasing EPS or reducing a loss per share; such securities are excluded.
Practice problems
Work each problem on paper first, then reveal the answer to check.
50,000 options with a fair value of $4, vesting after 3 years, 90 percent expected to vest. Annual expense?
Show answer
50,000 × 90% × 4 ÷ 3 = $60,000.
The expected vesting rate falls to 80 percent at the end of year 2. Year 2 expense?
Show answer
Cumulative 50,000 × 80% × 4 × 2/3 = $106,667; year 2 = $46,667.
Rerun the option program with volatility of 40 percent. What happens to fair value?
Show answer
It rises to about $8.83, increasing the cost of the award.
An award vests one-third a year over 3 years; total cost $90,000. Year 1 expense under a straight-line policy?
Show answer
$30,000.
Profit $1 million; cumulative preferred dividend $100,000 (not declared). Numerator for basic EPS?
Show answer
$900,000.
500,000 shares at 1 January; 120,000 issued 1 May. Weighted average?
Show answer
500,000 + 120,000 × 8/12 = 580,000.
A 2-for-1 split occurs after year end but before issue. Effect on EPS?
Show answer
Restate the weighted shares for all periods, halving EPS.
20,000 options at $40; average price $50. Incremental shares?
Show answer
20,000 − 16,000 = 4,000.
Same options with an average price of $35?
Show answer
None; they are antidilutive.
A convertible bond adds $90,000 after tax and 100,000 shares; EPS before it is $0.80. Include?
Show answer
No; its incremental EPS of $0.90 exceeds $0.80, so it is antidilutive and excluded.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.