
ACCT-212 · Lesson 4 of 12 · 28 min
Long-term debt II: notes, extinguishment, modifications and presentation
Lesson 3 followed a bond from issue to maturity. Real debt rarely behaves so neatly. Companies borrow from banks on installment notes, repay bonds early when interest rates fall, renegotiate loans when they run into trouble, breach covenants, and issue debt that converts into shares. This lesson covers those events: installment and mortgage notes, early extinguishment, modifications and troubled debt restructurings, the fair value option, convertible debt and the classification questions raised by covenants. The framework differences here are larger than for plain bonds, so the IFRS and US GAAP treatments are set side by side.
Installment notes and mortgages
Many long-term notes are repaid in equal installments that combine interest and principal, like a home mortgage. The payment is the annuity that amortizes the principal at the stated rate. Each payment is split: interest is the opening balance times the rate, and the rest reduces principal. Early payments are mostly interest; later payments are mostly principal. Only the principal due within twelve months is a current liability.
Worked problem
An installment note
Northlake borrows $600,000 from its bank on 1 January 2027 to buy test equipment, repayable in four equal annual payments at 6 percent, starting 31 December 2027. What are the payment and the split of the first payment?
Show solution
- Payment: 600,000 × 0.06 ÷ [1 − 1.06⁻⁴] = $173,155.
- Year 1 interest: 600,000 × 6% = $36,000. Principal repaid: 173,155 − 36,000 = $137,155.
- Balance after the first payment: $462,845.
- At 31 December 2027, the principal due in 2028 (173,155 − 462,845 × 6% = $145,384) is current; the remaining $317,461 is non-current.
Answer: Annual payment $173,155; the current portion at the end of year 1 is $145,384.
Mortgages are installment notes secured by real property; the lender can take the property if the borrower defaults. Their accounting is the same, with additional disclosure of the assets pledged as security. Canadian residential mortgages compound interest semi-annually under the Interest Act, so the monthly rate is derived from the semi-annual rate (FIN-201 lesson 4); commercial loans usually compound monthly.
Extinguishing debt before maturity
A company may repay debt early by exercising a call option in the indenture, buying its bonds in the open market or refinancing through a new issue. When debt is extinguished, the difference between the reacquisition price (including any call premium and transaction costs) and the carrying amount of the debt, including unamortized discount, premium and issue costs, is recognized as a gain or loss in profit or loss. Because the carrying amount and the price rarely match, extinguishments often produce gains or losses that analysts treat as non-recurring.
Worked problem
Calling the bonds
On 31 December 2029, after six semi-annual payments, interest rates have fallen and Northlake calls its $10 million bonds from lesson 3 at 102. The carrying amount after the sixth payment is $9,811,901. What is recognized?
Show solution
- Reacquisition price: 10,000,000 × 1.02 = $10,200,000.
- Carrying amount: $9,811,901 (face value less the unamortized discount of $188,099).
- Loss on extinguishment: 10,200,000 − 9,811,901 = $388,099, in profit or loss.
- Entry: debit bonds payable $9,811,901 and loss on extinguishment $388,099; credit cash $10,200,000.
Answer: Loss of $388,099: the call premium plus the unamortized discount.
Under ASC 405-20 a liability is derecognized when the debtor pays the creditor or is legally released. ASC 470-50 requires the gain or loss to be recognized in income; since ASU 2015-01 eliminated extraordinary items, it is presented within income from continuing operations, often as a separate line.
Modifications and exchanges of debt
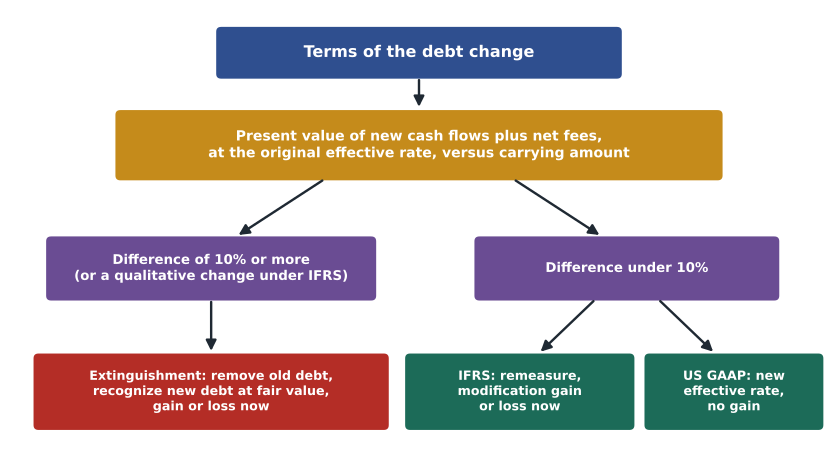
Instead of repaying debt, a borrower and lender may change its terms: a lower interest rate, a longer maturity, a reduced principal or added fees. The question is whether the change is so substantial that the old debt should be treated as extinguished and new debt recognized, or whether the old debt continues with modified terms. Both frameworks use a quantitative '10 percent test': compare the present value of the cash flows under the new terms, including fees paid net of fees received, discounted at the original effective interest rate, with the present value of the remaining cash flows of the original debt (its carrying amount). If the difference is at least 10 percent, the modification is substantial and treated as an extinguishment.
If the modification is not substantial, ASC 470-50 does not recognize a gain or loss. Instead, the existing carrying amount (adjusted for fees paid to the lender) continues, and a new effective interest rate is computed that equates the revised cash flows with that carrying amount, so the effect is spread over the remaining term. This is a well-known difference from IFRS 9, which recognizes the effect at once. Third-party costs are expensed in a modification and capitalized in an extinguishment, the reverse of fees paid to the lender.
# The 10% test and accounting for a modified bank loan
original_eir = 0.06
carrying = 5_000_000                    # 6% loan, 3 years left, interest annual
def pv(flows, r):
    return sum(cf / (1 + r) ** t for t, cf in enumerate(flows, start=1))

# New terms: rate cut to 4%, maturity extended to 5 years, $100,000 fee paid to the lender
new_flows = [200_000] * 4 + [5_200_000]
fee_paid = 100_000
pv_new = pv(new_flows, original_eir) + fee_paid
change = (carrying - pv_new) / carrying
print(f"PV of new flows plus fee at 6%: {pv_new:,.0f}")
print(f"Difference from carrying amount: {change:.1%} -> {'extinguishment' if abs(change) >= 0.10 else 'modification'}")

# IFRS 9: remeasure at the original EIR, recognize a gain; fee adjusts the carrying amount
remeasured = pv(new_flows, original_eir)
print(f"IFRS 9 gain on modification: {carrying - remeasured:,.0f}; new carrying {remeasured - fee_paid:,.0f}")

# US GAAP (ASC 470-50): no gain; solve a new effective rate on carrying less the fee
target = carrying - fee_paid
lo, hi = 0.0, 0.2
for _ in range(100):
    mid = (lo + hi) / 2
    lo, hi = (mid, hi) if pv(new_flows, mid) > target else (lo, mid)
print(f"ASC 470-50: no gain; carrying {target:,.0f}; new effective rate {mid:.3%}")PV of new flows plus fee at 6%: 4,678,764 Difference from carrying amount: 6.4% -> modification IFRS 9 gain on modification: 421,236; new carrying 4,478,764 ASC 470-50: no gain; carrying 4,900,000; new effective rate 4.455%
The rate cut and extension reduce the present value of the loan by 6.4 percent, under the 10 percent threshold, so the debt is modified rather than extinguished. Under IFRS 9 Northlake recognizes a modification gain of $421,236 immediately and continues to recognize interest at the original 6 percent on the lower carrying amount. Under US GAAP no gain is recognized; the carrying amount, reduced by the fee, becomes $4.9 million, and interest is recognized at a new effective rate of about 4.46 percent for the next five years. Over the life of the loan the total effect is the same; only the timing differs.
For debtors, ASC 470-60 still contains a separate model for troubled debt restructurings: when the creditor grants a concession because the debtor is in difficulty, the debtor recognizes a gain only if the total future undiscounted cash flows under the new terms are less than the carrying amount. Otherwise, a new effective rate is computed prospectively. (ASU 2022-02 eliminated the TDR model for creditors, not debtors.) Transfers of assets or equity in full settlement produce a gain measured against the fair value of what is given up.
The fair value option
ASC 825-10 allows an entity to elect the fair value option for eligible financial liabilities on an instrument-by-instrument basis at initial recognition. Changes in fair value are recognized in net income, except the portion attributable to instrument-specific credit risk, which ASU 2016-01 requires to be presented in other comprehensive income. Debt issuance costs on liabilities at fair value are expensed as incurred.
Convertible debt
Since ASU 2020-06, effective for public business entities in 2022 and others in 2024, most convertible debt is accounted for as a single liability at amortized cost under ASC 470-20, with no separation of the conversion feature, unless the feature must be bifurcated as a derivative under ASC 815 or the debt was issued at a substantial premium. Interest expense is therefore close to the cash coupon. IFRS reporters split the same instrument into a liability and an equity component, so they report higher interest expense on convertible debt than US GAAP reporters.
Worked problem
Splitting a convertible bond
Northlake issues $5 million of five-year convertible bonds at par with a 3 percent annual coupon. Similar bonds without a conversion feature would yield 6 percent. How is the issue recorded?
Show solution
- Under ASU 2020-06, the bonds are recorded as a single liability of $5,000,000 (less any issuance costs).
- Interest expense is about $150,000 a year, the cash coupon.
- Under IFRS the same bonds would be split: liability $4,368,145 and equity $631,855, with interest expense of $262,089 in year 1.
- Diluted earnings per share uses the if-converted method in both frameworks (lesson 11).
Answer: Single liability of $5,000,000 under US GAAP; IFRS would split it.
Covenants, breaches and classification
Under ASC 470-10, debt that is callable because of a covenant violation at the balance sheet date is classified as current unless the creditor has waived or lost the right to demand repayment for more than one year from the balance sheet date, or the debt agreement contains a grace period within which the violation is probable of being cured. A waiver obtained after the balance sheet date but before the statements are issued can support non-current classification, unlike under IFRS. Subjective acceleration clauses require disclosure, and classification as current if acceleration is probable.
| Event | US GAAP | IFRS (for comparison) |
|---|---|---|
| Refinanced after year end, before issue | Non-current | Current |
| Covenant breach at year end, waiver after year end | Non-current if waived for more than a year | Current |
| Non-substantial modification | New effective rate, no gain or loss | Gain or loss now |
| Convertible bond (no derivative) | Single liability | Split liability and equity |
| Fair value option: own credit changes | Other comprehensive income | Other comprehensive income |
Because the classification of debt can swing a current ratio dramatically, readers should study the notes on covenants and waivers, especially for companies near their limits. A reclassification of a large loan to current is often an early warning of financial distress, and auditors consider it carefully when assessing whether the going-concern basis is appropriate.
Common mistakes
MistakeRecording the call premium on early repayment as interest expense spread over the remaining term.
InsteadRecognize the difference between the price and the carrying amount immediately as a gain or loss on extinguishment.
MistakeTreating every change in loan terms as new debt.
InsteadApply the 10 percent test (and, under IFRS, qualitative factors) to decide between extinguishment and modification.
MistakeRecognizing a gain immediately on a non-substantial modification.
InsteadASC 470-50 recognizes no gain; it computes a new effective rate prospectively.
MistakeSplitting a plain convertible bond into liability and equity.
InsteadSince ASU 2020-06, most convertibles are a single liability.
MistakeClassifying the full installment note as non-current.
InsteadThe principal due within twelve months is current.
Summary and key terms
- Installment payments combine interest on the opening balance and principal; only next year's principal is current.
- Early extinguishment produces a gain or loss equal to the difference between the price paid and the carrying amount.
- The 10 percent test compares the present value of modified cash flows, at the original effective rate, with the carrying amount.
- ASC 470-50 recognizes no gain on a non-substantial modification and adjusts the effective rate.
- Under the fair value option, changes from the entity's own credit risk go to other comprehensive income.
- Most convertible bonds are a single liability under ASU 2020-06.
- A covenant breach waived before the statements are issued can leave debt non-current.
- Installment note
- A loan repaid in equal payments combining interest and principal.
- Extinguishment
- The discharge, cancellation or expiry of a liability, removing it from the balance sheet.
- Call premium
- The amount above face value an issuer pays to redeem bonds early.
- Modification
- A change in the terms of debt that is not substantial enough to be an extinguishment.
- Ten percent test
- Comparison of the present value of modified cash flows with the carrying amount to decide whether a modification is substantial.
- Troubled debt restructuring
- A modification in which a lender grants concessions because the borrower is in financial difficulty.
- Fair value option
- An election to measure a financial liability at fair value with changes in profit or loss.
- Convertible bond
- A bond the holder may exchange for a fixed number of the issuer's shares.
- Covenant
- A condition in a loan agreement that the borrower must meet.
- Grace period
- A period after a breach during which the lender cannot demand repayment.
Practice problems
Work each problem on paper first, then reveal the answer to check.
$200,000 note, 3 annual payments at 5 percent. Payment?
Show answer
$73,442.
Carrying amount $4.9 million; called at $5.1 million. Gain or loss?
Show answer
Loss of $200,000.
Bonds with a carrying amount of $10.3 million are repurchased at $10.1 million. Result?
Show answer
Gain of $200,000.
Carrying amount $2 million; PV of new flows plus fees at the original rate $1.75 million. Substantial?
Show answer
Yes; a 12.5 percent difference.
Rerun the modification program with a $20,000 fee and the rate cut only to 5 percent for three years. Result?
Show answer
The present value changes by about 2.3 percent: a modification, not an extinguishment.
Non-substantial modification reduces the PV at the original rate by $300,000. US GAAP entry?
Show answer
No gain; compute a new effective rate on the existing carrying amount.
How is a plain $1 million convertible recorded under ASU 2020-06?
Show answer
As a single $1 million liability.
Why do covenants matter for the current ratio?
Show answer
A breach can make long-term debt current, sharply reducing the ratio.
Under the fair value option, the entity's credit rating falls and its debt's fair value drops $500,000. Where does the gain go?
Show answer
To other comprehensive income, not profit or loss.
Why are early payments on an installment note mostly interest?
Show answer
Interest is computed on the opening balance, which is highest at the start.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.