
ACCT-212 · Lesson 5 of 12 · 27 min
Leases I: lessee accounting under ASC 842
Northlake needs a larger warehouse for finished stations. Rather than buy a building, it signs a five-year lease. For decades, most such leases never appeared on the lessee's balance sheet: if the lease did not transfer substantially all the risks and rewards of ownership, the lessee simply expensed the rent. Analysts knew this hid enormous obligations; airlines and retailers carried billions of dollars of lease commitments in the notes only. In 2016 both the IASB and the FASB issued new standards, IFRS 16 and ASC 842, that bring almost all leases onto the lessee's balance sheet. The two boards agreed on that principle but not on how the expense should be presented, so lessee accounting is now one of the clearest examples of a remaining IFRS–US GAAP difference.
What is a lease?
A lease is a contract, or part of a contract, that conveys the right to control the use of an identified asset for a period of time in exchange for consideration. Two tests apply. First, there must be an identified asset, specified explicitly or implicitly, and the supplier must not have a substantive right to substitute a different asset throughout the period of use. Second, the customer must have the right to obtain substantially all the economic benefits from use of the asset and the right to direct how and for what purpose it is used. A contract to store goods in any available space in a supplier's warehouse is a service, not a lease; a contract for exclusive use of a specified building is a lease.
Many contracts contain embedded leases. An agreement for a supplier to provide data processing using dedicated servers in the customer's premises, or a transportation contract that uses specified railcars at the customer's direction, may contain a lease even though it is not called one. Contracts often mix lease components, such as the use of equipment, with non-lease components, such as maintenance. The consideration is allocated between them on a relative standalone price basis, although lessees may elect, by class of asset, to treat lease and non-lease components as a single lease component.
Initial measurement for the lessee
At the commencement date, when the lessor makes the asset available, the lessee recognizes a lease liability and a right-of-use asset. The lease liability is the present value of the lease payments not yet paid. Lease payments include fixed payments (less lease incentives receivable), variable payments that depend on an index or rate (measured using the index or rate at commencement), amounts expected under residual value guarantees, the exercise price of a purchase option the lessee is reasonably certain to exercise, and termination penalties if the lease term reflects termination. Variable payments linked to usage or sales, such as a percentage of store revenue, are excluded and expensed as incurred.
The discount rate is the rate implicit in the lease if readily determinable; otherwise the lessee's incremental borrowing rate. Lessees that are not public business entities may elect, by class of underlying asset, to use a risk-free rate for a comparable term instead, which produces a larger liability. The right-of-use asset is measured at the lease liability plus payments made at or before commencement, less incentives received, plus initial direct costs. Asset retirement obligations for leased assets are accounted for separately under ASC 410.
The lease term is the non-cancellable period plus periods covered by options to extend that the lessee is reasonably certain to exercise and periods covered by options to terminate that it is reasonably certain not to exercise. Judging 'reasonably certain' requires looking at economic incentives: significant leasehold improvements, relocation costs, below-market renewal rents and the importance of the asset to the lessee's operations.
Worked problem
Measuring the warehouse lease
On 1 January 2027 Northlake leases a warehouse for five years at $200,000 a year, paid at the end of each year. There are no renewal options, incentives or initial direct costs. The rate implicit in the lease is not known; Northlake's incremental borrowing rate is 6 percent. What is recognized at commencement?
Show solution
- Lease payments: five annual payments of $200,000 in arrears.
- Lease liability: 200,000 × [1 − 1.06⁻⁵] ÷ 0.06 = $842,473.
- Right-of-use asset: equal to the liability, $842,473, because there are no prepayments, incentives or direct costs.
- Entry: debit right-of-use asset $842,473; credit lease liability $842,473.
Answer: Right-of-use asset and lease liability of $842,473 each.
Subsequent measurement under ASC 842: finance and operating leases
ASC 842 keeps a dual model for lessees. A lease is a finance lease if any one of five criteria is met at commencement: ownership transfers by the end of the term; the lessee holds a purchase option it is reasonably certain to exercise; the lease term is for the major part of the asset's remaining economic life; the present value of lease payments and any residual value guarantee equals or exceeds substantially all of the asset's fair value; or the asset is so specialized that it has no alternative use to the lessor at the end of the term. Many companies use the bright lines from the old standard, 75 percent for 'major part' and 90 percent for 'substantially all', as policy. Otherwise, the lease is an operating lease. A finance lease is accounted for like the IFRS single model: amortization of the right-of-use asset plus interest on the liability, front-loaded. An operating lease produces a single straight-line lease cost each year in operating expenses. The liability is still measured at the present value of remaining payments, but the right-of-use asset is measured as a balancing figure so that total expense stays straight-line, and all operating lease payments are operating cash outflows.
# Warehouse lease: IFRS 16 (single model) vs ASC 842 operating lease, 5 years at 6%
payment, rate, years = 200_000, 0.06, 5
liability = sum(payment / (1 + rate) ** t for t in range(1, years + 1))
rou0 = liability
dep = rou0 / years
print(f"Initial liability and ROU asset: {liability:,.0f}")
print(f"{'Year':>4} {'Interest':>9} {'Dep':>9} {'IFRS 16 total':>14} {'ASC 842 op cost':>16} {'Liability end':>14} {'Op-lease ROU end':>17}")
ifrs_total = us_total = 0
for y in range(1, years + 1):
    interest = liability * rate
    liability = liability + interest - payment
    ifrs = interest + dep
    us = payment                          # straight-line single lease cost
    rou_us = liability                    # with no prepaid/accrued rent, ROU equals the liability
    ifrs_total += ifrs; us_total += us
    print(f"{y:>4} {interest:>9,.0f} {dep:>9,.0f} {ifrs:>14,.0f} {us:>16,.0f} {liability:>14,.0f} {rou_us:>17,.0f}")
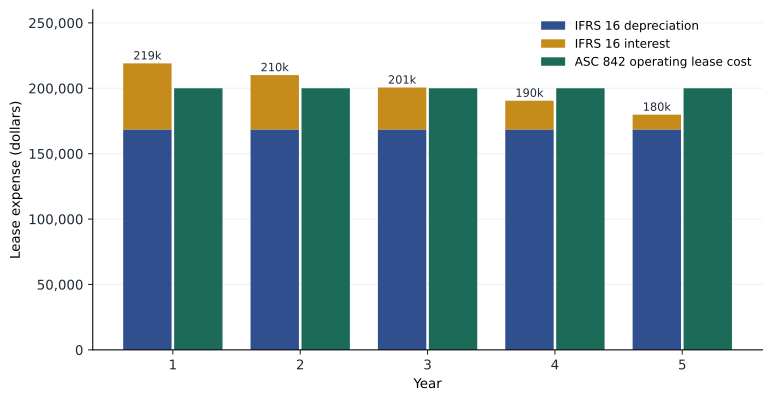
print(f"Totals: IFRS 16 {ifrs_total:,.0f}; ASC 842 operating {us_total:,.0f}")Initial liability and ROU asset: 842,473 Year Interest Dep IFRS 16 total ASC 842 op cost Liability end Op-lease ROU end 1 50,548 168,495 219,043 200,000 693,021 693,021 2 41,581 168,495 210,076 200,000 534,602 534,602 3 32,076 168,495 200,571 200,000 366,679 366,679 4 22,001 168,495 190,495 200,000 188,679 188,679 5 11,321 168,495 179,815 200,000 -0 -0 Totals: IFRS 16 1,000,000; ASC 842 operating 1,000,000
The program shows the difference. Under IFRS 16, lease expense in year 1 is $219,043 (interest of $50,548 plus depreciation of $168,495), falling to $179,815 in year 5. Under an ASC 842 operating lease, the expense is $200,000 every year. Both total $1,000,000 over the lease, and the liability is identical at every year end; only the pattern and presentation of expense differ. Because the operating-lease right-of-use asset is a plug, it equals the liability in each year in this simple case, while the IFRS right-of-use asset is depreciated faster than the liability is repaid in the early years.
Worked problem
Classifying an equipment lease
Northlake leases a calibration rig with an economic life of five years for four years, paying $60,000 a year in arrears. The rig's fair value is $230,000, and Northlake's incremental borrowing rate is 6 percent. There is no purchase option or ownership transfer. How is the lease classified?
Show solution
- Ownership transfer or purchase option: no.
- Major part of economic life: four of five years is 80 percent, meeting the commonly used 75 percent policy.
- Present value of payments: 60,000 × [1 − 1.06⁻⁴] ÷ 0.06 = $207,906, about 90 percent of the $230,000 fair value, meeting the 90 percent policy.
- Either criterion makes it a finance lease: amortize the right-of-use asset and recognize interest separately.
Answer: A finance lease under ASC 842.
Practical expedients and exemptions
ASC 842 allows lessees to elect, by class of underlying asset, not to recognize short-term leases, those with a term of twelve months or less and no purchase option the lessee is reasonably certain to exercise; payments are expensed straight-line. There is no low-value exemption like IFRS 16's, but companies may apply a capitalization threshold for immaterial leases as an accounting policy, consistent with materiality. Private companies may also elect to use a risk-free discount rate and, under ASU 2023-01, to use the written terms and conditions of arrangements between entities under common control.
How IFRS and ASPE compare
Outside the United States, IFRS 16 applies a single model: every recognized lease is accounted for like a US finance lease, with depreciation and interest presented separately. A Canadian or European competitor with the same warehouse lease would therefore report higher operating profit and EBITDA than a US company reporting an operating lease, and classify the principal portion of payments as a financing cash flow. Canadian private enterprises using ASPE still apply the older capital/operating model, keeping operating leases off the balance sheet entirely. Analysts comparing companies across frameworks need to adjust for these differences.
| Feature | ASC 842 | IFRS 16 (for comparison) |
|---|---|---|
| Lessee models | Finance or operating | Single model |
| Operating leases on balance sheet? | Yes: liability and right-of-use asset | Yes (no operating category) |
| Expense pattern | Finance: front-loaded; operating: straight-line single cost | Front-loaded: depreciation plus interest |
| Short-term exemption | Yes, twelve months or less | Yes, twelve months or less |
| Low-value exemption | No (materiality policy only) | Yes, about US$5,000 new |
| Operating lease payments in cash flow statement | Operating | Principal in financing |
Effects on financial statement analysis
Bringing leases onto the balance sheet increased reported debt and assets for lease-heavy companies, raising debt-to-equity and lowering return on assets. Under IFRS 16 it also raised EBITDA, because rent was replaced by depreciation and interest, both excluded from EBITDA. Loan covenants written in terms of EBITDA or debt often had to be renegotiated or defined on a 'frozen GAAP' basis. Analysts comparing a retailer reporting under IFRS with one reporting operating leases under US GAAP must adjust: the US company's EBITDA includes lease cost, while the IFRS company's does not. Lease disclosures, including maturity analyses of lease liabilities, weighted-average remaining lease terms and discount rates, help with these adjustments.
Common mistakes
MistakeTreating a contract as a service because it is not called a lease.
InsteadApply the identified-asset and right-to-control tests; embedded leases are common.
MistakeRecording no liability for an operating lease under ASC 842.
InsteadOperating leases are on the balance sheet; only the expense pattern is straight-line.
MistakeIncluding sales-based variable rent in the lease liability.
InsteadOnly variable payments based on an index or rate are included; usage- and sales-based payments are expensed as incurred.
MistakeIgnoring a renewal option the lessee is reasonably certain to exercise.
InsteadInclude option periods in the lease term when exercise is reasonably certain.
MistakeAssuming IFRS and US GAAP lease expense always match.
InsteadThey match only for US finance leases; operating leases produce a different pattern and presentation.
Summary and key terms
- A lease conveys the right to control the use of an identified asset for a period of time.
- The lease liability is the present value of fixed and index-based payments, guarantees and reasonably certain options.
- The right-of-use asset starts at the liability plus prepayments, initial direct costs and restoration costs, less incentives.
- ASC 842 has finance leases (front-loaded) and operating leases (straight-line single cost).
- Short-term leases may be expensed; there is no low-value exemption.
- IFRS 16 reporters show higher EBITDA than US operating-lease reporters for the same lease.
- Lease accounting changes debt, EBITDA and cash flow classification, so analysts adjust when comparing.
- Finance lease
- A lease meeting any of the five ASC 842 classification criteria, accounted for with separate amortization and interest.
- Operating lease
- Under ASC 842, a lease that is not a finance lease, producing a straight-line single lease cost.
- Lease
- A contract conveying the right to control the use of an identified asset for a period in exchange for consideration.
- Right-of-use asset
- The lessee's asset representing its right to use the underlying asset over the lease term.
- Lease liability
- The present value of lease payments not yet paid.
- Incremental borrowing rate
- The rate the lessee would pay to borrow, over a similar term and security, to obtain a similar asset.
- Lease term
- The non-cancellable period plus option periods the lessee is reasonably certain to use.
- Commencement date
- The date the lessor makes the underlying asset available to the lessee.
- Embedded lease
- A lease contained within a broader service or supply contract.
- Short-term lease
- A lease of twelve months or less with no purchase option.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A contract allows a supplier to substitute any of its trucks at any time at little cost. Lease?
Show answer
No; the substitution right is substantive, so there is no identified asset.
Payments of $100,000 a year for 3 years in arrears at 5 percent. Lease liability?
Show answer
$272,325.
Liability $272,325 and a $5,000 prepayment at commencement. Right-of-use asset?
Show answer
$277,325.
For an operating lease of $100,000 a year, what is the annual ASC 842 lease cost?
Show answer
$100,000, straight-line.
Rerun the lease program at 8 percent. What happens to year 1 IFRS 16 expense?
Show answer
Interest rises and the liability falls; year 1 expense rises to about $223,600 while the total stays $1,000,000.
Rent of 5 percent of store sales. Included in the liability?
Show answer
No; it is expensed as incurred.
A ten-month equipment lease with no purchase option. Exemption?
Show answer
Short-term exemption may be elected.
Why does IFRS 16 increase EBITDA?
Show answer
Rent is replaced by depreciation and interest, which EBITDA excludes.
A lessee has a five-year renewal option at half the market rent and has built costly improvements. Lease term?
Show answer
Include the renewal period; exercise is reasonably certain.
A 6-year lease of an asset with an 8-year life. Finance lease under a 75 percent policy?
Show answer
Yes; 75 percent of the economic life.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.