
FIN-201 · Lesson 8 of 12 · 29 min
Estimating project cash flows and taxes
A capital budgeting decision is only as good as the cash flow forecast behind it. The decision rules of lesson 7 tell us to discount a project's cash flows, but which cash flows? This lesson sets out the principles for identifying the cash flows that belong in the analysis, shows how to build a project's free cash flows year by year, and explains how taxes, especially the tax deductions for capital spending, change the result. The tax rules differ sharply between Canada and the United States, so this lesson uses each country's system on its own site. Nothing here is tax advice; rules change often, and real projects need current rules and professional advice.
Incremental cash flows
The cash flows that matter are incremental: the difference between the firm's cash flows if it takes the project and its cash flows if it does not. Every item in the analysis should pass that test. Several common traps follow from it. Sunk costs, money already spent and unrecoverable whatever the decision, are irrelevant: a market study paid for last year should not count against the project. Opportunity costs are relevant: if the project uses land the firm already owns, the cash the firm could get by selling or renting that land is a cost of the project, even though no cheque is written. Side effects matter: a new product that takes sales from an existing one (cannibalization) should be charged with the lost profit, while one that boosts sales of other products should be credited with the gain. Allocated overhead counts only to the extent that the project actually increases it.
Financing costs are excluded from project cash flows. Interest, debt repayments and dividends are payments to investors, and the required return of those investors is captured in the discount rate, the weighted average cost of capital developed in lesson 11. Subtracting interest from the cash flows and also discounting at a rate that includes the cost of debt would count it twice. Finally, be consistent about inflation, as lesson 3 explained: if revenues and costs are forecast in nominal dollars that include expected price increases, discount at a nominal rate.
| Item | Include? | Why |
|---|---|---|
| Market research already paid for | No | Sunk: it does not change with the decision |
| Rent forgone on a building the firm owns | Yes | Opportunity cost |
| Lost profit on an existing product | Yes | Cannibalization is a side effect |
| Share of head office costs | Only if they rise | Allocated costs that do not change are not incremental |
| Interest on a loan to buy the equipment | No | Financing costs are in the discount rate |
| Extra inventory and receivables | Yes | Investment in working capital uses cash |
| Tax savings from depreciation or CCA | Yes | Taxes are real cash flows |
The parts of a project's cash flows
A project's free cash flow in each year has three parts, matching the free cash flow definition of lesson 2. The first is after-tax operating cash flow: incremental revenue minus incremental cash operating costs, minus the taxes on that difference. The second is the tax saving from deducting the cost of the capital assets over time, called the depreciation tax shield, or in Canada the capital cost allowance tax shield. The third is investment: the capital spending at the start (and any later), the investment in net working capital, and their recovery at the end through the after-tax salvage value of the assets and the release of the working capital.
Here \( D_t \) is the tax deduction for the capital asset in year \( t \) and \( T \) the marginal tax rate. The term \( T \cdot D_t \) shows that depreciation itself is not a cash flow, but its effect on taxes is: each dollar deducted saves \( T \) dollars of tax. Working capital is usually invested at the start or as sales grow and recovered at the end of the project, when inventory is sold off and receivables are collected; ignoring it overstates the NPV of almost any project, because it moves cash from early years to late years.
Tax deductions for capital spending
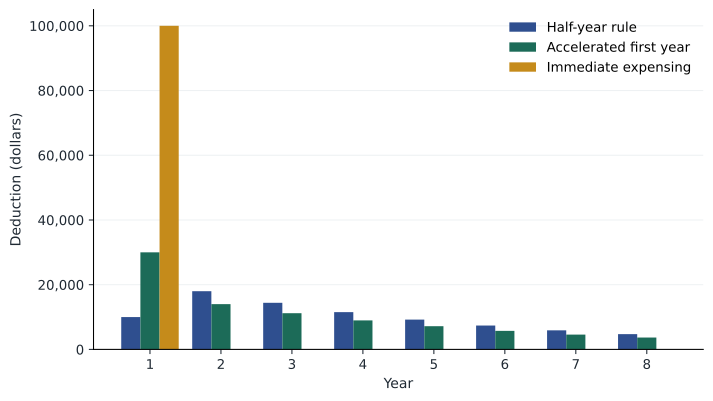
In Canada, the tax deduction for depreciable property is the capital cost allowance (CCA). Assets are grouped into classes, each with a prescribed rate, and most classes use the declining balance method: each year the deduction is the class rate times the remaining undepreciated capital cost (UCC). For example, Class 8 (most machinery and equipment not in another class) has a rate of 20 %, Class 10 (vehicles) 30 %, Class 50 (general computer equipment) 55 %, and Class 1 (most buildings) 4 %. Normally the half-year rule allows only half the usual deduction in the year of acquisition. Budget 2024 and the Fall Economic Statement 2024 proposed, and Budget 2025 extended, a set of measures that Parliament enacted in March 2026: an accelerated first-year allowance for most property acquired from 2025 and available for use before 2030 (the deduction in the first year is about one and a half times the normal full-year rate, with the half-year rule suspended), phasing down for 2030 to 2033; and immediate 100 % expensing, the productivity super-deduction, for manufacturing and processing equipment (Class 53), clean energy equipment and zero-emission vehicles available for use before 2030, plus productivity-enhancing assets such as computer equipment and patents. Because the deduction continues on the declining balance indefinitely, Canadian analysts value the whole stream with a closed-form formula rather than year by year.
In the formula, \( C \) is the capital cost, \( d \) the CCA rate, \( T \) the tax rate and \( r \) the discount rate. With the accelerated first-year allowance, the factor \( (1 + 0.5r) \) becomes \( (1 + 1.5r) \); with immediate expensing, the shield is simply \( CT/(1+r) \) if the deduction is claimed at the end of the first year. When an asset is sold, its proceeds (up to the original cost) are deducted from the UCC of the class, so the firm loses the future CCA on that amount. As long as the class remains open, the present value of the lost shield is \( S\,d\,T/(d+r) \) discounted from the date of sale, where \( S \) is the salvage value. If the class is closed, a terminal loss or recapture arises instead.
Worked problem
Comparing CCA treatments
A firm buys equipment costing $100,000. The tax rate is 26.5 % and the discount rate 10 %. Find the present value of the tax shield under Class 8 (20 %) with the half-year rule, with the accelerated first-year allowance, and with immediate expensing.
Show solution
- Half-year rule: 100,000 × 0.20 × 0.265 ÷ 0.30 × 1.05 ÷ 1.10 = 16,864.
- Accelerated first year: 100,000 × 0.20 × 0.265 ÷ 0.30 × 1.15 ÷ 1.10 = 18,470.
- Immediate expensing: 100,000 × 0.265 ÷ 1.10 = 24,091.
Answer: Faster deductions are worth more because tax is saved sooner. Immediate expensing adds about $7,200 of value per $100,000 compared with the half-year rule, which is why governments use it to encourage investment.
A complete project analysis
Bringing the pieces together, consider a project that requires equipment costing $800,000, has a five-year life, and will be sold for $150,000 at the end. It needs $60,000 of extra working capital at the start, recovered at the end. It is expected to increase revenue by $500,000 a year and cash operating costs by $230,000 a year. The discount rate is 10 %. The tax treatment of the equipment follows each country's rules.
Worked problem
Project NPV with CCA
Using a 26.5 % tax rate and Class 8 CCA with the accelerated first-year allowance, find the NPV of the project described above.
Show solution
- After-tax operating cash flow = (500,000 − 230,000) × 0.735 = 198,450 a year; PV over 5 years = 752,282.
- PV of CCA tax shield = 800,000 × 0.20 × 0.265 ÷ 0.30 × 1.15 ÷ 1.10 = 147,758.
- PV of lost shield on salvage = 150,000 × 0.20 × 0.265 ÷ 0.30 ÷ 1.10⁵ = 16,454.
- PV of salvage = 150,000 ÷ 1.10⁵ = 93,138.
- Working capital: −60,000 + 60,000 ÷ 1.10⁵ = −22,745.
- NPV = −800,000 + 752,282 + 147,758 − 16,454 + 93,138 − 22,745 = 153,978.
Answer: The project adds about $154,000 of value. Note how much of that comes from the CCA tax shield: without it, the NPV would be negative.
# Project NPV with capital cost allowance (Class 8, 20 %, accelerated first year)
cost, salvage, nwc, years = 800_000, 150_000, 60_000, 5
revenue, op_costs, tax, r, d = 500_000, 230_000, 0.265, 0.10, 0.20
after_tax_operating = (revenue - op_costs) * (1 - tax)
pv_ops = sum(after_tax_operating / (1 + r) ** t for t in range(1, years + 1))
# CCA tax shield: first-year deduction of 1.5 x d, then d on the declining balance
pv_shield = cost * d * tax / (d + r) * (1 + 1.5 * r) / (1 + r)
pv_lost_shield = salvage * d * tax / (d + r) / (1 + r) ** years
pv_salvage = salvage / (1 + r) ** years
pv_nwc = -nwc + nwc / (1 + r) ** years
npv = -cost + pv_ops + pv_shield - pv_lost_shield + pv_salvage + pv_nwc
for label, v in [("after-tax operating", pv_ops), ("CCA tax shield", pv_shield), ("lost shield on salvage", -pv_lost_shield),
                 ("salvage", pv_salvage), ("working capital", pv_nwc), ("equipment", -cost)]:
    print(f"{label:24s} {v:12,.0f}")
print(f"{'NPV':24s} {npv:12,.0f}")
# With immediate expensing (for example Class 53 manufacturing equipment under the 2025 measures)
pv_shield_100 = cost * tax / (1 + r)
print(f"NPV if the full cost were deductible in year 1: {npv - pv_shield + pv_shield_100:,.0f} (ignoring the salvage adjustment)")after-tax operating 752,282 CCA tax shield 147,758 lost shield on salvage -16,454 salvage 93,138 working capital -22,745 equipment -800,000 NPV 153,978 NPV if the full cost were deductible in year 1: 198,948 (ignoring the salvage adjustment)
Replacement decisions
Many capital budgeting decisions are about replacing an existing asset with a new one. The incremental cash flows are then the differences: the cost of the new machine minus the after-tax proceeds from selling the old one, the change in operating costs, the change in tax deductions, and the difference in salvage values at the end. The old machine's original cost is sunk; what matters is what it could be sold for now and what keeping it would cost in the future.
Worked problem
Replacing a machine
An old machine could be sold today for $40,000; if kept, it will last 4 more years with no salvage value. A new machine costs $150,000, lasts 4 years, would be worth $30,000 at the end, and cuts operating costs by $45,000 a year. Ignoring taxes for simplicity, and using 9 %, should the firm replace?
Show solution
- Net investment = 150,000 − 40,000 = 110,000.
- PV of savings = 45,000 × (1 − 1.09^−4) ÷ 0.09 = 145,787.
- PV of salvage = 30,000 ÷ 1.09⁴ = 21,253.
- NPV of replacing = −110,000 + 145,787 + 21,253 = 57,040.
Answer: Replacing adds about $57,000 before taxes. With taxes, the savings would be reduced by the tax rate and the change in tax deductions added.
Practical forecasting
Forecasts of revenue and costs are where most capital budgeting errors begin. Managers proposing a project tend to be optimistic, and they often have an incentive to be. Good practice includes checking forecasts against the experience of past projects, asking why the firm has an advantage that will let it earn more than its cost of capital, building forecasts from specific assumptions (market size, share, price, unit costs) rather than from a target NPV, and reviewing projects after they are completed. Lesson 9 shows how sensitivity, scenario and simulation analysis expose the assumptions that matter most. And whatever the tax rules, the project should make economic sense before the tax shield: an investment that is worthwhile only because of a tax incentive is vulnerable if the rules change.
Common mistakes
MistakeInclude money already spent on a feasibility study.
InsteadIt is sunk; only future cash flows that change with the decision count.
MistakeA building the firm already owns is free to use.
InsteadIts rental or sale value is an opportunity cost.
MistakeSubtract interest payments from project cash flows.
InsteadFinancing costs are captured in the discount rate.
MistakeDepreciation is a cash flow.
InsteadOnly its tax effect, T × D, is a cash flow.
MistakeWorking capital can be ignored because it is recovered.
InsteadInvesting it early and recovering it later has a real present value cost.
Summary and key terms
- Use incremental cash flows: ignore sunk costs, include opportunity costs and side effects, exclude financing costs.
- Project FCF = after-tax operating cash flow + tax shield on capital deductions − capital spending − investment in working capital.
- CCA uses declining-balance classes; the PV of the shield is CdT/(d + r) × (1 + 0.5r)/(1 + r) under the half-year rule, with faster first-year treatment and immediate expensing available for many assets from 2025.
- Salvage reduces the UCC pool; subtract the PV of the lost CCA shield.
- Working capital investment and recovery must be included.
- Replacement decisions use the differences between keeping and replacing; the old asset's cost is sunk.
- Forecast discipline matters more than precise formulas.
- Incremental cash flow
- The change in the firm's cash flow that results from a decision.
- Sunk cost
- A cost already incurred that cannot be recovered.
- Opportunity cost
- The value of the best alternative use of a resource.
- Cannibalization
- Sales a new product takes from the firm's existing products.
- Tax shield
- The tax saved by a deductible expense, equal to the expense times the tax rate.
- Capital cost allowance
- The Canadian tax deduction for depreciable property.
- Undepreciated capital cost
- The remaining balance of a CCA class on which future deductions are calculated.
- MACRS
- The US Modified Accelerated Cost Recovery System for tax depreciation.
- Bonus depreciation
- A US provision allowing an immediate deduction of a percentage of an asset's cost.
- Salvage value
- The amount for which an asset can be sold at the end of a project.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A firm spent $25,000 on a survey last year. Include it in the NPV?
Show answer
No, it is sunk.
A project uses a warehouse the firm could rent for $40,000 a year. Treatment?
Show answer
Include $40,000 a year (after tax) as an opportunity cost.
Revenue 300,000, cash costs 120,000, tax 25 %, deduction 50,000. Operating cash flow including the shield?
Show answer
135,000 + 12,500 = 147,500.
PV of the CCA shield on $50,000 of Class 10 (30 %) equipment, T = 26.5 %, r = 8 %, half-year rule?
Show answer
50,000 × 0.30 × 0.265 ÷ 0.38 × 1.04 ÷ 1.08 = 10,073.
NWC of $20,000 is invested now and recovered in 4 years; r = 10 %. PV cost?
Show answer
20,000 − 13,660 = 6,340.
Why is cannibalization a cost?
Show answer
It reduces cash flows the firm would otherwise earn.
Equipment sold for $30,000 at year 6 from an open Class 8 pool; T = 26.5 %, r = 10 %. PV of the lost shield?
Show answer
30,000 × 0.2 × 0.265 ÷ 0.3 ÷ 1.1⁶ = 2,992.
Old machine sells for $15,000; new costs $70,000 and saves $20,000 a year for 5 years; r = 10 %, no taxes or salvage. NPV?
Show answer
−55,000 + 75,816 = 20,816.
Why should financing costs be excluded from project cash flows?
Show answer
The discount rate already reflects the cost of debt and equity.
Portfolio task: list the incremental cash flows, with sources, for a real investment your organization or a public company has announced.
Show answer
Answers vary; identify sunk costs and opportunity costs explicitly.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.