
FIN-201 · Lesson 11 of 12 · 31 min
The cost of capital
Every capital budgeting calculation in lessons 7 to 9 needed a discount rate, the opportunity cost of capital. This lesson shows how firms estimate it. The cost of capital is the return investors require for providing money to the firm, and therefore the minimum return the firm's investments must earn to maintain its value. Because firms raise money from different investors, mainly lenders and shareholders, with different risks and different tax treatment, the overall cost of capital is a weighted average of the costs of each source: the weighted average cost of capital, or WACC. The lesson builds the WACC step by step, then explains when it is, and is not, the right rate for a particular project.
The idea
Think of the firm as a portfolio of its assets, financed by a portfolio of claims. Investors in the firm's debt and equity together own all of its cash flows, so the expected return on the firm's assets must equal the weighted average of the expected returns on its debt and equity. If a project has the same risk as the firm's existing assets, and is financed in the same proportions, the WACC is the return it must earn to leave investors exactly as well off. A project that earns more creates value; one that earns less destroys it. The cost of capital depends on the use of the money, the risk of the investment, not on where the money happens to come from: a firm that borrows to fund a risky venture does not make the venture safe.
The cost of debt
The cost of debt is the return lenders currently require on the firm's borrowing. For a firm with publicly traded bonds, the yield to maturity on those bonds, from lesson 5, is the standard estimate. The coupon rate on existing debt is not the cost of debt: it reflects market conditions when the bonds were issued. For a firm without traded bonds, analysts use the yield on bonds with the same credit rating, or a bank's quoted rate for new borrowing. Because interest is tax-deductible, the after-tax cost of debt is \( r_D(1 - T) \). For firms with low credit ratings, the promised yield overstates the expected return lenders will actually receive, because it ignores expected default losses.
Interest deductibility has limits. Since 2023, Canada's excessive interest and financing expenses limitation (EIFEL) rules generally cap net interest deductions of larger corporate groups at 30 % of adjusted taxable income (a tax version of EBITDA), with exemptions for smaller Canadian-controlled private corporations and groups with modest net interest. A firm that hits the cap gets less tax saving from additional debt.
Worked problem
Estimating the cost of debt
A company's 8-year bonds, with a 4.5 % semi-annual coupon, trade at $96.20 per $100 of face value. The marginal tax rate is 26 %. Estimate the pre-tax and after-tax cost of debt.
Show solution
- Solve for the yield that makes the bond worth 96.20: semi-annual yield ≈ 2.542 %, so the YTM ≈ 5.08 %.
- After-tax cost of debt = 5.08 % × (1 − 0.26) = 3.76 %.
Answer: The relevant figure is the 5.08 % market yield, not the 4.5 % coupon. After the tax saving, debt costs the firm about 3.76 %.
The cost of preferred shares
Preferred shares that pay a fixed dividend forever are valued as perpetuities, so their cost is the dividend divided by the current price: \( r_P = D_P/P_P \). Preferred dividends are paid from after-tax income and are not deductible by the issuer, so there is no tax adjustment. Canadian banks, insurers and utilities have historically been large issuers of preferred shares, which receive favourable tax treatment for individual investors through the dividend tax credit; US preferred issuance is concentrated among banks and real estate investment trusts.
The cost of equity
The cost of equity is the hardest component to estimate, because shareholders receive no promised payments: their required return must be inferred. Three methods are common, and analysts often use more than one and compare the results.
The CAPM, from lesson 10, gives \( r_E = R_f + \beta(E(R_m) - R_f) \). Practitioners typically use the yield on long-term government bonds (often 10-year) as the riskless rate, a market risk premium of about 4 to 6 %, and a beta estimated from the firm's share returns or from comparable firms. The dividend discount model, from lesson 6, gives \( r_E = D_1/P_0 + g \); it works for stable dividend payers such as utilities, but is very sensitive to the growth estimate and useless for firms that pay no dividends. The bond yield plus risk premium method adds a judgmental premium, often 3 to 5 percentage points, to the yield on the firm's own long-term debt, on the logic that shareholders bear more risk than the firm's lenders.
Worked problem
Three estimates of the cost of equity
A company has a beta of 1.1. The 10-year Government of Canada yield is 3.9 %, and the market risk premium is taken as 5.5 %. Its share price is $48, next year's dividend is expected to be $2.16, and dividends are expected to grow 4.5 % a year. Its bonds yield 5.08 %. Estimate the cost of equity three ways.
Show solution
- CAPM: 3.9 + 1.1 × 5.5 = 9.95 %.
- DDM: 2.16 ÷ 48 + 0.045 = 0.045 + 0.045 = 9.0 %.
- Bond yield plus 4 % premium: 5.08 + 4 = 9.08 %.
Answer: The estimates range from about 9 % to 10 %. An analyst might use 9.5 %, explaining the judgment, rather than pretending any single method is precise.
Weights and the WACC
The weights in the WACC are the proportions of each source of capital in the firm's financing, measured at market values, because market values reflect what investors would have to pay today to acquire those claims. Book values of equity in particular can be far from market values. Many firms use a target capital structure, the mix they aim to maintain over time, rather than the mix on a particular day. The WACC formula combines the after-tax cost of each source with its weight.
Worked problem
Calculating the WACC
A firm has 50 million shares trading at $48, preferred shares with a market value of $200 million and a cost of 6.0 %, and bonds with a market value of $800 million and a yield of 5.08 %. Its cost of equity is 9.5 % and its marginal tax rate 26 %. Find the WACC.
Show solution
- Market value of equity = 50 × 48 = 2,400 million.
- V = 2,400 + 200 + 800 = 3,400 million; weights 70.59 %, 5.88 %, 23.53 %.
- After-tax cost of debt = 5.08 × 0.74 = 3.759 %.
- WACC = 0.7059 × 9.5 + 0.0588 × 6.0 + 0.2353 × 3.759 = 6.706 + 0.353 + 0.885 = 7.94 %.
Answer: The firm's WACC is about 7.9 %. Projects of average risk, financed in the same proportions, should earn at least that.
# WACC from market values, and how sensitive a project's NPV is to it
equity, preferred, debt = 50 * 48, 200, 800          # millions
r_e, r_p, r_d, tax = 0.095, 0.060, 0.0508, 0.26
v = equity + preferred + debt
wacc = equity / v * r_e + preferred / v * r_p + debt / v * r_d * (1 - tax)
print(f"WACC {wacc * 100:.2f} %")
# A 10-year project costing 100 with level after-tax cash flows of 15
for rate in (wacc - 0.02, wacc - 0.01, wacc, wacc + 0.01, wacc + 0.02):
    npv = -100 + 15 * (1 - (1 + rate) ** -10) / rate
print(f"discount rate {rate * 100:5.2f} %: NPV {npv:6.2f}")WACC 7.94 % discount rate 5.94 %: NPV 10.70 discount rate 6.94 %: NPV 5.63 discount rate 7.94 %: NPV 0.91 discount rate 8.94 %: NPV -3.49 discount rate 9.94 %: NPV -7.61
Flotation costs
Raising new capital costs money: underwriting spreads, legal and accounting fees, and the underpricing discussed in lesson 1. These flotation costs are highest for new equity, lower for debt, and avoided entirely when a project is financed from retained earnings. The recommended treatment is to add them to the project's initial cost, as a cash outflow, rather than to adjust the cost of capital, because flotation costs are a one-time expense tied to a particular financing, not a permanent change in investors' required return. If a project needing $50 million can only be financed with a share issue whose costs are 6 % of gross proceeds, the firm must raise \( 50/(1 - 0.06) = 53.19 \) million, so flotation adds $3.19 million to the project's cost.
Divisional and project costs of capital
The WACC is the right discount rate only for projects with the same risk as the firm as a whole. A firm that uses its WACC for all projects will tend to reject good low-risk projects, whose required return is below the WACC, and accept bad high-risk projects, whose required return is above it. Over time it will drift into riskier businesses and destroy value. Firms with distinct divisions, such as a utility with a regulated distribution business and an unregulated generation business, should estimate a separate cost of capital for each.
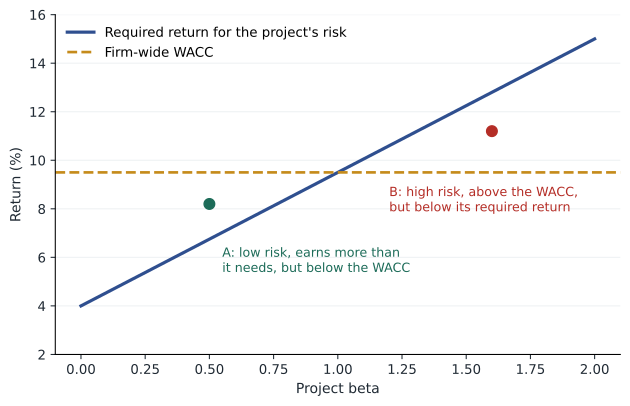
The usual way to estimate a project's cost of capital is the pure-play approach: find publicly traded companies that operate only in the project's line of business, estimate their betas, and adjust for differences in financial leverage. A firm's equity beta reflects both the business risk of its assets and the extra risk of its debt. Removing the effect of debt gives the asset (unlevered) beta; adding back the leverage of the firm doing the project gives the relevant equity beta. With debt assumed to have a beta near zero and a constant debt ratio, a widely used formula, due to Robert Hamada, is shown below.
Worked problem
A pure-play cost of capital
A food company is considering a battery recycling venture. Pure-play recyclers have an average equity beta of 1.6 and a debt-to-equity ratio of 0.5. The food company will finance the venture with a debt-to-equity ratio of 0.25, a pre-tax cost of debt of 5.5 % and a tax rate of 26 %. The riskless rate is 4 % and the market risk premium 5.5 %. Find the venture's cost of capital.
Show solution
- Asset beta = 1.6 ÷ (1 + 0.74 × 0.5) = 1.6 ÷ 1.37 = 1.168.
- Relevered equity beta = 1.168 × (1 + 0.74 × 0.25) = 1.168 × 1.185 = 1.384.
- Cost of equity = 4 + 1.384 × 5.5 = 11.61 %.
- Weights: D/E = 0.25 means D/V = 20 %, E/V = 80 %.
- WACC = 0.8 × 11.61 + 0.2 × 5.5 × 0.74 = 9.29 + 0.81 = 10.10 %.
Answer: The venture should be evaluated at about 10.1 %, not at the food company's own WACC, which might be 7 % or 8 %.
Regulated industries
The cost of capital has a direct public role in regulated industries. Provincial regulators, such as the Ontario Energy Board, the Alberta Utilities Commission and the British Columbia Utilities Commission, and the Canada Energy Regulator for federally regulated pipelines, set an allowed return on equity and a deemed capital structure for utilities. These allowed returns, often in the high single digits, determine the rates customers pay, so regulatory hearings feature competing expert estimates of the cost of equity using the CAPM, DDM and risk premium methods described here.
Common mistakes
Several errors appear again and again in practice. Using the coupon rate instead of the current yield for the cost of debt. Using book values instead of market values for the weights. Using a historical average of a firm's returns as its cost of equity. Applying the firm's WACC to projects of very different risk. Adding arbitrary premiums to the discount rate to reflect project-specific risks that should instead be handled in the cash flows, for example by forecasting expected cash flows that include the chance of failure. And mixing nominal cash flows with a real discount rate, or the reverse. The cost of capital is an estimate, and modest errors in it change NPVs substantially, as the code above shows, so analysts should report a range and test how decisions change across it.
Common mistakes
MistakeThe cost of debt is the coupon rate on the firm's bonds.
InsteadUse the current market yield; the coupon reflects past conditions.
MistakeWeights should come from the balance sheet.
InsteadUse market values or a target capital structure.
MistakeA project financed entirely with cheap debt should be discounted at the cost of debt.
InsteadThe discount rate depends on the project's risk and the firm's overall financing mix, not on the particular source of funds.
MistakeUse the firm's WACC for every project.
InsteadUse a rate that matches each project's systematic risk, for example with pure-play betas.
MistakeFlotation costs should be added to the cost of capital.
InsteadTreat them as an extra initial cash outflow of the project that requires the new financing.
Summary and key terms
- The cost of capital is the return investors require; it depends on the risk of the investment, not the source of funds.
- Cost of debt = current yield on the firm's debt; after tax, rD(1 − T), subject to interest deduction limits.
- Cost of preferred = dividend ÷ price, with no tax adjustment.
- Cost of equity: CAPM, dividend growth model or bond yield plus premium; compare methods.
- WACC = (E/V)rE + (P/V)rP + (D/V)rD(1 − T), using market-value or target weights.
- Add flotation costs to the project's initial outlay.
- Use divisional or project-specific rates, estimated from pure-play betas unlevered and relevered for leverage.
- Cost of capital
- The return investors require for providing capital, and the minimum return the firm's investments must earn.
- WACC
- The weighted average of the after-tax costs of the firm's sources of capital.
- After-tax cost of debt
- The yield on debt multiplied by one minus the tax rate.
- Target capital structure
- The mix of debt and equity a firm aims to maintain.
- Flotation costs
- The costs of issuing new securities.
- Pure-play approach
- Estimating a project's risk from firms that operate only in that business.
- Asset beta
- The beta of a firm's assets, removing the effect of financial leverage.
- Equity beta
- The beta of a firm's shares, reflecting business and financial risk.
- Divisional cost of capital
- A cost of capital estimated for a division with risk different from the firm's.
- Allowed return on equity
- The return a regulator permits a utility to earn on its equity.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Bonds yield 6 %, tax rate 25 %. After-tax cost of debt?
Show answer
4.5 %.
Preferred dividend $1.20, price $24. Cost?
Show answer
5.0 %.
Rf 4 %, beta 0.9, MRP 6 %. Cost of equity?
Show answer
9.4 %.
D₁ $1.50, P₀ $30, g 5 %. Cost of equity?
Show answer
10 %.
E = 600, D = 400 (market values); rE = 11 %, rD = 6 %, T = 25 %. WACC?
Show answer
6.6 + 1.8 = 8.4 %.
A project needs $20 million from a share issue with 5 % flotation costs. Amount raised and flotation cost?
Show answer
21.05 million; 1.05 million.
Equity beta 1.4, D/E 0.6, T 25 %. Asset beta?
Show answer
1.4 ÷ 1.45 = 0.966.
Relever that asset beta at D/E = 0.2.
Show answer
0.966 × 1.15 = 1.11.
Why does using one firm-wide WACC lead firms into riskier businesses?
Show answer
It accepts risky projects with returns below their true required rate and rejects safe ones above theirs.
Portfolio task: estimate the WACC of a public company using its share price, bond yields or credit rating, a beta from a data provider and current government bond yields.
Show answer
Answers vary; show every input with its source and date.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.