
ACCT-470 · Lesson 8 of 12 · 27 min
Financial instruments II: credit losses and hedge accounting
The global financial crisis of 2008 exposed a weakness in the old incurred loss models: banks could not recognize credit losses until a loss event had occurred, so allowances were too little and too late. Both standard setters replaced those models with forward-looking expected loss models, but they could not agree on a single one. IFRS 9 recognizes twelve months of expected losses at first and lifetime losses only after a significant increase in credit risk. The FASB's current expected credit loss (CECL) model, in ASC 326, recognizes lifetime expected losses from the day an asset is recognized. For a food manufacturer the effect is smaller than for a bank, but the same models apply to trade receivables, loans and contract assets. The second half of the lesson turns to hedge accounting, where the frameworks again differ in important details.
Expected credit losses: the IFRS 9 general approach
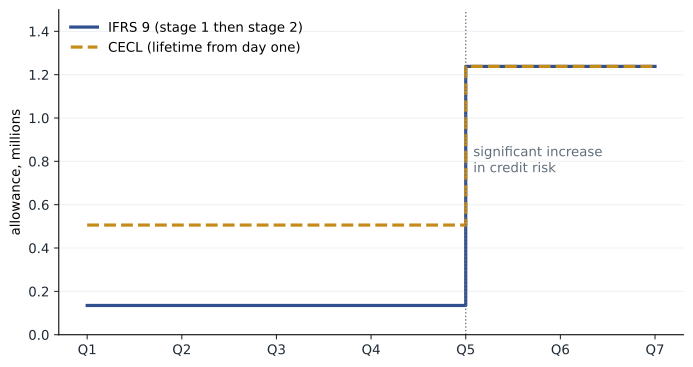
Under IFRS 9's general approach, a financial asset at amortized cost or FVOCI starts in stage 1, with an allowance equal to the expected credit losses resulting from default events possible within the next twelve months. If credit risk increases significantly since initial recognition, the asset moves to stage 2 and the allowance becomes lifetime expected credit losses. If the asset becomes credit-impaired, for example because the borrower is in significant financial difficulty or has defaulted, it moves to stage 3, where lifetime losses continue but interest revenue is calculated on the net carrying amount. The model therefore produces a jump in the allowance when an asset moves from stage 1 to stage 2, a feature known as the cliff effect.
Measuring expected losses requires three inputs: the probability of default (PD) over the relevant horizon, the loss given default (LGD), the share of the exposure that would not be recovered, and the exposure at default (EAD). The estimate is unbiased and probability-weighted, considers a range of possible outcomes and reflects the time value of money. Forward-looking information, such as forecasts of unemployment, sector insolvencies or commodity prices, must be incorporated. Banks build complex models for these inputs; a manufacturer like Tamarind Bay uses simpler approaches but faces the same principles.
# Credit losses at December 31, 2026 (invented). IFRS 9 expected credit losses vs ASC 326 CECL.
# 1. Supplier loan of 25.0 (lesson 7), amortized cost.
ead, lgd = 25.0, 0.45
pd12, pd_life = 0.012, 0.045          # at origination
print("Supplier loan")
print(f"  IFRS 9 stage 1 (12-month ECL): {ead * pd12 * lgd:.3f}")
print(f"  ASC 326 CECL (lifetime from day one): {ead * pd_life * lgd:.3f}")
pd_life2 = 0.110                      # after the supplier lost a major customer
print(f"  After significant increase in credit risk -> IFRS 9 stage 2 (lifetime): {ead * pd_life2 * lgd:.3f}")
print(f"  CECL updated lifetime estimate: {ead * pd_life2 * lgd:.3f}")
# 2. Trade receivables: provision matrix with a forward-looking overlay.
buckets = [("Current", 168.0, 0.004), ("1-30 days", 41.5, 0.012), ("31-60 days", 12.2, 0.045),
           ("61-90 days", 4.6, 0.140), ("Over 90 days", 3.1, 0.480)]
overlay = 1.10                        # forecast: higher grocery-sector insolvencies
print("\nTrade receivables (lifetime losses under both frameworks)")
print(f"{'Age':<14}{'Balance':>9}{'Hist. rate':>12}{'Adjusted':>10}{'Allowance':>11}")
tot = tot0 = 0
for b, bal, r in buckets:
    a = bal * r * overlay; tot += a; tot0 += bal * r
    print(f"{b:<14}{bal:>9.1f}{r:>12.1%}{r * overlay:>10.2%}{a:>11.2f}")
print(f"{'Total':<14}{sum(x[1] for x in buckets):>9.1f}{'':>22}{tot:>11.2f}")
print(f"Allowance without the forward-looking overlay: {tot0:.2f}")
print("ASU 2025-05 expedient: assume current conditions persist for current receivables ->", f"{tot0:.2f}")Supplier loan IFRS 9 stage 1 (12-month ECL): 0.135 ASC 326 CECL (lifetime from day one): 0.506 After significant increase in credit risk -> IFRS 9 stage 2 (lifetime): 1.238 CECL updated lifetime estimate: 1.238 Trade receivables (lifetime losses under both frameworks) Age Balance Hist. rate Adjusted Allowance Current 168.0 0.4% 0.44% 0.74 1-30 days 41.5 1.2% 1.32% 0.55 31-60 days 12.2 4.5% 4.95% 0.60 61-90 days 4.6 14.0% 15.40% 0.71 Over 90 days 3.1 48.0% 52.80% 1.64 Total 229.4 4.24 Allowance without the forward-looking overlay: 3.85 ASU 2025-05 expedient: assume current conditions persist for current receivables -> 3.85
For the 25.0 million supplier loan, IFRS 9 initially requires only the 12-month loss of 0.135 million, while CECL would require the lifetime loss of 0.506 million from day one. In November 2026 the supplier lost a major customer, an event that Tamarind Bay judges to be a significant increase in credit risk because the supplier's lifetime PD has more than doubled and its internal rating has fallen by three notches. The loan moves to stage 2, and the allowance jumps to the lifetime loss of 1.238 million. The judgment of when credit risk has increased significantly is the heart of the IFRS 9 model. IFRS 9 includes a rebuttable presumption that it has when payments are more than 30 days past due, and a low credit risk simplification, but most of the analysis compares the lifetime PD at the reporting date with the lifetime PD expected at that date when the asset was first recognized.
Trade receivables and the provision matrix
For trade receivables and contract assets without a significant financing component, IFRS 9 requires a simplified approach: the allowance is always lifetime expected credit losses, so there are no stages to track. A provision matrix, applying loss rates by age bucket derived from historical experience and adjusted for current and forecast conditions, is a common practical method. The program applies a 10 per cent forward-looking overlay to Tamarind Bay's historical loss rates because economists forecast higher insolvencies among regional grocers in 2027, raising the allowance from 3.85 to 4.24 million. The overlay is a judgment that must be supported by evidence, such as sector insolvency forecasts or the credit ratings of customers, and documented. Auditors look for overlays that are added in bad years and quietly removed in good years without analysis.
ASPE uses an incurred loss model: a private enterprise assesses its financial assets for impairment when there are indications, such as significant financial difficulty of the debtor or a breach of contract, and writes them down to the higher of the present value of expected cash flows and the amount realizable from sale or collateral. Harrow Creek's allowance under ASPE is therefore smaller than the group's IFRS 9 allowance on the same receivables, and the difference is a consolidation adjustment.
Hedge accounting: why it exists
Hedge accounting is optional. It exists because the normal measurement rules can create accounting mismatches: a derivative used to hedge a risk is measured at fair value through profit or loss, while the hedged item, such as a forecast purchase, is not recognized at all until it occurs. Without hedge accounting, profit would swing with the derivative even though the economic position is hedged. Hedge accounting changes the timing of recognition so that gains and losses on the hedging instrument and the hedged item affect profit in the same period. In exchange, the entity must designate the relationship at inception, document the risk management objective and strategy, and show that the hedge is expected to be effective.
| Type | What is hedged | Accounting |
|---|---|---|
| Fair value hedge | Exposure to changes in fair value of a recognized asset, liability or firm commitment | Derivative and hedged item both remeasured through profit or loss |
| Cash flow hedge | Variability in cash flows of a recognized item or highly probable forecast transaction | Effective portion of the derivative in OCI, reclassified when the hedged item affects profit |
| Net investment hedge | Foreign currency exposure of a net investment in a foreign operation | Effective portion in OCI with translation differences |
Tamarind Bay's cash flow hedge of US-dollar purchases
Tamarind Bay buys cocoa, nuts and packaging film in US dollars, while its functional currency is the Canadian dollar. To protect its margins, it hedges about 70 per cent of forecast US-dollar purchases for the next twelve months with foreign exchange forward contracts and designates them as cash flow hedges of highly probable forecast purchases. IFRS 9 replaced IAS 39's 80 to 125 per cent bright-line effectiveness test with three requirements: an economic relationship between the hedged item and the hedging instrument, credit risk that does not dominate the value changes, and a hedge ratio consistent with the quantities actually used for risk management. Ineffectiveness must still be measured and recognized in profit or loss.
# Cash flow hedge of forecast US-dollar ingredient purchases with FX forwards (IFRS 9; invented).
# Dollar-offset comparison and the "lower of" test for the cash flow hedge reserve.
periods = [  # cumulative changes in fair value, millions of Canadian dollars
    ("Q1", 1.10, -1.05), ("Q2", 2.40, -2.28), ("Q3", 0.90, -0.97), ("Q4", 3.20, -2.95)]
print(f"{'Quarter':<8}{'Forward':>9}{'Hedged item':>13}{'Offset':>9}{'To OCI':>9}{'To P&L':>9}")
for q, fwd, item in periods:
    ratio = -fwd / item
    oci = min(abs(fwd), abs(item)) * (1 if fwd > 0 else -1)
    pl = fwd - oci
    print(f"{q:<8}{fwd:>9.2f}{item:>13.2f}{ratio:>9.0%}{oci:>9.2f}{pl:>9.2f}")
print("IFRS 9 has no 80-125% bright line; an economic relationship and hedge ratio are required.")
print("Ineffectiveness arises only when the derivative's cumulative change exceeds the hedged item's.")Quarter Forward Hedged item Offset To OCI To P&L Q1 1.10 -1.05 105% 1.05 0.05 Q2 2.40 -2.28 105% 2.28 0.12 Q3 0.90 -0.97 93% 0.90 0.00 Q4 3.20 -2.95 108% 2.95 0.25 IFRS 9 has no 80-125% bright line; an economic relationship and hedge ratio are required. Ineffectiveness arises only when the derivative's cumulative change exceeds the hedged item's.
The cash flow hedge reserve is adjusted to the lower, in absolute amounts, of the cumulative gain or loss on the hedging instrument and the cumulative change in the fair value of the expected cash flows of the hedged item. When the forward's cumulative gain exceeds the hedged item's cumulative change, as in quarters 1, 2 and 4, the excess is ineffectiveness and goes to profit or loss; when it falls short, as in quarter 3, all of it goes to OCI and no ineffectiveness is recognized. The amounts shown are cumulative, so the profit or loss column at each date is the ineffectiveness recognized to that date. When the inventory is purchased, Tamarind Bay removes the accumulated gain from the reserve and includes it in the initial cost of the inventory, a basis adjustment that IFRS 9 requires for hedges of forecast purchases of non-financial items. The gain then affects profit as the inventory is sold.
Hedge accounting judgments
Several judgments recur. The first is whether a forecast transaction is highly probable: a purchase that the company expects but has not committed to must be supported by budgets, past patterns and the company's ability to carry it out, and hedging 100 per cent of forecast volumes invites challenge. If a forecast transaction is no longer expected to occur, the accumulated amount in OCI must be reclassified to profit immediately, and a pattern of forecasts that fail to occur can call into question the entity's ability to forecast at all. The second is the hedge ratio and sources of ineffectiveness, such as differences in timing, location or quality between the derivative's underlying and the hedged item, or the credit risk of the counterparty. The third is the hedged risk component: IFRS 9 permits hedging a separately identifiable and reliably measurable component of a non-financial item, such as the benchmark gas price embedded in a delivered price, and ASU 2017-12 introduced a similar contractually specified component approach in US GAAP.
The IASB published a request for information on the post-implementation review of IFRS 9's hedge accounting requirements in September 2026, with a 120-day comment period, so changes may follow in later years. ASPE has its own simplified hedge accounting in Section 3856, available only for a few specified relationships, such as hedges of anticipated purchases with forward contracts where the critical terms match; Harrow Creek does not hedge.
Disclosures
Credit risk disclosures explain the entity's credit risk management practices, the inputs, assumptions and techniques used to measure expected losses, how forward-looking information is incorporated, changes in the allowance during the period, the credit quality of financial assets and concentrations of risk. Hedge accounting disclosures cover the risk management strategy, how hedging affects the amount, timing and uncertainty of future cash flows, and the effects on the financial statements, including amounts in the hedge reserve and, under IFRS 9, ineffectiveness recognized. Tamarind Bay's largest customer accounts for 14 per cent of revenue, a concentration that must be disclosed and that also matters for the going concern assessment in lesson 12.
Worked problem
Moving between stages
A 10.0 million loan to a distributor has a 12-month PD of 1.0 per cent and a lifetime PD of 3.0 per cent at origination, with LGD of 50 per cent. A year later its lifetime PD is 9.0 per cent and the distributor is 20 days late on a payment. What allowance is required?
Show solution
- Stage 1 at origination: 10.0 × 1.0% × 50% = 0.05 million.
- Assess significant increase in credit risk: lifetime PD has tripled, a significant increase; the 30-day rebuttable presumption has not been reached, but it is not needed.
- Move to stage 2: allowance = 10.0 × 9.0% × 50% = 0.45 million.
- Disclose the change in the allowance and the reasons.
Answer: The allowance becomes 0.45 million. Under IFRS 9 the increase from 0.05 is the cliff effect; under CECL the increase is from 0.15.
Common mistakes
MistakeRecognizing credit losses only when a customer defaults.
InsteadRecognize expected losses using forward-looking information, under IFRS 9 or CECL.
MistakeUsing historical loss rates without considering forecasts.
InsteadAdjust historical rates for current conditions and reasonable and supportable forecasts, and document overlays.
MistakeWaiting for 30 days past due before moving loans to stage 2.
InsteadThe 30-day test is a backstop; assess significant increases in credit risk with forward-looking information.
MistakeDesignating hedges of forecast volumes the company may never buy.
InsteadHedge only highly probable transactions and reclassify OCI amounts if a forecast transaction is no longer expected.
MistakeLeaving basis adjustments or reclassifications to chance.
InsteadPlan how OCI amounts will be reclassified or included in inventory cost when the hedged item affects profit.
MistakeForgetting that hedge accounting is optional and documentation is required at inception.
InsteadDesignate and document the relationship when it starts; it cannot be applied retrospectively.
Summary and key terms
- IFRS 9 recognizes 12-month losses in stage 1 and lifetime losses after a significant increase in credit risk.
- Expected losses combine PD, LGD and EAD with forward-looking information in an unbiased, probability-weighted estimate.
- Trade receivables use the simplified lifetime approach, often through a provision matrix.
- Hedge accounting aligns the timing of gains and losses on hedging instruments and hedged items, but requires documentation at inception.
- IFRS 9 has no bright-line effectiveness test but recognizes ineffectiveness and requires basis adjustments for non-financial items.
- Highly probable forecasts, hedge ratios and risk components are the main hedge accounting judgments.
- Stage 2
- The IFRS 9 stage for assets whose credit risk has increased significantly, with lifetime expected losses.
- Significant increase in credit risk
- The IFRS 9 trigger for moving from 12-month to lifetime expected credit losses.
- Basis adjustment
- Including a cash flow hedge gain or loss in the initial cost of a non-financial asset.
- Expected credit losses
- A probability-weighted estimate of credit losses over the relevant horizon.
- Probability of default (PD)
- The likelihood that a borrower will default over a given period.
- Loss given default (LGD)
- The proportion of an exposure that would be lost if default occurs.
- Exposure at default (EAD)
- The amount owed at the time of default.
- Provision matrix
- A method that applies loss rates to receivables grouped by age or other characteristics.
- Cash flow hedge
- A hedge of exposure to variability in cash flows, with effective gains and losses deferred in OCI.
- Highly probable forecast transaction
- An expected transaction that is significantly more likely than not to occur.
Practice problems
Work each problem on paper first, then reveal the answer to check.
What is the 12-month ECL on the supplier loan at origination?
Show answer
0.135 million.
Rerun the credit loss program with an overlay of 1.25. What is the trade receivables allowance?
Show answer
About 4.81 million.
Why is the supplier's loss of a major customer relevant?
Show answer
It is evidence of a significant increase in credit risk, moving the loan to stage 2.
What is the cliff effect?
Show answer
The jump in the allowance under IFRS 9 when an asset moves from 12-month to lifetime expected losses.
Why must overlays be documented?
Show answer
They are judgments that can be used to manage earnings; evidence and consistent removal criteria are needed.
In the hedge program, why is nothing recognized in profit in quarter 3?
Show answer
The forward's cumulative change is smaller than the hedged item's, so the whole amount goes to OCI.
What happens if a hedged forecast purchase is no longer expected to occur?
Show answer
The accumulated amount in OCI is reclassified to profit or loss immediately.
Name two sources of hedge ineffectiveness.
Show answer
Differences in timing, location or quality between the derivative and hedged item; counterparty credit risk; differences in notional amounts.
Why is hedging 100 per cent of forecast volume risky for hedge accounting?
Show answer
Forecasts are uncertain; overhedging may mean some transactions are not highly probable.
Which concentration must Tamarind Bay disclose?
Show answer
Its largest customer accounts for 14 per cent of revenue.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.