
ACCT-470 · Lesson 1 of 12 · 30 min
Judgment, materiality and the reporting framework
Intermediate and advanced financial accounting taught you the rules: how to measure a lease liability, when to recognize revenue, how to consolidate a subsidiary. This course is about the part of financial reporting that the rules cannot settle on their own. Almost every important number in a set of financial statements rests on a judgment: which standard applies, which estimate is most reasonable, whether an item is material, how much to disclose. Preparers make those judgments, auditors challenge them, regulators review them after the fact, and investors live with the consequences. Doing them well is what separates a technically correct set of statements from a useful one.
Each lesson takes a reporting issue that regularly causes difficulty in practice, sets out what the standards require, shows where the judgment lies and works through it with numbers. The issues are drawn from areas that regulators and audit inspectors repeatedly flag: presentation and performance measures, revenue, leases, impairment, financial instruments, fair value, earnings per share, income taxes, provisions and disclosure. Several of them are changing. Two major presentation reforms take effect for 2027 year ends, and the standard setters have active projects on goodwill, financial instruments with characteristics of equity and provisions. Where a requirement is new or still moving, the lesson says so and gives the date of the information.
The course follows one invented company. Tamarind Bay Foods Inc. is a packaged-foods manufacturer based in Mississauga, Ontario, listed on the Toronto Stock Exchange (TSX), with three operating segments: Snacks, Beverages and Frozen. It reports under IFRS Accounting Standards, which Canadian publicly accountable enterprises must apply under Part I of the CPA Canada Handbook. It owns 80 per cent of Harrow Creek Packaging Ltd., a private packaging maker that prepares its own statements under ASPE for its lenders. For the year ending December 31, 2026, Tamarind Bay expects revenue of about 1,840 million dollars and profit before tax, before any impairment, of about 144 million. The reporting team, led by the chief financial officer, is working through its year-end judgments and preparing to adopt IFRS 18 in 2027. Every person, company and figure in the case is invented.
Where judgment enters financial reporting
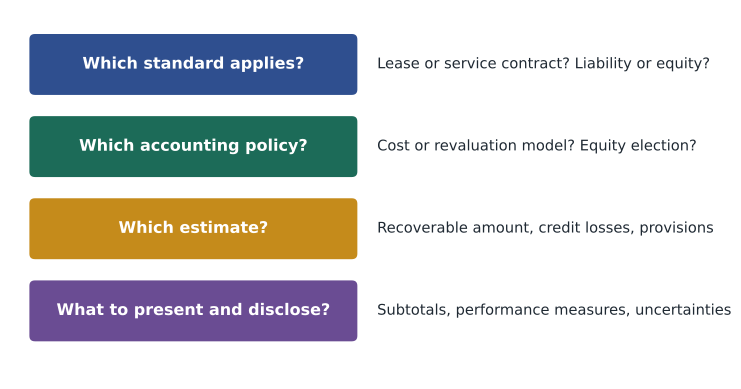
Judgment enters at four levels. The first is the choice of framework and standard: whether a contract is within the leases standard or the revenue standard, whether an instrument is a liability or equity, whether the entity controls another entity. The second is the choice of accounting policy where the standards allow options, such as the cost or revaluation model for property, or the election to present certain equity investments through other comprehensive income. The third, and most common, is estimation: useful lives, expected credit losses, recoverable amounts, provisions and fair values all require assumptions about the future. The fourth is presentation and disclosure: how to aggregate line items, which performance measures to show, what to say about uncertainties and how much detail is enough.
Judgment is not the same as discretion. The standards require that judgments be reasonable, supportable by evidence available at the reporting date, consistent from period to period unless circumstances change, and free from bias. Bias is the central risk. A preparer who, in each of twenty estimates, picks the end of the reasonable range that flatters profit has made twenty individually defensible decisions and one misleading set of statements. Auditors are required to consider whether the judgments, taken together, indicate possible management bias, and securities regulators look for patterns across periods, such as reserves that grow in good years and are released in bad ones.
IFRS Accounting Standards are principles-based. When no standard specifically applies, IAS 8 directs management to develop a policy that results in relevant and reliable information, first by reference to standards dealing with similar issues, then to the Conceptual Framework, and then, if consistent with those, to the pronouncements of other standard setters that use a similar framework, such as US GAAP. IAS 8 also distinguishes accounting policies, which are applied retrospectively when changed, from accounting estimates, which are defined since a 2023 amendment as monetary amounts subject to measurement uncertainty and are changed prospectively. In 2027 IFRS 18 renames IAS 8 Basis of Preparation of Financial Statements and moves into it the general requirements on fair presentation, going concern and disclosure of judgments that used to sit in IAS 1.
Materiality is a judgment, not a percentage
Information is material if omitting, misstating or obscuring it could reasonably be expected to influence the decisions that the primary users of the financial statements make on the basis of those statements. The IASB's Practice Statement 2, Making Materiality Judgements (2017), sets out a four-step process: identify information that could be material, assess whether it is material using quantitative and qualitative factors, organize it in the draft statements, and review the draft as a whole. Obscuring is part of the definition since 2018: burying important information among immaterial detail can be as misleading as leaving it out.
Practitioners nevertheless start with numbers, because a rule of thumb anchors the discussion. Common starting points are 5 per cent of profit before tax for a profitable company, 0.5 to 1 per cent of revenue or total assets for companies with volatile or negligible profit, and 1 to 2 per cent of equity for some asset-heavy entities. The reporting team at Tamarind Bay Foods Inc. computes several benchmarks before choosing one.
# Materiality benchmarks for Tamarind Bay Foods (invented figures, millions of dollars).
# Common rules of thumb are applied to several bases; judgment picks one and documents why.
base = {
    "Profit before tax, before impairment": 144.2,
    "Revenue": 1840.0,
    "Total assets": 2150.0,
    "Equity": 905.0,
    "Adjusted EBITDA": 268.4,
}
rule = {
    "Profit before tax, before impairment": (0.05, "5%"),
    "Revenue": (0.005, "0.5%"),
    "Total assets": (0.005, "0.5%"),
    "Equity": (0.01, "1%"),
    "Adjusted EBITDA": (0.03, "3%"),
}
print(f"{'Benchmark':<38}{'Amount':>9}{'Rate':>7}{'Threshold':>11}")
for k, v in base.items():
    r, lab = rule[k]
    print(f"{k:<38}{v:>9.1f}{lab:>7}{v * r:>11.2f}")
chosen = base["Profit before tax, before impairment"] * 0.05
print(f"\nChosen overall threshold: {chosen:.1f}")
print(f"Clearly trivial (5% of threshold): {chosen * 0.05:.2f}")Benchmark Amount Rate Threshold Profit before tax, before impairment 144.2 5% 7.21 Revenue 1840.0 0.5% 9.20 Total assets 2150.0 0.5% 10.75 Equity 905.0 1% 9.05 Adjusted EBITDA 268.4 3% 8.05 Chosen overall threshold: 7.2 Clearly trivial (5% of threshold): 0.36
The team chooses profit before tax before impairment, because investors in a stable, profitable food company focus on earnings, and the year's goodwill impairment is unusual. Excluding it avoids a threshold that would swing with a non-recurring item. The resulting overall threshold of about 7.2 million is a starting point. Some items are material at far lower amounts because of their nature: related-party transactions, executive compensation, breaches of covenants or laws, and anything that affects a trend or a key performance indicator that the market watches.
| Qualitative factor | Why it can make a small amount material |
|---|---|
| Changes a loss into a profit, or a miss into a beat | Investors react to whether a target or consensus was met |
| Affects compliance with a covenant or regulation | Can trigger default, penalties or loss of a licence |
| Masks a change in earnings or other trends | Users extrapolate trends |
| Increases management compensation | Signals possible bias or intent |
| Involves an unlawful transaction or a related party | Users care about the nature, not just the size |
| Affects a segment that is important to the business | May be material to that segment's profitability |
| Arises from an item capable of precise measurement | Less tolerance than for an inherently imprecise estimate |
A prior-period error: correct, restate or revise?
During the 2026 year-end work, the accounts receivable team discovers that trade promotion accruals at December 31, 2025 were understated by 5.9 million. Promotions earned by retailers in December 2025 were recorded in January 2026, so 2025 revenue and profit were overstated and 2026 understated by the same amount. Is the error material, and what should Tamarind Bay Foods Inc. do about it?
# Is a prior-year error material? Quantitative and qualitative screen (invented figures).
# 2025 trade promotion accruals were understated by 5.9 million, overstating 2025 profit.
err = 5.9
pbt_2025, pbt_2026 = 131.0, 144.2          # profit before tax, millions
consensus_eps_2025, reported_eps_2025, shares = 0.78, 0.80, 120.0
tax = 0.265
eps_effect = err * (1 - tax) / shares
print(f"Error as % of 2025 profit before tax: {err / pbt_2025:.1%}")
print(f"Error as % of 2026 profit before tax: {err / pbt_2026:.1%}")
print(f"After-tax EPS effect: {eps_effect:.3f}")
print(f"2025 EPS without the error: {reported_eps_2025 - eps_effect:.3f} vs consensus {consensus_eps_2025:.2f}")
qual = {
    "turns a miss of consensus into a beat": reported_eps_2025 - eps_effect < consensus_eps_2025,
    "affects a loan covenant": False,
    "masks a change in earnings trend": True,
    "increases management bonus": True,
    "arises from an estimate (imprecise by nature)": False,
}
for k, v in qual.items():
    print(f"  {'YES' if v else 'no ':<4}{k}")
flags = sum(qual.values())
print("Assessment:", "material to 2025 despite being under 5%" if flags >= 2 else "not material to 2025")
# Correcting the whole 5.9 in 2026 would distort 2026 by the same amount (rollover vs iron curtain)
print(f"Effect on 2026 if corrected in 2026 instead: {err / pbt_2026:.1%} of profit before tax")Error as % of 2025 profit before tax: 4.5% Error as % of 2026 profit before tax: 4.1% After-tax EPS effect: 0.036 2025 EPS without the error: 0.764 vs consensus 0.78 YES turns a miss of consensus into a beat no affects a loan covenant YES masks a change in earnings trend YES increases management bonus no arises from an estimate (imprecise by nature) Assessment: material to 2025 despite being under 5% Effect on 2026 if corrected in 2026 instead: 4.1% of profit before tax
On its size alone the error is below the usual 5 per cent threshold for both years. The qualitative screen tells a different story. The 2025 results narrowly beat analyst consensus only because of the error, the bonus pool depended on the reported figure and the error flattered the trend. Trade promotion accruals can be calculated precisely from retailer claims, so the error is not an inherently imprecise estimate. The team concludes that the error is material to 2025.
Under IAS 8, a material prior-period error is corrected retrospectively: the comparative 2025 figures are restated in the 2026 statements as if the error had never occurred, the opening balance of retained earnings for the earliest period presented is adjusted, and the nature of the error and the amount of the correction for each line item and for earnings per share are disclosed. If the error had been immaterial, it could simply be corrected in 2026, but IAS 8 does not permit leaving even immaterial errors uncorrected if they were made intentionally to achieve a particular presentation. Because Tamarind Bay is a reporting issuer, the securities regulators also expect a news release and, depending on the facts, may expect the company to file amended interim reports. If the company had not yet issued its 2025 statements, it would simply correct them.
A restatement is rarely the end of the matter. It usually indicates a material weakness in internal control over financial reporting, because a control should have caught a misstatement of this kind; ACCT-431 discusses how auditors evaluate the deficiency. It invites questions from regulators, plaintiffs and lenders. And it can affect compensation: clawback policies now require listed companies in the United States, and many Canadian companies voluntarily, to recover incentive pay that was based on misstated results. The cost of an error therefore depends far more on how and when it is found than on its size.
Policies, estimates and the boundary between them
Whether a change is a change in policy or a change in estimate matters because the accounting is different: retrospective for policies, prospective for estimates. The boundary is clearer than it once was. A change in measurement basis, such as moving inventory from FIFO to weighted average cost, is a change in policy. A change in an input or a technique used to develop an estimate, such as revising the useful life of a production line or changing the weightings in a credit loss model, is a change in estimate. When it is difficult to tell, both frameworks treat the change as a change in estimate. What preparers must not do is present a correction of an error as a change in estimate, which avoids restatement; regulators and auditors look closely for this.
Worked problem
Policy, estimate or error?
Tamarind Bay Foods Inc. makes three changes in 2026: (a) it revises the useful life of its Frozen packaging lines from 12 to 9 years after a technology review; (b) it moves its private subsidiary's inventory from FIFO to weighted average cost to align with the group; (c) it discovers that a formula in the 2025 depreciation spreadsheet omitted a line acquired in September 2025.
Show solution
- (a) New information about how long the asset will be used: a change in estimate, applied prospectively from 2026.
- (b) A change in measurement basis: a change in accounting policy, applied retrospectively unless impracticable, with disclosure of the reasons and effects.
- (c) Information available when the 2025 statements were prepared was not used correctly: an error, corrected retrospectively if material and in the current period if not.
- Document each assessment, including why (c) is not an estimate change.
Answer: (a) estimate, (b) policy, (c) error. The labels drive the accounting, so the reasoning must be written down.
Private entities in the group
Tamarind Bay's subsidiary Harrow Creek Packaging Ltd. is not publicly accountable, so it may use ASPE in its own statements, as it does for its bank. ASPE requires fewer estimates and disclosures than IFRS Accounting Standards: for example, it permits the taxes payable method for income taxes and has simpler financial instrument rules. For consolidation, the subsidiary's figures must be converted to the group's IFRS policies. A new option arrives in 2027: IFRS 19 Subsidiaries without Public Accountability: Disclosures, issued in May 2024 and effective for periods beginning on or after January 1, 2027, lets an eligible subsidiary whose parent prepares IFRS consolidated statements apply full IFRS recognition and measurement with reduced disclosures. That removes the need to keep two sets of accounting for group reporting purposes, and the AcSB has incorporated it into Part I. Harrow Creek's controller is evaluating whether IFRS with IFRS 19 would be cheaper than ASPE plus conversion adjustments.
Professional judgment in practice
Good judgment can be learned. Practitioners who do it well follow a disciplined process: they identify the issue and the facts; they find the applicable requirements, including any interpretations, agenda decisions and regulator guidance; they set out the alternatives; they evaluate each against the requirements and the evidence; they reach a conclusion; and they document the reasoning, including why the alternatives were rejected. The documentation matters because judgments are reviewed later by auditors, audit committees, regulators and sometimes courts, all of whom have the benefit of hindsight. A well-reasoned memo written at the time protects a reasonable judgment from second-guessing in a way that no later explanation can.
Judgments also need to be disclosed. IAS 1, and from 2027 IAS 8, requires disclosure of the judgments, apart from estimates, that have the most significant effect on the amounts recognized, and of the assumptions and other sources of estimation uncertainty that have a significant risk of causing a material adjustment within the next financial year, with sensitivity or ranges where useful. These disclosures are among the most read by investors and the most criticized by regulators when they are generic. A disclosure that says impairment testing requires judgment tells a reader nothing; one that says a 0.5 point rise in the discount rate would eliminate the headroom on the Frozen unit tells them a great deal.
Common mistakes
MistakeTreating 5 per cent of profit as the definition of materiality.
InsteadUse quantitative benchmarks as a starting point and then consider the qualitative factors and the users' perspective.
MistakeLeaving a known error uncorrected because it is small.
InsteadCorrect errors; small intentional misstatements are never acceptable, and small errors can accumulate.
MistakeCalling the correction of an error a change in estimate.
InsteadAn error arises from misuse or neglect of information available at the time; a change in estimate arises from new information.
MistakePicking the most favourable end of each estimate's range.
InsteadMake unbiased point estimates and consider whether judgments taken together show bias.
MistakeWriting the judgment memo after the auditor asks for it.
InsteadDocument the issue, alternatives and reasoning when the judgment is made.
MistakeGiving generic disclosures about estimates.
InsteadDisclose entity-specific assumptions, sensitivities and changes from the prior period.
Summary and key terms
- Judgment enters at four levels: which standard applies, which policy to choose, which estimate to make and what to present and disclose.
- Judgments must be reasonable, supportable, consistent and free of bias, and they are assessed in total as well as one by one.
- Materiality depends on what could influence users; quantitative benchmarks are starting points, and qualitative factors can make small items material.
- Material prior-period errors are corrected by retrospective restatement under IAS 8.
- Changes in policy are retrospective, changes in estimate prospective, and corrections of errors must not be presented as either.
- IFRS 19 offers eligible subsidiaries reduced disclosures from 2027; ASPE remains available for private enterprises.
- A documented judgment process and entity-specific disclosure are the best protection against hindsight.
- IFRS 19
- A disclosure standard, effective 2027, that lets eligible subsidiaries of IFRS parents apply IFRS with reduced disclosures.
- IFRS Practice Statement 2
- Non-mandatory IASB guidance on making materiality judgements.
- Professional judgment
- The application of training, knowledge and experience to make informed decisions where the standards do not dictate an answer.
- Materiality
- The quality of information whose omission, misstatement or obscuring could reasonably be expected to influence users' decisions.
- Management bias
- A lack of neutrality in the preparation of information, often shown by consistently favourable choices.
- Accounting estimate
- A monetary amount in the financial statements that is subject to measurement uncertainty.
- Retrospective restatement
- Correcting prior-period amounts as if an error had never occurred.
- Clearly trivial
- A threshold below which misstatements are not accumulated, because they are inconsequential individually and in total.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Name the four levels at which judgment enters financial reporting and give an example of each.
Show answer
Choice of standard (lease or service contract), choice of policy (cost or revaluation model), estimate (recoverable amount), presentation and disclosure (which performance measures to show).
Why might a company choose profit before tax before impairment as its materiality benchmark?
Show answer
Profit is what users focus on, and excluding an unusual impairment avoids a benchmark that swings with a non-recurring item.
Rerun the benchmark program with revenue of 2,100 million. Which benchmark is now largest?
Show answer
Revenue: 0.5 per cent of 2,100 is 10.5, larger than the others.
Give three qualitative factors that could make a 3 per cent error material.
Show answer
It turns a miss into a beat, affects a covenant, masks a trend, increases bonuses, involves a related party or an illegal act.
In the error program, change the consensus to 0.75 (or 0.79 on the US site). Does the assessment change? Why?
Show answer
The consensus factor becomes false, leaving two flags (trend and bonus); the program still flags the error as material, which shows the result depends on how many qualitative factors apply.
Classify: a company changes its estimate of warranty claims from 2 to 3 per cent of sales after new claims data.
Show answer
A change in accounting estimate, applied prospectively.
Why must judgments be documented at the time they are made?
Show answer
Reviewers later have hindsight; contemporaneous documentation shows the judgment was reasonable given the information available.
What makes a disclosure about estimation uncertainty useful?
Show answer
Entity-specific assumptions, quantified sensitivities or ranges, and explanation of changes from the prior period.
When can a subsidiary of an IFRS parent use IFRS 19?
Show answer
When it has no public accountability and its parent prepares consolidated IFRS statements available for public use, for periods beginning on or after January 1, 2027.
What is the main risk when many estimates are made by the same people?
Show answer
Systematic bias, where each estimate is defensible but together they consistently favour reported profit.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.