
ACCT-211 · Lesson 6 of 12 · 29 min
Cash and receivables
Cash and receivables are the most liquid assets and, for Northlake, two of the largest: sensor stations are often sold on credit to municipalities and farms, and some customers pay over years. ACCT-101 covered bank reconciliations, internal control over cash and the basic allowance method for doubtful accounts. This lesson moves to intermediate questions: what counts as cash and how restricted cash is reported; how receivables are measured when there are discounts and long payment terms; how credit losses are estimated under the expected credit loss models; how notes receivable are carried at amortized cost using the effective interest method; and when selling receivables to a factor removes them from the balance sheet.
Cash, cash equivalents and restricted cash
Cash includes coins, currency, bank deposits available on demand and negotiable instruments such as cheques received but not yet deposited. Cash equivalents, defined in lesson 3, are short-term, highly liquid investments with original maturities of about three months or less. Items that are not cash include postdated cheques from customers (receivables), IOUs from employees (receivables), postage stamps (prepaid expenses) and travel advances (prepaid expenses or receivables). Cash in foreign currencies is translated at the closing exchange rate.
Restricted cash, such as deposits held in escrow or cash that must be used for a specified purpose, is reported separately if material and classified as current or non-current depending on when the restriction lapses. Compensating balances, minimum deposits a bank requires as part of a loan arrangement, are disclosed. A bank overdraft is normally a current liability; under IAS 7 it may be included in cash and cash equivalents for the cash flow statement when it is repayable on demand and forms an integral part of cash management.
Recognizing and measuring receivables
Trade receivables arise from selling goods and services on credit; other receivables include loans to employees, interest and dividends receivable, tax refunds and amounts due from related parties. A trade receivable without a significant financing component is initially measured at the transaction price (lesson 4). Trade discounts, reductions from list price offered to classes of customers, are simply deducted: the receivable and revenue are recorded at the net price. Cash (sales) discounts for early payment, such as 2/10, net 30, are variable consideration: the entity estimates the discounts customers will take and records revenue net of them, adjusting the estimate as customers pay.
Worked problem
Cash discounts as variable consideration
Northlake sells parts to distributors for $50,000 on terms 2/10, net 30. From experience, 70 per cent of distributors pay within 10 days. How are revenue and the receivable recorded?
Show solution
- Expected discount = 50,000 × 70% × 2% = $700.
- Record a receivable of $50,000, revenue of $49,300 and a liability (or contra-receivable) for expected discounts of $700.
- When distributors owing $35,000 pay within 10 days, they remit $34,300; the $700 allowance is used.
- If more or fewer customers take the discount than expected, revenue is adjusted.
Answer: Revenue $49,300, net of expected discounts; the $700 difference sits in an allowance until settled.
A receivable due beyond twelve months that contains a significant financing component is measured at the present value of the cash flows, using the market rate for the customer's credit, as in the farm cooperative example in lesson 5. After initial recognition, trade receivables are measured at amortized cost under IFRS 9 (or at amortized cost under ASPE Section 3856), less a loss allowance.
Expected credit losses
IFRS 9, Financial Instruments, replaced the old incurred-loss model with an expected credit loss (ECL) model in 2018. A loss allowance is recognized from the start, before any loss event occurs, based on forward-looking information. For most financial assets IFRS 9 uses a general three-stage approach: stage 1 assets (no significant increase in credit risk since initial recognition) carry an allowance equal to 12-month expected credit losses; stage 2 assets (significant increase in credit risk) and stage 3 assets (credit-impaired) carry lifetime expected credit losses, with interest on stage 3 computed on the net carrying amount. For trade receivables and contract assets without a significant financing component, IFRS 9 requires a simplified approach: always use lifetime expected credit losses, typically estimated with a provision matrix based on historical loss rates by ageing category, adjusted for current conditions and forecasts.
ASPE keeps an incurred-loss approach: under Section 3856, a financial asset is assessed for impairment when there are indications of impairment, such as significant financial difficulty of the debtor or a breach of contract, and written down to the higher of the present value of expected cash flows and the amount realizable from selling it or any collateral. In practice, private enterprises still use an allowance based on ageing and specific accounts, but they do not need forward-looking loss estimates for all receivables.
# Provision matrix for trade receivables (illustrative loss rates)
ageing = {               # bucket: (balance, historical loss rate)
    "Current":        (6_200_000, 0.004),
    "1-30 days":      (1_500_000, 0.015),
    "31-60 days":     (  600_000, 0.050),
    "61-90 days":     (  250_000, 0.120),
    "Over 90 days":   (  150_000, 0.400),
}
forward_adjustment = 1.15    # forecasts point to a weaker farm economy
total_bal = total_allow = 0
for bucket, (bal, rate) in ageing.items():
    allow = bal * rate * forward_adjustment
    total_bal += bal; total_allow += allow
    print(f"{bucket:<13} {bal:>10,}  rate {rate*forward_adjustment:6.2%}  allowance {allow:>9,.0f}")
print(f"Total receivables {total_bal:,}; required allowance {total_allow:,.0f}")
existing = 120_000
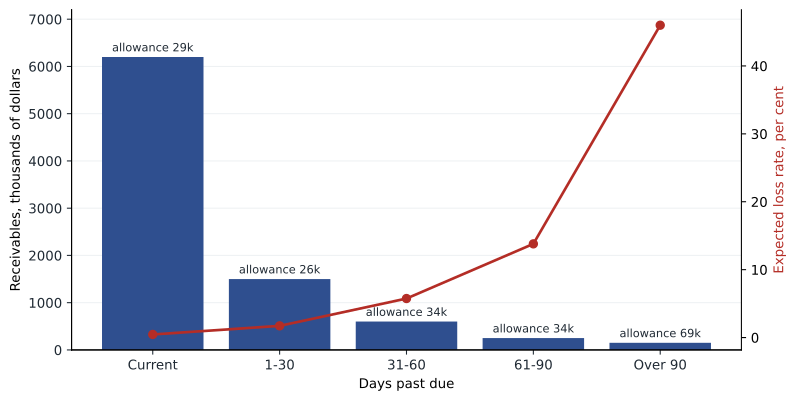
print(f"Existing allowance {existing:,}; credit loss expense this period {total_allow - existing:,.0f}")Current 6,200,000 rate 0.46% allowance 28,520 1-30 days 1,500,000 rate 1.72% allowance 25,875 31-60 days 600,000 rate 5.75% allowance 34,500 61-90 days 250,000 rate 13.80% allowance 34,500 Over 90 days 150,000 rate 46.00% allowance 69,000 Total receivables 8,700,000; required allowance 192,395 Existing allowance 120,000; credit loss expense this period 72,395
The provision matrix applies historical loss rates by age, increased by 15 per cent because forecasts point to a weaker farm economy. Northlake needs an allowance of about $192,000 against $8.7 million of receivables; with $120,000 already in the allowance, it records credit loss expense of about $72,000. The forward-looking adjustment is the step that distinguishes the expected loss models from the older practice of relying only on history.
Write-offs, recoveries and presentation
When an account is determined to be uncollectible, it is written off against the allowance: debit the allowance, credit the receivable. The write-off does not change net receivables or expense, because the loss was already provided for. If a written-off account is later collected, the write-off is reversed (debit receivable, credit allowance) and the cash collection recorded. Credit loss (impairment) expense is presented as a separate line or disclosed; IFRS requires impairment losses on financial assets, including reversals, to be presented as a separate line in the statement of profit or loss. Notes disclose the allowance movements, the ageing of receivables, concentrations of credit risk and the methods and assumptions used.
Notes receivable and the effective interest method
A note receivable is a written promise to pay a specified amount, often with interest, at a future date. Northlake accepts notes from municipalities and farm cooperatives that cannot pay for networks immediately. If the stated interest rate equals the market rate for the customer's credit, the note is recorded at face value. If the stated rate is below market, or the note carries no interest at all, it is recorded at the present value of its cash flows discounted at the market rate, and the discount is recognized as interest income over the term using the effective interest method: interest income each period equals the carrying amount at the start of the period times the market (effective) rate; the difference between that and the cash interest received increases the carrying amount.
# Note receivable at amortized cost: effective interest method
face, stated, market, years = 300_000, 0.02, 0.06, 3
cash_interest = face * stated
pv = sum(cash_interest / (1 + market) ** t for t in range(1, years + 1)) + face / (1 + market) ** years
print(f"Initial carrying amount (present value): {pv:,.0f}  discount {face - pv:,.0f}")
carrying = pv
print(f"{'Year':<5}{'Cash':>10}{'Interest income':>17}{'Amortization':>14}{'Carrying':>12}")
for y in range(1, years + 1):
    income = carrying * market
    amort = income - cash_interest
    carrying += amort
print(f"{y:<5}{cash_interest:>10,.0f}{income:>17,.0f}{amort:>14,.0f}{carrying:>12,.0f}")Initial carrying amount (present value): 267,924 discount 32,076 Year Cash Interest income Amortization Carrying 1 6,000 16,075 10,075 277,999 2 6,000 16,680 10,680 288,679 3 6,000 17,321 11,321 300,000
Northlake sells a network to a town for a $300,000 three-year note at 2 per cent when the town's market borrowing rate is 6 per cent. The note is worth $267,924 at inception, so revenue is $267,924, not $300,000; the $32,076 discount is interest that Northlake earns over three years. Interest income rises each year (about $16,075, $16,680 and $17,321) because it is computed on a growing carrying amount, which reaches $300,000 at maturity.
Worked problem
Zero-interest note
Northlake receives a $100,000 note due in 2 years with no stated interest in exchange for equipment whose cash price is unknown. The customer's market rate is 5 per cent. Record the note and the interest.
Show solution
- Present value = 100,000 ÷ 1.05² = $90,703. Record the receivable at $90,703 and revenue of $90,703.
- Year 1 interest income = 90,703 × 5% = $4,535; carrying amount $95,238.
- Year 2 interest income = 95,238 × 5% = $4,762; carrying amount $100,000, collected at maturity.
Answer: Total interest income of $9,297 over two years equals the discount; revenue is the present value, $90,703.
Transfers of receivables
Companies can turn receivables into cash before customers pay by selling them to a factor or securitizing them, or by borrowing against them. The accounting question is whether the receivables are derecognized (removed from the balance sheet, with any gain or loss recognized) or remain on the balance sheet with a liability for the cash received (a secured borrowing). Selling receivables without recourse, where the factor bears the credit risk, usually qualifies as a sale. Selling with recourse, where the seller must compensate the factor for uncollectible accounts, often does not.
Under IFRS 9 the test focuses on risks and rewards, then control. If the entity transfers the contractual rights to the cash flows (or passes them through under strict conditions) and transfers substantially all the risks and rewards of ownership, it derecognizes the receivables. If it retains substantially all the risks and rewards, for example through full recourse, it continues to recognize them and records the proceeds as a liability. If it neither transfers nor retains substantially all the risks and rewards, it derecognizes if it has lost control (the transferee can sell the assets) or otherwise continues to recognize the assets to the extent of its continuing involvement. ASPE Section 3856 uses a control-based test closer to the older US model.
Worked problem
Factoring without recourse
Northlake factors $400,000 of receivables without recourse. The factor charges a 3 per cent fee and holds back 5 per cent to cover returns and disputes. Record the sale.
Show solution
- Cash received = 400,000 − 3% fee (12,000) − 5% holdback (20,000) = $368,000.
- Record a receivable from the factor for the $20,000 holdback.
- Loss on sale of receivables = the $12,000 fee.
- Derecognize the $400,000 of receivables.
Answer: Debit cash 368,000, due from factor 20,000 and loss on sale 12,000; credit receivables 400,000.
Analysing receivables
Receivables turnover (net credit sales ÷ average net receivables) and days sales outstanding (365 ÷ turnover, or average receivables ÷ sales × 365) show how quickly customers pay. A rising DSO can signal weaker customers, looser credit terms or aggressive revenue recognition: receivables that grow much faster than sales are a warning sign analysts watch for. For Northlake, with sales of $61 million and average receivables of $8.1 million, turnover is about 7.5 and DSO about 48 days. Its stated terms are net 30 for most customers and longer for municipalities, so 48 days is plausible but worth monitoring as the farm economy weakens.
Common mistakes
MistakeRecording revenue at the gross price when customers usually take early-payment discounts.
InsteadTreat expected discounts as variable consideration and record revenue net of them.
MistakeWaiting for a loss event before providing for credit losses under IFRS 9.
InsteadIFRS 9 requires expected credit losses from initial recognition, using forward-looking information.
MistakeRecording credit loss expense when an account is written off.
InsteadThe write-off uses the allowance; expense was recognized when the allowance was established.
MistakeRecording a below-market-rate note at face value.
InsteadRecord it at the present value of its cash flows at the market rate and amortize the discount as interest income.
MistakeTreating every factoring arrangement as a sale.
InsteadApply the derecognition tests; transfers that fail them are secured borrowings.
Summary and key terms
- Restricted cash is reported separately and classified by when the restriction lapses.
- Trade discounts are deducted at the outset; cash discounts are variable consideration.
- IFRS 9 requires expected credit losses: 12-month or lifetime in the general approach, lifetime for trade receivables under the simplified approach.
- ASPE uses an incurred-loss impairment model for receivables.
- Write-offs reduce the receivable and the allowance, not expense; recoveries reverse the write-off.
- Notes receivable are carried at amortized cost with interest income at the effective (market) rate.
- Transfers of receivables are derecognized only if they meet the framework's tests; otherwise they are secured borrowings.
- Simplified approach
- The IFRS 9 requirement to measure the allowance for trade receivables at lifetime expected credit losses.
- Restricted cash
- Cash that is not available for general use because of legal or contractual restrictions.
- Compensating balance
- A minimum deposit a bank requires as part of a borrowing arrangement.
- Trade discount
- A reduction from list price offered to certain customers, recorded as a lower price.
- Cash discount
- A reduction offered for early payment, treated as variable consideration.
- Expected credit loss
- The probability-weighted estimate of credit losses over a specified horizon.
- Provision matrix
- A table of loss rates by ageing category used to estimate the allowance for trade receivables.
- Amortized cost
- Initial amount adjusted for principal repayments and cumulative effective-interest amortization, less the loss allowance.
- Effective interest method
- A method that recognizes interest at a constant rate on the carrying amount.
- Factoring
- Selling receivables to a third party, the factor, for cash.
- Secured borrowing
- A transfer of receivables that does not qualify for derecognition, recorded as a liability.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Is a postdated customer cheque cash?
Show answer
No; it is a receivable until it can be deposited.
Sales of $20,000 on 1/10, net 30; 60 per cent expected to take the discount. Revenue?
Show answer
20,000 − 20,000 × 60% × 1% = $19,880.
Receivables of $500,000 with an expected loss rate of 2 per cent; existing allowance $6,000. Expense?
Show answer
Required allowance $10,000; expense $4,000.
A $3,000 account is written off. Effect on net receivables and expense?
Show answer
None on either; both the receivable and the allowance fall by $3,000.
A written-off $3,000 account is collected. Entries?
Show answer
Reinstate: debit receivable, credit allowance; then debit cash, credit receivable.
Present value of a $50,000 note due in one year with no interest at a 4 per cent market rate?
Show answer
$48,077.
Rerun the note program with a stated rate of 6 per cent. What happens?
Show answer
The note is recorded at face value, $300,000, and there is no discount to amortize.
Factor $200,000 without recourse at a 4 per cent fee, no holdback. Loss and cash?
Show answer
Cash $192,000; loss $8,000.
Under IFRS 9, what happens if the entity retains substantially all risks and rewards in a transfer?
Show answer
It continues to recognize the receivables and records a liability for the proceeds.
Sales $12 million, average receivables $1.5 million. DSO?
Show answer
Turnover 8; DSO about 46 days.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.