
ACCT-211 · Lesson 11 of 12 · 29 min
Impairment of long-lived assets
Depreciation spreads an asset's cost over its life on the assumption that the asset will earn at least that much. Sometimes that assumption fails: a technology becomes obsolete, a market collapses, a regulation bans a product, a plant sits idle. When the carrying amount of an asset is more than the entity can recover from it, the asset is impaired and must be written down. This lesson explains when to test for impairment, how the frameworks measure it and why they can give different answers for the same asset: the IFRS one-step test against recoverable amount, and the two-step test used by US GAAP and, for private enterprises in Canada, by ASPE. It also covers cash-generating units and asset groups, how losses are allocated and when they can be reversed. Goodwill impairment is introduced here and completed in lesson 12.
When to test
IAS 36, Impairment of Assets, requires an entity to assess at the end of each reporting period whether there is any indication that an asset may be impaired, and if there is, to estimate its recoverable amount. Regardless of indicators, goodwill, intangible assets with indefinite useful lives and intangible assets not yet available for use must be tested at least annually. Indicators include external sources (a significant decline in market value, adverse changes in technology, markets, the economy or law, increases in market interest rates that raise discount rates, and the entity's net assets exceeding its market capitalization) and internal sources (obsolescence or physical damage, plans to discontinue or restructure, idle assets, and evidence that economic performance is worse than expected).
ASPE Section 3063 requires a long-lived asset to be tested for recoverability whenever events or changes in circumstances indicate that its carrying amount may not be recoverable, using indicators similar to those above but without a requirement to assess indicators at every reporting date.
The IFRS model: recoverable amount
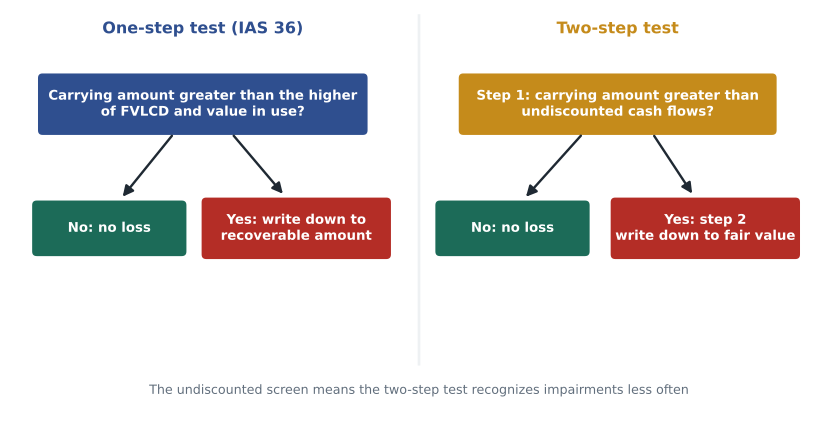
Under IAS 36, an asset is impaired when its carrying amount exceeds its recoverable amount, the higher of fair value less costs of disposal (FVLCD) and value in use (VIU). FVLCD is measured under IFRS 13 (lesson 2) less incremental disposal costs such as legal fees and removal costs. VIU is the present value of the future cash flows expected from continuing use of the asset and its ultimate disposal, based on reasonable and supportable projections (normally no more than five years of detailed budgets, then extrapolated with a steady or declining growth rate), excluding future restructurings not yet committed and improvements not yet made, and discounted at a pre-tax rate reflecting current market assessments of the time value of money and the risks specific to the asset. The impairment loss is the excess of carrying amount over recoverable amount, recognized in profit or loss (or against any revaluation surplus for revalued assets).
ASPE Section 3063 uses the two-step approach also found in US GAAP: first a recoverability test comparing the carrying amount with the undiscounted cash flows expected from use and eventual disposal; if the carrying amount is not recoverable, the impairment loss is the excess of carrying amount over fair value. Because undiscounted cash flows exceed discounted ones, the ASPE recoverability test acts as a cushion: an asset can be worth less than its carrying amount yet pass step 1.
# Same asset, two impairment models (illustrative)
carrying = 1_800_000
annual_cash_flow, years, disposal_value = 330_000, 6, 100_000
rate = 0.10
fair_value, costs_of_disposal = 1_350_000, 50_000

undiscounted = annual_cash_flow * years + disposal_value
viu = sum(annual_cash_flow / (1 + rate) ** t for t in range(1, years + 1)) + disposal_value / (1 + rate) ** years
fvlcd = fair_value - costs_of_disposal
recoverable = max(viu, fvlcd)

print(f"Undiscounted cash flows {undiscounted:,.0f}; value in use {viu:,.0f}; FVLCD {fvlcd:,.0f}")
ifrs_loss = max(0, carrying - recoverable)
print(f"One-step test (IFRS): recoverable {recoverable:,.0f}; impairment {ifrs_loss:,.0f}")
two_step_loss = 0 if undiscounted >= carrying else carrying - fair_value
print(f"Two-step test: recoverable on undiscounted basis? {undiscounted >= carrying}; impairment {two_step_loss:,.0f}")Undiscounted cash flows 2,080,000; value in use 1,493,683; FVLCD 1,300,000 One-step test (IFRS): recoverable 1,493,683; impairment 306,317 Two-step test: recoverable on undiscounted basis? True; impairment 0
Northlake's marine-sensor production line has a carrying amount of $1.8 million. Its undiscounted cash flows ($2.08 million) exceed the carrying amount, so under the two-step test it passes the recoverability screen and no loss is recognized. Under IAS 36 the recoverable amount is the higher of value in use ($1,493,683) and FVLCD ($1,300,000), and the line is written down by about $306,300. The same facts produce an impairment under one framework and none under the other. If cash flows fell further so that the undiscounted total dropped below $1.8 million, the two-step test would measure the loss against fair value ($1,350,000), giving $450,000.
Cash-generating units
Most assets do not generate cash flows independently: a calibration machine contributes to the output of a whole production line. IAS 36 therefore tests at the level of the cash-generating unit (CGU), the smallest identifiable group of assets that generates cash inflows largely independent of the cash inflows from other assets or groups. If an active market exists for the output of a group, it is a CGU even if the output is used internally. Corporate assets (head office, research centre) and goodwill are allocated to CGUs or groups of CGUs on a reasonable and consistent basis. An impairment loss for a CGU is allocated first to reduce the carrying amount of any goodwill allocated to it, then to the other assets pro rata on the basis of their carrying amounts, but no asset is reduced below the highest of its FVLCD, its VIU (if determinable) and zero.
Worked problem
Allocating a CGU impairment
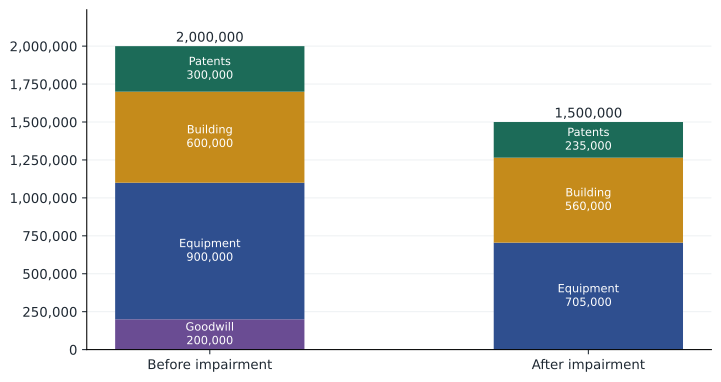
Northlake's marine-sensor CGU has goodwill $200,000, equipment $900,000, building $600,000 and patents $300,000 (total $2,000,000). Its recoverable amount is $1,500,000. The building's FVLCD is $560,000. Allocate the $500,000 impairment.
Show solution
- Goodwill first: reduce by $200,000 to zero; $300,000 remains.
- Pro rata to the other assets (total 1,800,000): equipment 300,000 × 900/1,800 = 150,000; building 100,000; patents 50,000.
- Building limit: 600,000 − 100,000 = 500,000 would be below its FVLCD of 560,000. Reduce the building only by $40,000; reallocate the $60,000 excess to equipment and patents in proportion (900:300): equipment +45,000, patents +15,000.
- Final losses: goodwill 200,000; equipment 195,000; building 40,000; patents 65,000. Total $500,000.
Answer: Goodwill absorbs the loss first; no asset falls below its own recoverable floor.
Reversals
At each reporting date an entity assesses whether there is any indication that an impairment loss recognized in prior periods for an asset other than goodwill may no longer exist or may have decreased. If so, it re-estimates recoverable amount and reverses the loss to the extent of the increase, but the reversed carrying amount cannot exceed what the carrying amount would have been (net of depreciation) had no impairment been recognized. Reversals are recognized in profit or loss (or OCI for revalued assets). Impairment losses on goodwill are never reversed. Under ASPE Section 3063, impairment losses on long-lived assets are not reversed.
Worked problem
Reversal ceiling
Northlake's equipment (cost $1,000,000, 10-year life, no residual) is impaired at the end of year 3: carrying amount $700,000, written down to recoverable amount $490,000 with 7 years remaining. At the end of year 5 recoverable amount rises to $520,000. How much is reversed?
Show solution
- Depreciation after impairment = 490,000 ÷ 7 = $70,000 a year; carrying amount at end of year 5 = 490,000 − 140,000 = $350,000.
- Carrying amount without the impairment at end of year 5 = 1,000,000 − 500,000 = $500,000 (the ceiling).
- Recoverable amount $520,000 exceeds the ceiling, so the reversal is limited to 500,000 − 350,000 = $150,000.
- The equipment returns to $500,000 and is depreciated at $100,000 a year for the remaining 5 years.
Answer: Reverse $150,000, up to the no-impairment carrying amount.
Goodwill and indefinite-life intangibles: a first look
Goodwill is not tested on its own because it does not generate cash flows independently; it is allocated to the CGUs (or groups of CGUs) expected to benefit from the business combination, at the lowest level at which it is monitored for internal management purposes, and no larger than an operating segment. Each such group is tested at least annually, and whenever there is an indication of impairment, by comparing its carrying amount, including goodwill, with its recoverable amount. ASPE Section 3064 tests goodwill only when events or changes in circumstances indicate that the carrying amount of a reporting unit may exceed its fair value. Lesson 12 completes the treatment of goodwill and other intangibles.
Estimating cash flows and discount rates
Whichever framework applies, the quality of an impairment test depends on the cash flow forecast. Forecasts should be based on the most recent budgets approved by management, cover the asset or unit in its current condition, include cash flows from continuing use and from eventual disposal, and exclude financing costs and income taxes (because the discount rate already reflects the cost of capital and, under IAS 36, is pre-tax). Growth beyond the detailed budget period should be steady or declining and should not exceed the long-term average growth rate for the products, industries or country in which the entity operates, unless a higher rate can be justified. Overly optimistic forecasts are the most common weakness auditors and regulators find in impairment tests.
Worked problem
Building a value-in-use discount rate
Northlake estimates a post-tax weighted average cost of capital of 8 per cent for its marine-sensor business, with a 25 per cent tax rate. It needs a pre-tax rate for an IAS 36 value-in-use calculation. A quick approximation divides the post-tax rate by (1 minus the tax rate). What rate results, and why is it only an approximation?
Show solution
- Approximate pre-tax rate = 8% ÷ (1 − 0.25) = 10.7 per cent.
- The approximation ignores the timing of tax cash flows, such as tax depreciation that differs from book depreciation, so IAS 36 practice is to solve iteratively for the pre-tax rate that gives the same value as discounting post-tax cash flows at the post-tax rate.
- Northlake rounds to 10 per cent for the marine-sensor line after that iteration, which is the rate used in this lesson's program.
- Under US GAAP, the fair value measurement in step 2 uses market participant assumptions, so the discount rate reflects what a market participant would require rather than the entity's own cost of capital.
Answer: A pre-tax rate of about 10 per cent; the precise rate comes from iteration, not the simple gross-up.
Disclosure and judgement
Impairment testing is one of the areas of accounting that depends most on judgement. Cash flow forecasts, growth rates, discount rates and the definition of CGUs or asset groups all affect the result, and management has incentives to avoid write-downs (which hit profit) or, occasionally, to take large write-downs in a bad year to make future results look better (a 'big bath'). Standards respond with disclosure: the events that led to the impairment, the amount, the recoverable amount or fair value and how it was measured, the key assumptions, and, under IFRS, sensitivity analysis when a reasonably possible change in a key assumption would cause an impairment. Auditors treat impairment as a key audit matter or critical audit matter in many audit reports.
Common mistakes
MistakeTesting PP&E for impairment only when the annual audit is near.
InsteadUnder IAS 36, assess indicators at every reporting date; test whenever an indicator exists.
MistakeUsing undiscounted cash flows to measure an impairment loss.
InsteadUndiscounted cash flows are only the recoverability screen in the two-step test; the loss is measured against fair value (or recoverable amount under IFRS).
MistakeAllocating a CGU impairment to assets pro rata before reducing goodwill.
InsteadUnder IAS 36, goodwill absorbs the loss first, then other assets pro rata, subject to individual floors.
MistakeReversing a goodwill impairment when the CGU recovers.
InsteadGoodwill impairments are never reversed.
MistakeIncluding planned future restructurings in value in use.
InsteadValue in use reflects the asset in its current condition; uncommitted restructurings and improvements are excluded.
Summary and key terms
- IAS 36 requires indicators to be assessed every reporting date; goodwill and indefinite-life intangibles are tested annually.
- IFRS impairment: carrying amount versus recoverable amount (higher of FVLCD and value in use).
- ASPE uses a two-step test: undiscounted recoverability, then measurement at fair value.
- Value in use discounts expected cash flows from the asset in its current condition at a pre-tax market-based rate.
- Losses are tested and allocated by cash-generating unit, with goodwill reduced first.
- IFRS requires reversals (except goodwill) up to the no-impairment carrying amount; ASPE prohibits them.
- Impairment depends heavily on judgement and is heavily disclosed.
- Cash-generating unit
- The smallest identifiable group of assets generating largely independent cash inflows.
- Corporate asset
- An asset such as a head office that contributes to several CGUs and is allocated to them for testing.
- Impairment loss
- The amount by which an asset's carrying amount exceeds its recoverable amount (IFRS) or fair value after failing recoverability (two-step models).
- Recoverable amount
- Under IAS 36, the higher of fair value less costs of disposal and value in use.
- Value in use
- The present value of future cash flows expected from an asset or CGU in its current condition.
- Fair value less costs of disposal
- Fair value minus incremental costs directly attributable to disposal.
- Recoverability test
- A comparison of carrying amount with undiscounted future cash flows (ASPE and US GAAP).
- Indicator of impairment
- An internal or external sign that an asset may be impaired.
- Big bath
- Taking unusually large write-downs in a bad period to improve later reported results.
- Reversal of impairment
- An increase in carrying amount when recoverable amount recovers, limited to the no-impairment amount (IFRS, not goodwill).
Practice problems
Work each problem on paper first, then reveal the answer to check.
Name three external indicators of impairment.
Show answer
Falling market value; adverse technological, market, economic or legal changes; rising interest rates; net assets exceeding market capitalization.
Carrying amount $500,000; FVLCD $420,000; value in use $460,000. IFRS impairment?
Show answer
Recoverable amount $460,000; loss $40,000.
Same asset: undiscounted cash flows $560,000, fair value $430,000. Two-step impairment?
Show answer
None: it passes the recoverability test.
If undiscounted cash flows were $480,000 in the previous question?
Show answer
It fails step 1; loss = 500,000 − 430,000 = $70,000.
Why is value in use discounted at a pre-tax rate?
Show answer
Because the cash flows are pre-tax, the rate must be consistent with them.
A CGU with goodwill $50,000 and other assets $450,000 has a recoverable amount of $420,000. How much goodwill remains?
Show answer
None: the $80,000 loss eliminates goodwill and reduces other assets by $30,000.
Can an impairment of goodwill be reversed under IFRS?
Show answer
No.
Under ASPE, can an impairment of equipment be reversed?
Show answer
No.
What is a big bath, and why does it concern users?
Show answer
Excessive write-downs in a bad year to flatter future results; it distorts trends.
Rerun the impairment program with annual cash flows of $280,000. What happens under each model?
Show answer
Undiscounted 1,780,000 < 1,800,000, so the two-step test measures a $450,000 loss; under IFRS VIU falls to about $1,276,000, recoverable amount is FVLCD $1,300,000, loss $500,000.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.