
ACCT-211 · Lesson 1 of 12 · 29 min
The reporting environment: IFRS, ASPE and the conceptual framework
ACCT-101 taught the accounting cycle: how transactions become journal entries, how entries become a trial balance and how a trial balance becomes four financial statements. Intermediate accounting asks harder questions. When exactly has revenue been earned on a contract that bundles equipment, installation and three years of monitoring? At what amount should a receivable sit on the balance sheet when some customers will not pay? When does a cost become an asset rather than an expense, and when must an asset be written down? Answering those questions requires the standards themselves, and in Canada there are two sets of them: International Financial Reporting Standards (IFRS) for publicly accountable enterprises and Accounting Standards for Private Enterprises (ASPE) for most private companies. This course works through the asset side of the balance sheet under both, flagging where they differ. ACCT-212 continues with liabilities, leases, income taxes, pensions and equity. Nothing in this course is professional advice; real reporting decisions belong with qualified accountants applying the full standards.
Throughout the course one invented company provides the numbers. Northlake Instruments makes precision weather and air-quality sensors for municipalities, airports and farms. It sells sensor stations, installs them, and sells multi-year monitoring subscriptions that stream data to a dashboard. It also holds inventory of parts and finished stations, owns a factory and a fleet of service vans, capitalizes some development costs and once bought a smaller competitor. Every lesson uses Northlake to show how a standard turns a business event into numbers on the statements. All Northlake figures are illustrative.
Why financial reporting needs standards
Financial statements are prepared by management but used mainly by outsiders: investors deciding whether to buy or sell shares, lenders deciding whether to lend and on what terms, suppliers deciding whether to extend credit, and employees, regulators and the public. Outsiders cannot demand custom reports, and they cannot inspect the books themselves. Standards solve that problem by fixing the rules in advance, so statements prepared by different companies, in different years, can be compared and relied on. Without standards, each management team would be tempted to choose the methods that flatter its own results, and every set of statements would need to be reverse-engineered before it could be used.
Standards also reduce the cost of capital. When investors trust the numbers, they demand a smaller premium for uncertainty, and companies can raise money more cheaply. That is why stock exchanges and securities regulators require audited statements prepared under a recognized framework, and why lenders write covenants in terms of ratios computed from those statements. Accounting choices therefore have real consequences: a change in how revenue is recognized can move a covenant ratio, an executive bonus or a share price, which is exactly why the standards are detailed and why auditors check them.
Who sets the rules in Canada
In Canada, the Accounting Standards Board (AcSB), an independent body overseen by the Accounting Standards Oversight Council and supported by the Financial Reporting & Assurance Standards Canada organization, sets standards for private enterprises, not-for-profit organizations and pension plans, and adopts IFRS for publicly accountable enterprises. Its standards are published in the CPA Canada Handbook – Accounting, which has several parts. Part I is IFRS as issued by the International Accounting Standards Board (IASB), adopted without modification and required for publicly accountable enterprises (essentially companies with publicly traded debt or equity and entities such as banks and insurers that hold assets in a fiduciary capacity) since 2011. Part II is ASPE, a simpler, made-in-Canada set of standards that private enterprises may use instead of IFRS. Part III covers not-for-profit organizations and Part IV pension plans. Public sector entities follow separate standards set by the Public Sector Accounting Board.
A private company in Canada can choose IFRS instead of ASPE, and some do, usually because they plan to go public, have foreign owners who report under IFRS or have lenders who ask for it. A company listed in both Canada and the United States may be permitted to file statements prepared under US GAAP with Canadian securities regulators; several large cross-listed Canadian companies do so. This course concentrates on IFRS and ASPE and mentions US GAAP where a Canadian accountant is likely to meet it.
| Feature | IFRS (Part I) | ASPE (Part II) |
|---|---|---|
| Required for | Publicly accountable enterprises | Optional for private enterprises |
| Set by | IASB, adopted by the AcSB without change | AcSB |
| Length and detail | Extensive, with many disclosures | Shorter, fewer disclosures |
| Revaluation of property, plant and equipment | Permitted (revaluation model) | Not permitted |
| Development costs | Capitalized when criteria are met | Policy choice: capitalize when criteria met, or expense |
| Impairment of long-lived assets | One-step test; reversals allowed | Two-step test; no reversals |
| Investment property | Fair value or cost model | Cost only |
| Credit losses on receivables | Expected credit loss model (IFRS 9) | Incurred-loss style allowance |
The conceptual framework
Standards cannot anticipate every transaction, so both the IASB and the AcSB publish a conceptual framework: a statement of the objective of financial reporting and the concepts that underlie the standards. The IASB's current Conceptual Framework for Financial Reporting was issued in 2018. It is not itself a standard and does not override one, but the IASB uses it when writing standards, and preparers use it to develop accounting policies when no standard applies (IAS 8 directs them there). ASPE has its own framework in Section 1000, Financial Statement Concepts, which is broadly consistent but older and simpler.
The framework begins with the objective. General-purpose financial reports exist to provide financial information about the reporting entity that is useful to existing and potential investors, lenders and other creditors in making decisions about providing resources to the entity. Those users need to assess the amount, timing and uncertainty of future cash flows, and management's stewardship of the entity's resources. Everything else follows from this decision-usefulness objective: which items are recognized, how they are measured and what is disclosed.
Qualitative characteristics
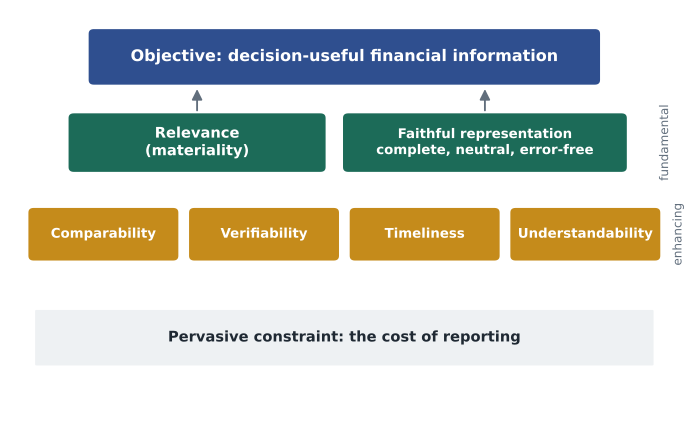
Information is useful if it is relevant and faithfully represents what it purports to represent. These are the two fundamental qualitative characteristics. Relevant information can make a difference to decisions because it has predictive value, confirmatory value or both. Materiality is an entity-specific aspect of relevance: information is material if omitting, misstating or obscuring it could reasonably be expected to influence users' decisions. There is no universal percentage threshold, although auditors often start from rules of thumb such as five per cent of pre-tax income, then adjust for qualitative factors such as whether a misstatement turns a loss into a profit or breaches a covenant.
Faithful representation means the information is complete (it includes everything needed to understand the item), neutral (it is not slanted to produce a desired result) and free from error (not perfectly accurate, but with no errors in the description or the process used). Neutrality is supported by prudence, the exercise of caution when making judgements under uncertainty, which the 2018 IASB framework reintroduced. Prudence does not permit deliberately understating assets or overstating liabilities; it means not overstating assets or income and not understating liabilities or expenses.
Four enhancing characteristics make relevant, faithfully represented information more useful: comparability (users can identify similarities and differences between entities and over time, helped by consistent methods), verifiability (different knowledgeable observers could reach consensus that the depiction is faithful), timeliness (information arrives in time to influence decisions) and understandability (information is classified and presented clearly for users who have a reasonable knowledge of business and review it diligently). The pervasive constraint is cost: the benefits of reporting information should justify the costs of providing and using it. Cost is the reason ASPE and the PCC alternatives exist.
Elements, recognition and measurement
The 2018 IASB framework defines an asset as a present economic resource controlled by the entity as a result of past events, where an economic resource is a right that has the potential to produce economic benefits. A liability is a present obligation of the entity to transfer an economic resource as a result of past events. Equity is the residual interest in the assets after deducting liabilities. Income is increases in assets or decreases in liabilities that increase equity, other than contributions from owners; expenses are the reverse, other than distributions to owners. The definitions centre on rights and obligations, which is why the asset chapters of this course keep asking: does the company control a right that can produce benefits?
Meeting a definition is necessary but not sufficient for recognition. An item is recognized (included in the statements) when doing so provides relevant information and a faithful representation, considering uncertainty about existence, a low probability of benefits and the degree of measurement uncertainty. Measurement then assigns an amount. The frameworks describe two broad families of measurement basis. Historical cost measures an asset at the cost incurred to acquire it, adjusted for consumption (depreciation) and impairment; amortized cost for receivables is a form of historical cost. Current value measures include fair value (the price that would be received to sell an asset in an orderly transaction between market participants), value in use for assets (the present value of cash flows from using and disposing of the asset) and current cost. Lesson 2 examines fair value in detail.
Worked problem
Is it an asset?
Northlake (a) signs a contract to buy a machine next year for $400,000; (b) pays a $50,000 non-refundable deposit on that machine; (c) employs a team of skilled engineers; (d) holds a three-year exclusive licence to a patented sensor coating. Which are assets?
Show solution
- (a) A signed purchase commitment, with no payment and no delivery, is an executory contract: neither party has performed. It is generally not recognized (although a loss on an onerous commitment may be).
- (b) The deposit is a present right (to receive the machine or the deposit's benefit) arising from a past event (the payment). It is an asset: a prepayment or deposit on equipment.
- (c) The engineers create value, but Northlake does not control them as a resource that can be recognized; they can leave. The workforce is not recognized as an asset.
- (d) The licence is a present right, controlled through the contract, with the potential to produce benefits. It is an intangible asset, measured at cost.
Answer: Only (b) and (d) are recognized as assets; (a) is disclosed if material, and (c) is not recognized.
Underlying assumptions and the accounting policies note
Two assumptions run through the statements. The going concern assumption says the entity will continue operating for the foreseeable future, at least twelve months from the reporting date; if management intends to liquidate or has no realistic alternative, the statements are prepared on another basis, and material uncertainties about going concern must be disclosed. The accrual basis, covered in ACCT-101, records the effects of transactions when they occur rather than when cash moves. Monetary unit and periodicity assumptions (stable currency, artificial periods such as quarters and years) are also implicit.
Because standards allow choices and require estimates, the notes must disclose significant accounting policies and the judgements and estimation uncertainty that most affect the amounts. Under IAS 8, an entity selects policies consistently, changes a policy only if a standard requires it or the change produces more relevant and reliable information, and applies policy changes retrospectively. Changes in estimates, such as a revised useful life, are applied prospectively. Errors in prior periods are corrected retrospectively by restating comparatives. ASPE Section 1506 has similar rules. These distinctions matter throughout the course: switching from FIFO to weighted average is a policy change; revising the expected life of a van is an estimate change.
# Materiality screen: a common starting point, not a rule (illustrative)
pretax_income = 4_200_000
revenue = 61_000_000
total_assets = 48_500_000

benchmarks = {
    "5% of pre-tax income": 0.05 * pretax_income,
    "0.5% of revenue": 0.005 * revenue,
    "1% of total assets": 0.01 * total_assets,
}
for name, amount in benchmarks.items():
    print(f"{name:<22} {amount:>12,.0f}")

misstatement = 180_000
lowest = min(benchmarks.values())
print(f"Misstatement {misstatement:,} vs lowest benchmark {lowest:,.0f}:",
      "below" if misstatement < lowest else "at or above")
# Qualitative factors can still make a small amount material:
covenant_min_income = 4_100_000
print("Would correcting it breach the income covenant?",
pretax_income - misstatement < covenant_min_income)5% of pre-tax income 210,000 0.5% of revenue 305,000 1% of total assets 485,000 Misstatement 180,000 vs lowest benchmark 210,000: below Would correcting it breach the income covenant? True
The output shows why materiality is judgement, not arithmetic. The $180,000 misstatement is below every quantitative benchmark, yet correcting it would push Northlake's pre-tax income below a loan covenant minimum. That qualitative factor makes it material: a lender would certainly want to know.
Canadian and international context
The IASB is based in London and its standards are used in more than 140 jurisdictions. Canada has a voice through the AcSB, which comments on IASB proposals and runs outreach. When the IASB issues a new standard, the AcSB incorporates it into Part I after due process; IFRS 18, Presentation and Disclosure in Financial Statements, issued in 2024, was incorporated and takes effect for annual periods beginning on or after 1 January 2027 (covered in lesson 2). The AcSB also maintains ASPE, amending it periodically, for example with a revenue section (3400) revised to align more closely with the principles of IFRS 15 while staying simpler. In 2024 the International Sustainability Standards Board's standards prompted the Canadian Sustainability Standards Board to issue Canadian versions, which sit alongside, not inside, the accounting standards.
Ethics and the reporting chain
Reliable reporting depends on people as much as rules. Management prepares the statements and is responsible for internal control; the board's audit committee oversees reporting and the auditor; the external auditor, a licensed public accountant, expresses an opinion on whether the statements present fairly in accordance with the framework. Canadian securities regulators require chief executive and chief financial officers of reporting issuers to certify the annual and interim filings and the design of internal control (National Instrument 52-109). CPA members are bound by their provincial body's code of professional conduct, which requires integrity, objectivity and due care. Lesson 12 returns to earnings management and Canadian cases such as Nortel Networks and Sino-Forest, where the reporting chain failed.
Common mistakes
MistakeTreating the conceptual framework as a standard that overrides IFRS.
InsteadThe framework guides standard setting and policy choice where no standard applies; a specific IFRS always takes precedence.
MistakeApplying a fixed percentage as the definition of materiality.
InsteadUse quantitative benchmarks only as a starting point and consider qualitative factors such as covenants, trends and fraud.
MistakeEquating prudence with deliberately understating assets.
InsteadPrudence means caution under uncertainty; deliberate understatement breaches neutrality and faithful representation.
MistakeRecording a signed but unperformed purchase contract as an asset and liability.
InsteadExecutory contracts are generally not recognized until one party performs; disclose material commitments.
MistakeApplying a change in useful life retrospectively.
InsteadChanges in estimates are applied prospectively; only policy changes and error corrections are applied retrospectively.
Summary and key terms
- In Canada, publicly accountable enterprises use IFRS (Part I of the Handbook) and most private enterprises may use ASPE (Part II).
- The objective of financial reporting is to provide information useful to investors, lenders and other creditors in making resource-allocation decisions.
- Relevance and faithful representation are the fundamental qualitative characteristics; comparability, verifiability, timeliness and understandability enhance them.
- Materiality is entity-specific and a matter of judgement; quantitative benchmarks are a starting point only.
- Assets are present rights or economic resources controlled by the entity as a result of past events; recognition also requires relevant, faithfully representative information.
- Measurement bases include historical cost and current values such as fair value and value in use.
- Policy changes and error corrections are retrospective; estimate changes are prospective.
- IFRS
- International Financial Reporting Standards issued by the IASB; Part I of the CPA Canada Handbook.
- ASPE
- Accounting Standards for Private Enterprises; Part II of the CPA Canada Handbook.
- Publicly accountable enterprise
- An entity with publicly traded debt or equity, or one that holds assets in a fiduciary capacity for outsiders.
- Conceptual framework
- A statement of the objective and concepts that underlie financial reporting standards.
- Relevance
- The capacity of information to make a difference to decisions through predictive or confirmatory value.
- Faithful representation
- Depiction that is complete, neutral and free from error.
- Materiality
- The quality of information whose omission or misstatement could reasonably influence users' decisions.
- Prudence
- Caution in making judgements under uncertainty, without deliberate bias.
- Going concern
- The assumption that the entity will continue operating for the foreseeable future.
- Change in estimate
- A revision of an estimate based on new information, applied prospectively.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Which part of the CPA Canada Handbook must a TSX-listed company follow?
Show answer
Part I, IFRS.
Give two reasons a private Canadian company might choose IFRS over ASPE.
Show answer
Plans to go public; foreign parent reporting under IFRS; lender requirements.
Name the two fundamental qualitative characteristics.
Show answer
Relevance and faithful representation.
Is an engineering team an asset? Explain.
Show answer
No; the entity does not control the employees as a recognizable resource.
A $90,000 error is 2 per cent of pre-tax income but turns a small profit into a loss. Is it material?
Show answer
Probably yes: qualitative factors such as changing a profit to a loss make it material.
Northlake extends a van's useful life from 5 to 7 years. Retrospective or prospective?
Show answer
Prospective: it is a change in estimate.
What does the going concern assumption require management to assess?
Show answer
Whether the entity can continue operating for at least twelve months, and to disclose material uncertainties.
Define fair value.
Show answer
The price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date.
Why do standards reduce the cost of capital?
Show answer
Investors trust comparable, audited numbers and demand a smaller risk premium.
Rerun the materiality program with a covenant minimum of 3,900,000. Is the misstatement still material on that ground?
Show answer
No; 4,200,000 − 180,000 = 4,020,000, which is above 3,900,000, so the covenant test is not breached.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.