
ACCT-470 · Lesson 11 of 12 · 26 min
Income taxes, provisions and climate-related matters
Income taxes and provisions have one thing in common: both require an entity to estimate obligations whose amount and timing depend on future events, often decided by someone else, such as a tax authority or a court. ACCT-212 covered the mechanics of current and deferred tax, losses and valuation, uncertain tax positions and provisions. This lesson takes four harder situations from Tamarind Bay's 2026 year end: deferred tax arising in a business combination, an uncertain transfer pricing position, the global minimum tax, and a product recall with an associated consumer claim. It ends with climate-related matters, which affect several estimates at once.
Deferred tax in a business combination
When Tamarind Bay acquired Greenfold in 2025, it bought the stock, so the tax bases of Greenfold's assets did not change. In the purchase price allocation, however, the brand and customer relationships were recognized at their fair values of 28.0 and 12.0 million, while their tax bases were zero. ASC 740 requires deferred taxes to be recognized on these temporary differences as part of the acquisition accounting, so a deferred tax liability of 10.0 million at the combined 25 percent rate reduces the identifiable net assets and increases goodwill by the same amount. No deferred tax liability is recognized for goodwill that is not deductible for tax purposes. If goodwill were deductible, as in an asset purchase or a Section 338 election, tax goodwill in excess of book goodwill would give rise to a deferred tax asset, measured with a simultaneous equation.
# Income tax judgments at Tamarind Bay Foods (ASC 740; invented figures, millions).
rate = 0.25
# 1. Deferred tax in the 2025 acquisition of Greenfold Plant Kitchen (stock purchase).
consideration = 96.0 + 12.0            # cash plus fair value of the earn-out at acquisition
assets = {"Working capital": (9.0, 9.0), "Property, plant and equipment": (15.0, 15.0),
          "Brand": (28.0, 0.0), "Customer relationships": (12.0, 0.0)}   # (fair value, tax basis)
dtl = sum(max(0.0, fv - tb) for fv, tb in assets.values()) * rate
net = sum(fv for fv, _ in assets.values()) - dtl
print(f"Deferred tax liability on intangibles: {dtl:.2f}")
print(f"Net identifiable assets: {net:.2f}   Goodwill: {consideration - net:.2f}")
print("No deferred tax liability is recognized for goodwill that is not tax deductible.")
# 2. Uncertain tax position: a transfer pricing position worth 8.0 of tax.
outcomes = [(8.0, 0.40), (5.0, 0.35), (0.0, 0.25)]   # (benefit sustained, probability)
p_some = sum(p for b, p in outcomes if b > 0)
print(f"\nStep 1 - recognition: probability that some benefit is sustained = {p_some:.0%}",
      "(more likely than not)" if p_some > 0.5 else "(not recognized)")
cum = 0.0
for b, p in sorted(outcomes, reverse=True):
    cum += p
    print(f"  benefit {b:>4.1f}: cumulative probability {cum:.0%}")
    if cum > 0.5:
        print(f"Step 2 - measurement: largest amount above 50% cumulative = {b:.2f}")
        print(f"Unrecognized tax benefit (liability): {8.0 - b:.2f}")
breakDeferred tax liability on intangibles: 10.00 Net identifiable assets: 54.00 Goodwill: 54.00 No deferred tax liability is recognized for goodwill that is not tax deductible. Step 1 - recognition: probability that some benefit is sustained = 75% (more likely than not) benefit 8.0: cumulative probability 40% benefit 5.0: cumulative probability 75% Step 2 - measurement: largest amount above 50% cumulative = 5.00 Unrecognized tax benefit (liability): 3.00
As the brand and customer relationships are amortized for accounting purposes (the brand is assessed as having an indefinite life, the customer relationships are amortized over eight years), the deferred tax liability on the customer relationships unwinds through deferred tax income, keeping the effective tax rate close to the statutory rate. The indefinite-lived brand's deferred tax liability remains until the brand is impaired or sold, a so-called naked credit that cannot be used to support recognition of deferred tax assets that reverse within a definite period. These details matter because errors in purchase price allocation tax accounting are a recurring source of restatements.
An uncertain transfer pricing position
Tamarind Bay's Mexican brand license from lesson 4 is held by a group company in a lower-tax jurisdiction that charges the US parent a fee for brand management services. The IRS could challenge the fee under Section 482 as excessive, which would increase US taxable income. The total tax at stake is 8.0 million. ASC 740-10 uses a two-step approach. First, recognition: a tax position is recognized only if it is more likely than not to be sustained on examination, based on its technical merits, assuming the authority has full knowledge. Second, measurement: the benefit recognized is the largest amount that is more than 50 percent likely to be realized on ultimate settlement, using cumulative probabilities. The position passes recognition, and the largest amount with a cumulative probability above 50 percent is 5.0 million, so 3.0 million is an unrecognized tax benefit, recorded as a liability. Under IFRIC 23 the same facts would give a liability of 3.05 million using the expected value, a small difference in this case but potentially large in others.
Both frameworks require interest and penalties to be considered: Tamarind Bay accrues interest on the uncertain liability and, as permitted, classifies it within income tax expense, a policy that must be applied consistently and disclosed. Uncertain tax liabilities are reassessed each period as audits progress, statutes of limitation expire and case law develops, and the reassessment is a change in estimate. Regulators also expect disclosure of the judgments made and, where significant, of the possible range of outcomes.
Pillar Two: the global minimum tax
Tamarind Bay's consolidated revenue exceeds 750 million euros, so its foreign subsidiaries are within the scope of the OECD's Pillar Two model rules where those countries have enacted them. The United States has not enacted Pillar Two; instead, the global intangible low-taxed income regime, renamed net CFC tested income by the 2025 tax law, taxes certain foreign earnings at a minimum rate. In January 2026 the OECD Inclusive Framework agreed a side-by-side arrangement under which US-parented groups are, broadly, not subject to the income inclusion and undertaxed profits rules of other countries, though qualified domestic minimum top-up taxes still apply; the details continue to evolve. Under ASC 740, a domestic minimum top-up tax or similar tax is generally treated as an alternative minimum tax, a period cost recognized as current tax, without deferred taxes for the expected future effect. For comparison, IAS 12 was amended in May 2023 to introduce a mandatory temporary exception from deferred tax accounting for Pillar Two, with specific disclosures.
Tamarind Bay's tax note changed significantly in 2025 with ASU 2023-09, Improvements to Income Tax Disclosures, effective for public business entities for annual periods beginning after December 15, 2024. The rate reconciliation must now be presented in a table using specified categories, such as state and local taxes, foreign tax effects, effects of changes in tax laws, cross-border tax laws, tax credits, valuation allowances, nontaxable or nondeductible items and changes in unrecognized tax benefits, with separate disclosure of items at or above 5 percent of the statutory tax, and income taxes paid must be disaggregated by federal, state and foreign jurisdiction, with individual jurisdictions at or above 5 percent of total taxes paid shown separately.
The product recall provision
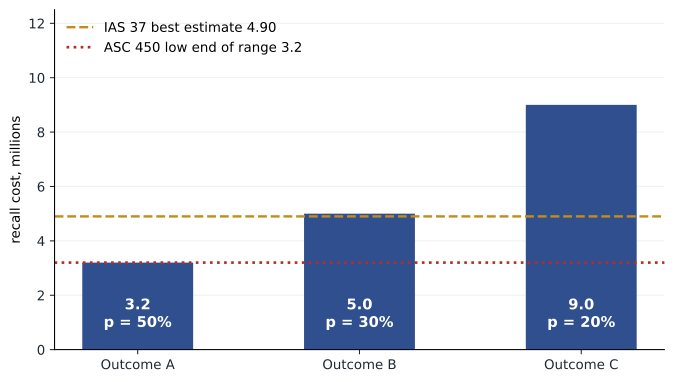
In October 2026 Tamarind Bay recalled several lots of frozen meals after a supplier's ingredient tested positive for listeria. No illnesses were confirmed by year end, but the recall involved retrieving products from retailers, destroying inventory, compensating retailers and consumers, and investigating the cause. At December 31 the company estimated the remaining costs at 3.2, 5.0 or 9.0 million, with probabilities of 50, 30 and 20 percent. A consumer class action alleging distress and economic loss has also been filed; counsel estimates the probability of an unfavorable outcome at 30 percent.
# Product recall provision and a consumer claim, December 31, 2026 (invented, millions).
scen = [(3.2, 0.50), (5.0, 0.30), (9.0, 0.20)]     # total recall cost, probability
ev = sum(c * p for c, p in scen)
ml = max(scen, key=lambda s: s[1])[0]
print(f"Most likely outcome: {ml:.2f}   Expected value: {ev:.2f}")
# Payments: 60% in 2027, 40% in 2028; discount rate 4.0% (pre-tax, risk-free plus adjustment)
paid = [(1, 0.6), (2, 0.4)]
def pv(amount): return sum(amount * w / 1.04 ** t for t, w in paid)
print("\nIAS 37 (single obligation; other outcomes are mostly higher, so a higher estimate is used)")
best = ev
print(f"  best estimate {best:.2f}, discounted {pv(best):.2f}; unwinding in 2027 {pv(best) * 0.04:.2f}")
print("ASC 450 (probable and reasonably estimable; no amount in the range is a better estimate)")
print(f"  accrue the low end of the range {min(c for c, _ in scen):.2f}, usually undiscounted;")
print(f"  disclose the reasonably possible additional loss of up to {max(c for c, _ in scen) - min(c for c, _ in scen):.2f}")
claim_p = 0.30
print(f"\nConsumer class action, probability of loss {claim_p:.0%}:")
print("  IAS 37 - not probable (more likely than not): disclose a contingent liability, no provision")
print(" ASC 450 - reasonably possible: disclose the nature and an estimate or range, no accrual")Most likely outcome: 3.20 Expected value: 4.90 IAS 37 (single obligation; other outcomes are mostly higher, so a higher estimate is used) best estimate 4.90, discounted 4.64; unwinding in 2027 0.19 ASC 450 (probable and reasonably estimable; no amount in the range is a better estimate) accrue the low end of the range 3.20, usually undiscounted; disclose the reasonably possible additional loss of up to 5.80 Consumer class action, probability of loss 30%: IAS 37 - not probable (more likely than not): disclose a contingent liability, no provision ASC 450 - reasonably possible: disclose the nature and an estimate or range, no accrual
ASC 450 requires accrual of a loss contingency when it is probable, meaning likely to occur, that a liability has been incurred and the amount can be reasonably estimated. Probable in US GAAP is a higher threshold than in IFRS, where it means more likely than not. The recall liability meets the threshold. The amount is the best estimate within a range; if no amount within the range is a better estimate than any other, ASC 450 requires the minimum of the range to be accrued, here 3.2 million, with disclosure of the reasonably possible additional loss of up to 5.8 million. Loss contingencies are generally not discounted unless the amount and timing of payments are fixed or reliably determinable. Under IAS 37, by contrast, a Canadian competitor would provide 4.90 million, the expected value, discounted to 4.64 million, because the outcomes above the most likely amount are substantial; IFRS also uses the midpoint when a continuous range is equally likely.
The class action is treated differently. Under both frameworks, a loss that is not probable is not recognized, but it must be disclosed unless the possibility of an outflow is remote. IAS 37 calls this a contingent liability and requires a description, an estimate of its financial effect, the uncertainties and any possibility of reimbursement; ASC 450 requires disclosure of the nature of a reasonably possible loss and an estimate of the possible loss or range, or a statement that an estimate cannot be made. Companies often argue that disclosure would prejudice their position in litigation. IAS 37 permits omitting some information in extremely rare cases where disclosure would seriously prejudice the entity's position, with disclosure of the general nature of the dispute and the reason; US GAAP has no equivalent exemption, though SEC registrants commonly say that an estimate cannot be made, which the SEC staff often challenges.
| Issue | IAS 37 | ASC 450 |
|---|---|---|
| Recognition threshold | Probable = more likely than not | Probable = likely, a higher threshold |
| Measurement | Best estimate; expected value for large populations | Best estimate in range; minimum if none better |
| Range with equal likelihood | Midpoint | Low end |
| Discounting | Required if material | Generally not, unless timing and amount are fixed |
| Constructive obligations | Recognized | Generally recognized only if legally enforceable or specific guidance applies |
| Prejudicial disclosure exemption | Available in extremely rare cases | None |
The IASB has a project to make targeted improvements to IAS 37, including the discount rate, which should reflect non-performance risk under its proposals; no effective date has been set. US GAAP has no equivalent active project.
Climate-related matters in the financial statements
Tamarind Bay has announced a target of halving its operational greenhouse gas emissions by 2035 from a 2022 baseline and reaching net zero by 2050. Do these commitments create liabilities or affect amounts in the statements? Under US GAAP, a voluntary public commitment generally does not create a liability until there is an obligation, such as under emissions regulation or a contract. But climate matters affect many estimates: useful lives, impairment cash flows, credit losses, fair values, asset retirement obligations and inventory measurement. The SEC adopted climate disclosure rules in March 2024, stayed them pending litigation and in March 2025 voted to end its defense of them, so as of 2026 there is no federal climate disclosure requirement in effect; California's laws apply to large companies doing business there, as ACCT-421 discusses. The SEC's 2010 interpretive guidance on climate change disclosure remains in place, and the staff continues to comment on inconsistencies between voluntary sustainability reports and the risk factors and MD&A in filings. For comparison, the IASB published illustrative examples in November 2025 showing how IFRS requirements apply to disclosures about climate-related and other uncertainties.
For Tamarind Bay, the most significant effect is on the Frozen unit: the replacement of ammonia refrigeration and gas boilers is brought forward, shortening the useful lives of the existing equipment and increasing depreciation by about 1.8 million a year from 2026, a change in estimate applied prospectively. The impairment test in lesson 6 includes the replacement costs required by enacted regulation. The financial statements disclose these judgments, and the chief financial officer checks that the numbers in the sustainability report, such as the cost of the transition plan, are consistent with those in the impairment model.
Common mistakes
MistakeIgnoring deferred tax on intangible assets recognized in a share acquisition.
InsteadRecognize deferred tax on the difference between fair values and tax bases, which increases goodwill.
MistakeMeasuring an uncertain tax benefit at its expected value.
InsteadApply the two steps: more-likely-than-not recognition, then the largest amount above 50 percent cumulative probability.
MistakeAssuming the United States has enacted Pillar Two.
InsteadThe United States has not; foreign minimum taxes still apply to US groups, subject to the side-by-side arrangement.
MistakeAccruing the expected value when no amount in the range is better.
InsteadAccrue the minimum of the range and disclose the reasonably possible additional loss.
MistakeTreating a net-zero pledge as a provision.
InsteadA pledge alone is not an obligation, but climate matters affect estimates such as useful lives and impairment.
MistakeOmitting contingent liability disclosure because the case might be lost.
InsteadDisclose unless the possibility of outflow is remote, within the limited exemptions available.
Summary and key terms
- Deferred tax on intangibles recognized in a business combination increases goodwill; no deferred tax arises on non-deductible goodwill.
- ASC 740 uses more-likely-than-not recognition and largest-amount-above-50-per-cent measurement.
- The United States has not enacted Pillar Two; ASU 2023-09 expanded the rate reconciliation and taxes paid disclosures from 2025.
- ASC 450 accrues probable (likely) losses at the best estimate or the minimum of the range, generally undiscounted.
- Contingent liabilities are disclosed unless remote.
- Climate commitments rarely create provisions on their own but affect many estimates and must be consistent with sustainability reporting.
- Unrecognized tax benefit
- The difference between a tax position taken in a return and the benefit recognized under ASC 740.
- ASU 2023-09
- The FASB update expanding income tax disclosures, effective 2025 for public business entities.
- Loss contingency
- An existing condition involving uncertainty about a possible loss that will be resolved by future events.
- Temporary difference
- A difference between the carrying amount of an asset or liability and its tax base.
- Pillar Two
- The OECD model rules for a 15 percent global minimum tax on large multinational groups.
- Top-up tax
- Additional tax payable to bring a jurisdiction's effective tax rate up to the minimum rate.
- Constructive obligation
- An obligation arising from an entity's actions that create a valid expectation it will discharge responsibilities.
- Contingent liability
- A possible obligation, or a present obligation not recognized, that is disclosed unless remote.
- Transfer pricing
- The pricing of transactions between related entities in different tax jurisdictions.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Why does the deferred tax liability on Greenfold's intangibles increase goodwill?
Show answer
It reduces the identifiable net assets acquired, so the residual goodwill is larger.
Rerun the tax program with a rate of 26.5 percent. What is goodwill?
Show answer
Deferred tax 10.60, net assets 53.40, goodwill 54.60.
Why is no deferred tax recognized on goodwill?
Show answer
Recognizing it would increase goodwill, which would require more deferred tax, a circular result; the standards prohibit it.
Change the probabilities to 60, 20 and 20 percent. What benefit is recognized?
Show answer
8.0, because its cumulative probability of 60 percent exceeds 50 percent; no unrecognized benefit.
How is Pillar Two top-up tax presented?
Show answer
Generally as current tax, like an alternative minimum tax, for foreign minimum taxes that apply.
Why does the recall create an obligation at year end?
Show answer
The public recall announcement created a constructive or legal obligation to compensate retailers and consumers for a past event.
Rerun the provision program with outcomes of 4.0, 5.0 and 6.0. What are the most likely outcome and expected value?
Show answer
Most likely 4.0; expected value 4.0 × 0.5 + 5.0 × 0.3 + 6.0 × 0.2 = 4.70.
How is the consumer class action treated?
Show answer
Not recognized, because a loss is not probable; disclosed as a contingent liability because it is not remote.
Does Tamarind Bay's net-zero target require a provision?
Show answer
No; a public target alone is not a present obligation, though it affects estimates such as useful lives.
What is the effect of shortening the Frozen equipment's useful life?
Show answer
Higher depreciation of about 1.8 million a year, a change in estimate applied prospectively.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.