
ACCT-470 · Lesson 9 of 12 · 24 min
Fair value measurement and crypto assets
Fair value runs through this course: impairment tests, financial instruments, business combinations and share-based payment all rely on it. ACCT-211 introduced ASC 820 Fair Value Measurement, the exit price definition and the three-level hierarchy. This lesson concentrates on the hard end of the hierarchy, Level 3 measurements that depend on unobservable inputs, where judgment is greatest and errors are most likely, and on a newer asset class, crypto assets, where the FASB introduced fair value measurement in ASU 2023-08 while IFRS Accounting Standards still rely on intangible asset or inventory accounting.
A quick review of the framework
Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. It is a market-based measurement, not an entity-specific one: the inputs are the assumptions market participants would use, not management's own expectations where those differ. Inputs are classified into three levels: Level 1, quoted prices in active markets for identical assets or liabilities; Level 2, other observable inputs; and Level 3, unobservable inputs. A measurement is categorized at the level of the lowest-level input that is significant to it. ASC 820 and IFRS 13 are substantially converged, the result of a joint project completed in 2011, with minor differences such as the US practical expedient for measuring certain investments at net asset value.
Level 3 measurements carry the most risk. The inputs, such as forecast revenue, volatility, discount rates or recovery rates, are estimates, and small changes can move the result significantly. The standards require the entity to use the best information available, including its own data, adjusted if market participants would use different assumptions, and to maximize the use of relevant observable inputs. In practice that means calibrating models to any observable transaction prices, such as the price paid for an investment at initial recognition, and testing models against later transactions.
The Greenfold earn-out
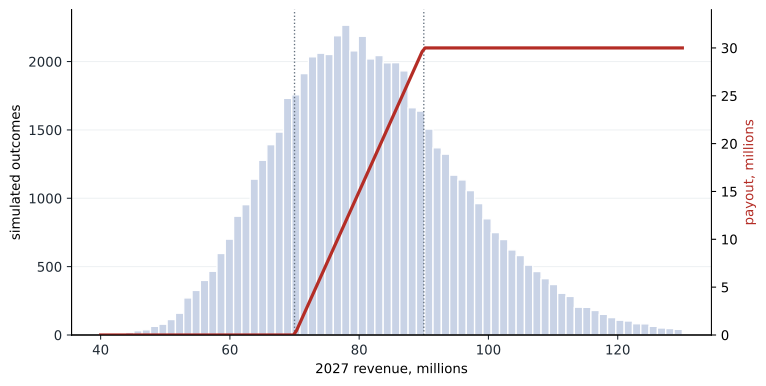
In March 2025 Tamarind Bay acquired Greenfold Plant Kitchen, a small maker of plant-based frozen and snack products, for 96.0 million in cash plus an earn-out. The sellers will receive up to 30.0 million in early 2028, depending on Greenfold's 2027 revenue: nothing if revenue is below 70 million, the full amount at 90 million or more, and a linear amount in between. The earn-out is contingent consideration, and because it will be settled in cash it is a financial liability. Both IFRS 3 and ASC 805 require it to be recognized at fair value at the acquisition date, as part of the consideration transferred, and remeasured at fair value through profit or loss at each reporting date until settled. Adjustments within the measurement period, at most one year after acquisition, that reflect facts and circumstances that existed at the acquisition date adjust goodwill; changes after that, or from events after the acquisition date such as meeting or missing targets, go to profit or loss.
Greenfold's revenue in 2026 was 74 million, and the plan for 2027 is 82 million. The payout is a non-linear function of revenue, so a single forecast cannot measure the liability: the expected payout depends on the whole distribution of possible revenue outcomes. Tamarind Bay's valuation specialists use a Monte Carlo simulation, which draws thousands of possible revenue outcomes from a distribution whose mean is the forecast and whose volatility reflects the uncertainty of the forecast, calculates the payout for each, averages them and discounts the result.
# Level 3 fair value: earn-out owed to the sellers of Greenfold Plant Kitchen (invented).
# Pays 30.0 if 2027 revenue reaches 90m, nothing below 70m, linear in between; paid early 2028.
import random, math, statistics as st
random.seed(470)
def earnout(rev): return 30.0 * min(1.0, max(0.0, (rev - 70.0) / 20.0))
def fair_value(mean_rev, vol, rate, n=200_000):
    mu = math.log(mean_rev) - vol ** 2 / 2
    pay = [earnout(math.exp(random.gauss(mu, vol))) for _ in range(n)]
    return st.fmean(pay) / (1 + rate) ** 1.25, pay
fv, pay = fair_value(82.0, 0.18, 0.085)
print(f"Expected payout: {st.fmean(pay):.2f}   P(full payout): {sum(p == 30.0 for p in pay) / len(pay):.1%}")
print(f"Fair value at Dec 31, 2026 (discounted 1.25 years at 8.5%): {fv:.2f}")
print("\nSensitivity to unobservable inputs (fair value)")
for lab, args in [("Revenue forecast 78m", (78.0, 0.18, 0.085)), ("Revenue forecast 86m", (86.0, 0.18, 0.085)),
                  ("Volatility 12%", (82.0, 0.12, 0.085)), ("Volatility 24%", (82.0, 0.24, 0.085)),
                  ("Discount rate 10.5%", (82.0, 0.18, 0.105))]:
    random.seed(470)
print(f" {lab:<22}{fair_value(*args, n=100_000)[0]:>7.2f}")Expected payout: 15.71 P(full payout): 27.2% Fair value at Dec 31, 2026 (discounted 1.25 years at 8.5%): 14.19 Sensitivity to unobservable inputs (fair value) Revenue forecast 78m 11.41 Revenue forecast 86m 16.81 Volatility 12% 15.08 Volatility 24% 13.52 Discount rate 10.5% 13.87
The fair value at December 31, 2026 is about 14.2 million, against 12.0 million at acquisition and 12.8 million at December 31, 2025. The 2026 remeasurement loss of about 1.4 million is recognized in profit and included in the acquisition-related costs that Tamarind Bay excludes from its adjusted measures in lesson 3. The sensitivity analysis shows why this is a Level 3 measurement: the result depends heavily on the revenue forecast, and less on volatility and the discount rate. Interestingly, higher volatility reduces the fair value here, because the forecast is already above the 70 million floor but below the 90 million cap, so more volatility adds more outcomes in the lower range than it adds above the cap, where payouts cannot grow. Payoff shapes like this one are why the standards expect models that capture the whole distribution rather than a single point estimate.
Governance over Level 3 measurements
Because Level 3 measurements are judgments, they need governance. Tamarind Bay's valuation committee, chaired by the chief financial officer and including the treasurer and the head of financial planning, approves the models, the key inputs and any changes in methodology each quarter. It compares inputs with market data where available, for example the volatility of listed plant-based food companies, and back-tests forecasts against results: Greenfold's 2026 revenue came in 3 percent below the forecast used a year earlier. External valuation specialists perform the Monte Carlo analysis, but management remains responsible for the result and must understand and challenge it. Auditors will test the model, the data and the assumptions and often use their own specialists, and ACCT-431 discusses how they audit complex estimates.
Disclosures for Level 3 measurements are extensive. Entities disclose the valuation techniques and inputs, quantitative information about significant unobservable inputs, such as the range and weighted average of revenue forecasts and discount rates, a reconciliation of opening and closing balances showing gains and losses, purchases, settlements and transfers, the amount of unrealized gains and losses in profit, a narrative description of the sensitivity of the measurement to changes in unobservable inputs, and a description of the valuation processes. For financial instruments, IFRS 13 also requires the quantitative effect of reasonably possible alternative assumptions if significant. Regulators often comment that companies disclose wide ranges of inputs that tell users little, and encourage tighter, entity-specific disclosure.
| Input | Value used | Range considered | Effect of increase on fair value |
|---|---|---|---|
| 2027 revenue forecast | 82.0 million | 78 to 86 million | Increase |
| Revenue volatility | 18 percent | 12 to 24 percent | Decrease in this case |
| Discount rate | 8.5 percent | 8.5 to 10.5 percent | Decrease |
| Fair value | 14.2 million | 11.4 to 16.8 million |
Other Level 3 items in practice
Other common Level 3 items include investments in private companies, measured using recent transaction prices, market multiples or discounted cash flows, often with adjustments for lack of marketability; derivatives with unobservable inputs, such as long-dated commodity contracts beyond the liquid part of the curve; and the fair values of intangible assets in purchase price allocations, such as Greenfold's brand, measured with a relief-from-royalty method, and its customer relationships, measured with a multi-period excess earnings method. The brand valuation, for instance, depends on an assumed royalty rate, typically benchmarked against licensing agreements for comparable brands, a forecast of revenue, an attrition or useful life assumption, and a discount rate, each of which can be challenged. Errors in purchase price allocations flow into goodwill and future amortization and impairment, so the judgments made in 2025 affect Tamarind Bay's statements for years.
Day-one gains and losses raise a related issue. If the transaction price differs from a fair value measured using Level 3 inputs, IFRS 9 defers the difference and recognizes it over time only as a factor that market participants would consider changes, while ASC 820 permits recognition when fair value is measured on a basis that market participants would use, subject to auditor scrutiny. Tamarind Bay rarely enters into instruments where this matters, but banks and energy traders deal with it constantly.
Crypto assets: one asset, three models
In January 2026 Tamarind Bay's board approved holding a small part of its treasury reserves, 12.0 million, in bitcoin, after a supplier relationship in Latin America began accepting crypto payments. The decision was controversial and is limited by a policy approved by the audit committee. Until recently US GAAP treated crypto assets as indefinite-lived intangible assets measured at cost less impairment, with impairment losses recognized whenever the price fell below carrying amount at any time, and no reversal when prices recovered. ASU 2023-08, Accounting for and Disclosure of Crypto Assets, effective for fiscal years beginning after December 15, 2024, and codified in ASC 350-60, changed that for in-scope crypto assets: those that meet the definition of intangible assets, do not give the holder enforceable rights to underlying goods, services or other assets, are created or reside on a distributed ledger, are secured through cryptography, are fungible and are not created or issued by the reporting entity or its related parties. Bitcoin qualifies.
# Bitcoin held as a treasury asset: carrying amount under different models (invented prices).
# 120 units bought at 100,000 dollars each (12.0 million) in January 2026.
units, cost = 120, 100_000
q_end = [("Mar 31", 84_000), ("Jun 30", 118_000), ("Sep 30", 96_000), ("Dec 31", 100_000)]
print(f"{'Date':<8}{'Price':>9}{'IAS 38 cost':>13}{'IAS 38 reval':>14}{'ASC 350-60':>12}{'Old US model':>14}")
old_us = units * cost
for d, p in q_end:
    fv = units * p
    ifrs_cost = min(units * cost, fv)   # IAS 36 impairment; reversal allowed up to original cost
    old_us = min(old_us, fv)            # pre-ASU 2023-08: impairment only, never reversed
    print(f"{d:<8}{p:>9,}{ifrs_cost / 1e6:>13.2f}{fv / 1e6:>14.2f}{fv / 1e6:>12.2f}{old_us / 1e6:>14.2f}")
print("IAS 38 cost model: impairment under IAS 36 in profit or loss; reversals capped at cost.")
print("IAS 38 revaluation model: needs an active market; gains above cost go to OCI.")
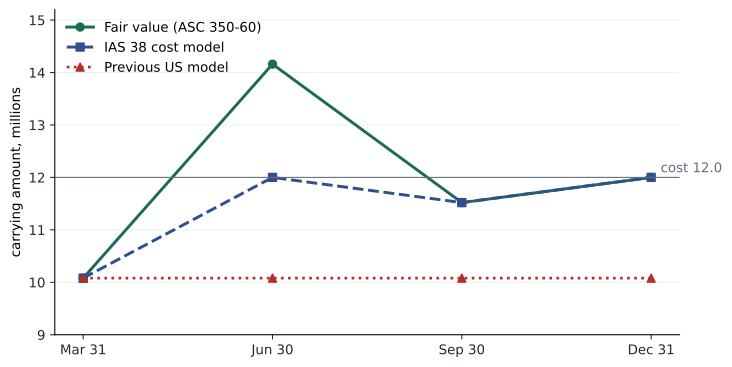
print("ASC 350-60 (ASU 2023-08): every change in fair value goes to net income.")Date Price IAS 38 cost IAS 38 reval ASC 350-60 Old US model Mar 31 84,000 10.08 10.08 10.08 10.08 Jun 30 118,000 12.00 14.16 14.16 10.08 Sep 30 96,000 11.52 11.52 11.52 10.08 Dec 31 100,000 12.00 12.00 12.00 10.08 IAS 38 cost model: impairment under IAS 36 in profit or loss; reversals capped at cost. IAS 38 revaluation model: needs an active market; gains above cost go to OCI. ASC 350-60 (ASU 2023-08): every change in fair value goes to net income.
Under ASC 350-60, Tamarind Bay measures the bitcoin at fair value at each reporting date, with changes recognized in net income and presented separately from changes in the carrying amounts of other intangible assets. Its year-end carrying amount equals fair value, and the program shows that the old model would have left it at 10.08 million, the lowest price during the year, even though bitcoin ended the year at its purchase price. Disclosures include the name, cost basis, fair value and number of units of each significant holding, restrictions, and a reconciliation of activity, including realized gains and losses. Under IFRS, a Canadian competitor would typically use the IAS 38 cost model, recognizing impairments through IAS 36 and reversals only up to cost, so the same holding would show different profit or loss patterns in each year.
Whatever the model, crypto holdings raise governance questions that go beyond measurement: custody arrangements and the risk of losing private keys, the creditworthiness of custodians and exchanges, existence and ownership evidence for auditors, and the risk of misappropriation. A company that holds crypto for treasury purposes should treat it as a risky investment, not as cash, and its disclosures should say so plainly.
Common mistakes
MistakeUsing management's own expectations instead of market participant assumptions.
InsteadFair value uses assumptions market participants would use; adjust entity data if they would differ.
MistakeMeasuring an earn-out with a single forecast.
InsteadUse a method, such as Monte Carlo simulation, that captures the whole distribution of outcomes for non-linear payoffs.
MistakeAdjusting goodwill for earn-out changes after the measurement period.
InsteadRecognize post-acquisition changes in contingent consideration in profit or loss.
MistakeDisclosing very wide input ranges with no explanation.
InsteadDisclose entity-specific, useful quantitative information and sensitivity.
MistakeContinuing to use cost less impairment for in-scope crypto assets.
InsteadApply ASC 350-60 fair value measurement to in-scope crypto assets from 2025.
MistakeIgnoring custody and safeguarding risks.
InsteadAssess and disclose custody, existence and misappropriation risks for crypto holdings.
Summary and key terms
- Fair value is a market-based exit price; Level 3 measurements rely on unobservable inputs and require the most judgment.
- Earn-outs settled in cash are liabilities remeasured at fair value through profit or loss after the measurement period.
- Non-linear payoffs need models that capture the full distribution of outcomes.
- Level 3 measurements need governance: valuation committees, calibration, back-testing and challenge of specialists.
- Disclosures include unobservable inputs, reconciliations and sensitivity.
- In-scope crypto assets are measured at fair value through net income under ASC 350-60 since 2025.
- ASU 2023-08
- The FASB update requiring fair value measurement of in-scope crypto assets through net income.
- ASC 350-60
- The Codification subtopic for in-scope crypto assets created by ASU 2023-08.
- Fair value
- The price received to sell an asset or paid to transfer a liability in an orderly transaction between market participants.
- Level 3 input
- An unobservable input used in a fair value measurement.
- Contingent consideration
- An obligation to transfer additional consideration to former owners if specified future events occur.
- Measurement period
- The period, up to one year after acquisition, during which provisional amounts in a business combination may be adjusted.
- Monte Carlo simulation
- A method that estimates outcomes by averaging results across many randomly generated scenarios.
- Relief-from-royalty method
- A valuation technique that values an asset by the royalties avoided by owning it.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Why is the earn-out a Level 3 measurement?
Show answer
Its significant inputs, the revenue forecast and its volatility, are unobservable.
Rerun the earn-out program with a revenue forecast of 90.0 million. What happens to the fair value?
Show answer
It rises to about 19.1 million, as more outcomes reach the cap.
Why does higher volatility reduce the earn-out's fair value here?
Show answer
The forecast sits between floor and cap; extra volatility adds more low outcomes than it adds payouts above the cap, which are limited.
Where is the 2026 earn-out remeasurement recognized?
Show answer
In profit or loss, within the acquisition-related costs excluded from adjusted measures.
Would a change in the earn-out estimate in June 2025 based on information about acquisition-date facts adjust goodwill?
Show answer
Yes, if it is a measurement period adjustment reflecting facts that existed at the acquisition date.
Name two elements of good governance over Level 3 measurements.
Show answer
A valuation committee approving models and inputs; calibration and back-testing; challenge of external specialists.
What would the bitcoin carrying amount be at year end under the old US model?
Show answer
10.08 million, the impaired amount, with no reversal.
Name two scope criteria for ASC 350-60.
Show answer
Fungible; created or residing on a distributed ledger; secured through cryptography; no enforceable rights to underlying assets; not issued by the entity.
What custody risks should a company disclose for crypto holdings?
Show answer
Loss of private keys, custodian or exchange failure, restrictions and misappropriation risk.
Which valuation method is typically used for an acquired brand?
Show answer
The relief-from-royalty method.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.