
ACCT-470 · Lesson 10 of 12 · 25 min
Earnings per share: complex capital structures
Earnings per share is the most quoted number in financial reporting. It appears in headlines, drives price-earnings ratios and is a common target in executive incentive plans. ASC 260 Earnings per Share requires public entities to present basic and diluted EPS on the face of the income statement, and ACCT-212 introduced the calculations. This lesson deals with the complications that arise in a real capital structure like Tamarind Bay's, which includes stock options, restricted stock units, performance stock units, convertible notes and a non-controlling interest, and compares IAS 33, which is close to ASC 260 but differs in some details. Errors in diluted EPS are surprisingly common in SEC comment letters, usually because companies forget an instrument, apply the wrong method or include an anti-dilutive instrument.
Basic EPS: getting the numerator and denominator right
Basic EPS is income available to common stockholders divided by the weighted average number of common shares outstanding during the period. The numerator excludes net income attributable to non-controlling interests and is reduced by preferred dividends, declared for non-cumulative stock or accumulated for cumulative stock, and, for redeemable non-controlling interests in temporary equity, by certain changes in redemption value that exceed fair value. Tamarind Bay's 2026 net income is 80.7 million, of which 1.2 million is attributable to the 20 percent non-controlling interest in Harrow Creek; the redemption value adjustment on the redeemable NCI does not exceed fair value, so the numerator is 79.5 million. The denominator is weighted for shares issued or repurchased during the year and adjusted retrospectively for stock splits and stock dividends. Tamarind Bay's weighted average is 120.0 million shares, so basic EPS is 0.66.
Diluted EPS: the methods
Diluted EPS adjusts basic EPS for all dilutive potential ordinary shares, that is, instruments that could entitle their holders to ordinary shares and would reduce EPS if converted. Each type of instrument has its own method. Options and warrants use the treasury stock method: the proceeds from exercise are assumed to be used to buy back shares at the average market price for the period, and only the net incremental shares are added. Unvested share awards use the same method, with the assumed proceeds including the compensation cost not yet recognized. Convertible instruments use the if-converted method: the shares from conversion are added to the denominator, and the interest or dividends that would no longer be paid, net of tax, are added back to the numerator. Contingently issuable shares are included only if the conditions would be met if the end of the reporting period were the end of the contingency period.
| Instrument | Method | Numerator effect | Denominator effect |
|---|---|---|---|
| Options and warrants | Treasury stock method | None | Shares issued less shares bought back at average price |
| Unvested restricted share awards | Treasury stock method with unrecognized cost as proceeds | None | Net incremental shares |
| Convertible debt | If-converted method | Add back after-tax interest | Add shares on conversion |
| Convertible preference shares | If-converted method | Add back preference dividends | Add shares on conversion |
| Contingently issuable shares | Include if conditions met at period end | Depends on instrument | Shares that would be issued |
| Participating securities | Two-class method | Allocate earnings to participants | Separate EPS by class |
Antidilution is the rule that most often trips up preparers. An instrument is anti-dilutive if its inclusion would increase EPS or reduce a loss per share, and anti-dilutive instruments are excluded. To ensure the most dilutive combination, instruments are considered in sequence from the most dilutive to the least dilutive, ranked by their incremental earnings per incremental share, and each is included only if it reduces the running diluted EPS. Options and unvested awards, with no numerator effect, have incremental EPS of zero and are always considered first. Convertibles, whose numerator add-back can be large, come later and are often anti-dilutive when profit is low.
# Diluted EPS for Tamarind Bay Foods, 2026 (ASC 260; invented figures, millions).
earnings, shares = 79.5, 120.0          # profit attributable to ordinary shareholders; weighted shares
avg_price, rate = 24.0, 0.25
pots = []
# Options: 6.0m at an exercise price of 18 (treasury stock method)
pots.append(("Share options", 0.0, 6.0 - 6.0 * 18.0 / avg_price))
# Unvested RSUs: 1.2m; unrecognized compensation of 4.8 is treated as assumed proceeds
pots.append(("Restricted stock units", 0.0, 1.2 - 4.8 / avg_price))
# Convertible notes: 12.5m shares; if-converted method required; add back after-tax interest
pots.append(("Convertible notes", 13.50 * (1 - rate), 12.5))
# Performance stock units: 0.6m issuable only if the 2027 margin target is met -> excluded
basic = earnings / shares
print(f"Basic EPS: {earnings} / {shares} = {basic:.3f}")
ranked = sorted(pots, key=lambda p: p[1] / p[2])
e, s = earnings, shares
for name, de, ds in ranked:
    inc = de / ds
    trial = (e + de) / (s + ds)
    keep = trial < e / s
    print(f"{name:<24} incremental EPS {inc:.3f} -> trial {trial:.3f}  {'dilutive' if keep else 'anti-dilutive, excluded'}")
    if keep: e, s = e + de, s + ds
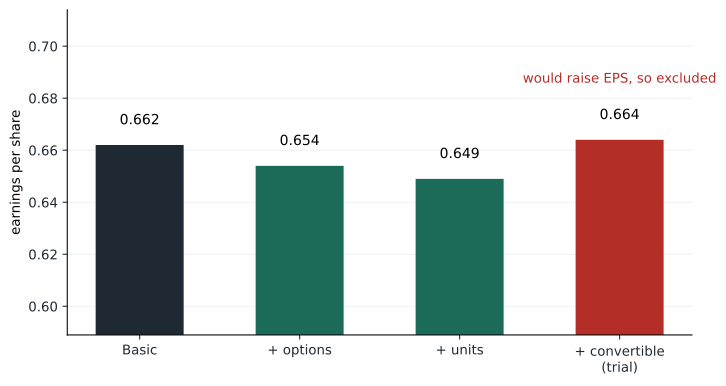
print(f"Diluted EPS: {e:.2f} / {s:.2f} = {e / s:.3f}")Basic EPS: 79.5 / 120.0 = 0.662 Share options incremental EPS 0.000 -> trial 0.654 dilutive Restricted stock units incremental EPS 0.000 -> trial 0.649 dilutive Convertible notes incremental EPS 0.810 -> trial 0.664 anti-dilutive, excluded Diluted EPS: 79.50 / 122.50 = 0.649
The options add 1.5 million incremental shares: 6.0 million shares would be issued for proceeds of 108.0 million, which would buy back 4.5 million shares at the average price of 24.00. The restricted stock units add 1.0 million: 1.2 million shares would be issued, and the 4.8 million of unrecognized compensation, treated as proceeds, would buy back 0.2 million. The convertible notes would add 12.5 million shares but also 10.13 million of after-tax interest, an incremental EPS of 0.81, which is above the running diluted EPS of 0.649. Including them would increase EPS, so they are anti-dilutive and excluded. Diluted EPS is 0.65. Since ASU 2020-06, the if-converted method is required for all convertible instruments; the treasury stock method, which some companies previously used for notes that could be settled in cash, is no longer available, and an instrument that may be settled in cash or shares is presumed to be settled in shares for diluted EPS. Under IAS 33 the add-back would include the accretion of the liability component, making the notes even more anti-dilutive.
The anti-dilution test uses profit from continuing operations as the control number, not profit for the period. If a company has discontinued operations, an instrument is dilutive or anti-dilutive based on its effect on EPS from continuing operations, and the same denominator is then used for all per-share amounts, even if it makes EPS from discontinued operations or total EPS look anti-dilutive. Tamarind Bay has no discontinued operations, so its control number is its profit attributable to shareholders.
Performance share units and other contingencies
Tamarind Bay's executives hold 0.6 million performance share units that vest in early 2028 only if the 2027 adjusted operating margin exceeds 11.5 percent. For diluted EPS, contingently issuable shares are included only to the extent that the condition would be satisfied if the end of the reporting period were the end of the contingency period. The margin condition is measured on 2027 results, so at December 31, 2026 the question is whether 2026's performance would meet it. The 2026 adjusted operating margin is 196.7 ÷ 1,840.0, or 10.7 percent, below the threshold, so the units are excluded. If a condition depends on maintaining a level already reached, such as a share price, the shares are included if the level has been reached at period end. These rules mean that diluted EPS can change from period to period as conditions are or are not met.
Options that can be settled in shares or cash at the holder's option, written put options on own shares and purchased options also need attention. Written puts and forward purchase contracts, which require a company to buy back its own shares, are dilutive when they are in the money: the reverse treasury stock method assumes the company issues enough shares at the average price to raise the cash to fulfill the contract. Purchased puts and calls are anti-dilutive and excluded. These instruments are rare for a food company but common in companies with active share buyback programs.
Participating securities and the two-class method
Securities that participate in dividends with common stock, such as unvested share-based payment awards with non-forfeitable rights to dividends or dividend equivalents, are participating securities, and ASC 260 requires the two-class method: earnings are allocated between common stock and participating securities according to dividends declared and participation rights in undistributed earnings, and basic EPS for common stock is computed using only the earnings allocated to it. For diluted EPS, a company uses the more dilutive of the two-class method and the treasury stock or if-converted method for the participating instrument. Losses are not allocated to participating securities that have no contractual obligation to share in losses. Tamarind Bay's restricted stock units do not receive dividend equivalents during vesting, so they are not participating securities, but many companies' awards do.
Presentation, other per-share measures and interim periods
Basic and diluted EPS are presented with equal prominence on the face of the income statement for income from continuing operations and net income, and per-share amounts for discontinued operations either on the face or in the notes. The notes reconcile the numerators and denominators, disclose securities excluded because they are anti-dilutive and describe subsequent transactions that would materially change the shares outstanding. Per-share amounts for non-GAAP measures, such as adjusted EPS, are permitted outside the financial statements subject to the SEC's non-GAAP rules, but per-share amounts for liquidity measures, such as cash flow per share, are prohibited in filings. Under IAS 33, as amended by IFRS 18, additional per-share amounts in the notes are allowed only for IFRS 18 subtotals and management-defined performance measures.
Interim periods add a complication: diluted EPS for the year is not the sum of the quarterly diluted EPS figures, because the average share price, the weighted average shares and the dilution test are computed separately for each period. Year-to-date diluted EPS uses a year-to-date computation, which can include an instrument that was anti-dilutive in one quarter and dilutive in another. Analysts who add up quarterly EPS to get an annual figure are often surprised by the difference.
Worked problem
A convertible that becomes dilutive
Suppose Tamarind Bay's 2027 net income attributable to shareholders rises to 140.0 million with the same capital structure and an average share price of 30.00. Are the convertible notes dilutive?
Show solution
- Basic EPS: 140.0 ÷ 120.0 = 1.167.
- Options: 6.0 − 6.0 × 18 ÷ 30 = 2.4 million incremental shares; RSUs: 1.2 − 4.8 ÷ 30 = 1.04 million (assuming the same unrecognized cost).
- Running diluted EPS after options and RSUs: 140.0 ÷ 123.44 = 1.134.
- Convertible: incremental EPS = 10.13 ÷ 12.5 = 0.81, below 1.134, so the notes are dilutive: (140.0 + 10.13) ÷ 135.94 = 1.104.
Answer: Yes. Diluted EPS would be about 1.10. When profit rises, convertibles that were anti-dilutive can become dilutive.
Common mistakes
MistakeIncluding profit attributable to non-controlling interests in the numerator.
InsteadUse profit attributable to ordinary shareholders of the parent.
MistakeAdding convertibles to diluted EPS without testing for anti-dilution.
InsteadRank instruments by incremental EPS and include only those that reduce the running figure.
MistakeIgnoring unrecognized compensation cost when applying the treasury stock method to unvested awards.
InsteadInclude it in assumed proceeds.
MistakeIncluding performance shares whose conditions are not met at period end.
InsteadInclude contingently issuable shares only if conditions would be met if the period ended at the reporting date.
MistakeAdding up quarterly diluted EPS to get annual diluted EPS.
InsteadCompute year-to-date diluted EPS separately.
MistakeUsing profit for the period as the control number when there are discontinued operations.
InsteadUse profit from continuing operations as the control number.
Summary and key terms
- Basic EPS divides profit attributable to ordinary shareholders by weighted average shares, adjusted retrospectively for splits and bonus elements.
- Diluted EPS uses the treasury stock method for options and awards and the if-converted method for convertibles.
- Instruments are sequenced from most to least dilutive and anti-dilutive instruments are excluded.
- Tamarind Bay's 2026 basic EPS is 0.66 and diluted EPS 0.65; the convertible notes are anti-dilutive.
- Contingently issuable shares are included only if conditions are met at period end.
- Participating securities require the two-class method, and interim diluted EPS is computed separately for each period.
- Basic EPS
- Profit attributable to ordinary shareholders divided by the weighted average number of ordinary shares outstanding.
- Diluted EPS
- EPS adjusted for the effects of all dilutive potential ordinary shares.
- Treasury stock method
- A method that assumes exercise proceeds are used to repurchase shares at the average market price.
- If-converted method
- A method that assumes conversion of convertible instruments, adding shares and removing related interest or dividends.
- Anti-dilution
- The effect of an instrument that would increase EPS or reduce a loss per share if included.
- Control number
- Profit from continuing operations, used to determine whether potential shares are dilutive.
- Two-class method
- An allocation of earnings between ordinary shares and participating securities according to their rights.
- Contingently issuable shares
- Shares issuable only if specified conditions are satisfied.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Why is the numerator 58.8 rather than 60.0 (or 79.5 rather than 80.7)?
Show answer
Profit attributable to the non-controlling interest, 1.2 million, is excluded.
How many incremental shares do the options add?
Show answer
1.5 million: 6.0 million issued less 4.5 million bought back with 108.0 million at 24.00.
Rerun the EPS program with an average share price of 18.00. What happens to the options?
Show answer
They are at the money: no incremental shares, so they have no effect.
Why are the convertible notes anti-dilutive in 2026?
Show answer
Their incremental EPS exceeds the running diluted EPS, so including them would increase EPS.
Why are the performance share units excluded?
Show answer
The 2026 adjusted operating margin of 10.7 percent is below the 11.5 percent condition.
What is the control number?
Show answer
Profit from continuing operations attributable to ordinary shareholders.
Why is annual diluted EPS not the sum of quarterly diluted EPS?
Show answer
Average prices, weighted shares and the dilution test differ by period.
When is an unvested award a participating security?
Show answer
When it carries non-forfeitable rights to dividends or dividend equivalents.
How does a share split during the year affect EPS?
Show answer
All periods presented are adjusted retrospectively as if the split had occurred at the start of the earliest period.
May a filing present cash flow per share?
Show answer
No; per-share amounts of liquidity measures are prohibited in filings.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.