
ACCT-211 · Lesson 9 of 12 · 32 min
Property, plant and equipment: acquisition and cost
Property, plant and equipment (PP&E) are tangible assets held for use in production or supply of goods or services, for rental to others or for administrative purposes, and expected to be used during more than one period. For Northlake they include land and a factory, calibration equipment, a fleet of service vans and the sensor stations it leases to some customers. ASC 360, Property, Plant, and Equipment, governs US GAAP, with related guidance in ASC 835-20 (capitalization of interest) and ASC 845 (nonmonetary transactions). This lesson covers recognition and the measurement of cost: which costs are capitalized, how lump-sum purchases, self-constructed assets, deferred payments, exchanges and government assistance are handled, when interest is capitalized, and how components are treated. Lesson 10 covers depreciation and derecognition; lesson 11 impairment.
Recognition
An item of PP&E is recognized as an asset when it is probable that future economic benefits associated with it will flow to the entity and its cost can be measured reliably. In practice, the key judgment is the line between capital expenditure and expense. Small items such as tools and office chairs are often expensed under a capitalization threshold policy (for example, items under $2,500), justified by materiality. Spare parts and servicing equipment are PP&E if they are expected to be used for more than one period; otherwise they are inventory. Safety and environmental equipment that does not itself increase benefits is capitalized if it is necessary for the entity to obtain the benefits of its other assets, as when a regulator requires emissions scrubbers before a plant can operate.
Elements of cost
PP&E is initially measured at cost. Cost includes the purchase price, including import duties and non-refundable purchase taxes, after deducting trade discounts and rebates; any costs directly attributable to bringing the asset to the location and condition necessary for it to operate as management intends; and the initial estimate of the costs of dismantling and removing the item and restoring the site, where the entity has an obligation. Directly attributable costs include employee benefits arising directly from construction or acquisition, site preparation, delivery and handling, installation and assembly, testing whether the asset is functioning properly, and professional fees.
Costs that are not part of PP&E include costs of opening a new facility, introducing a new product or service (including advertising), conducting business in a new location or with a new class of customer (including training staff), administration and general overheads, and costs incurred while an asset capable of operating as intended has not yet been brought into use or is operating below full capacity. Initial operating losses are expensed. Under US GAAP, the costs of testing an asset are capitalized; practice on proceeds from selling test output varies, and many companies deduct them from the asset's cost. Sales and use taxes paid on equipment are included in its cost.
Worked problem
Capitalizing the cost of a calibration machine
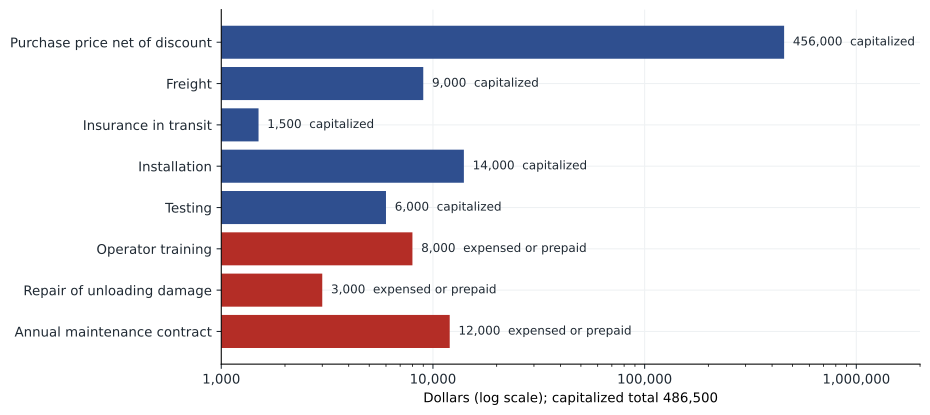
Northlake buys a calibration machine. Costs: invoice price $480,000 less a 5 percent trade discount; freight $9,000; insurance in transit $1,500; installation $14,000; testing $6,000; a two-week training course for operators $8,000; repair of damage caused by Northlake staff while unloading $3,000; annual maintenance contract $12,000. Compute the capitalized cost.
Show solution
- Purchase price: 480,000 × 95% = $456,000.
- Directly attributable: freight 9,000 + insurance in transit 1,500 + installation 14,000 + testing 6,000 = $30,500.
- Excluded: training $8,000 (expense), damage repair $3,000 (expense: not necessary to bring the asset to working condition), maintenance contract $12,000 (prepaid expense over the year).
- Capitalized cost = 456,000 + 30,500 = $486,500.
Answer: The machine is recorded at $486,500; $23,000 of the other costs are expensed or prepaid.
Lump-sum purchases
When several assets are bought together for one price, such as land and a building, the price is allocated to the individual assets in proportion to their fair values at the purchase date. The allocation matters because land is not depreciated while buildings and equipment are. Costs of demolishing an old building to make way for a new one are part of the cost of the land if the old building was bought with the land intending to demolish it; if the entity demolishes a building it has been using, the old building's remaining carrying amount is derecognized as a loss and demolition costs are generally expensed or treated as part of site preparation for the new building.
Worked problem
Lump-sum allocation
Northlake buys a site with a building and equipment for $3,600,000. Appraised fair values are land $1,200,000, building $2,400,000 and equipment $400,000. Allocate the cost.
Show solution
- Total fair value = $4,000,000; the purchase price is 90 percent of fair value.
- Land = 1,200,000 × 0.9 = $1,080,000. Building = 2,400,000 × 0.9 = $2,160,000. Equipment = 400,000 × 0.9 = $360,000.
Answer: Land $1,080,000 (not depreciated), building $2,160,000 and equipment $360,000.
Self-constructed assets
When an entity builds an asset for its own use, cost is determined using the same principles as for acquired assets: materials, direct labor and directly attributable overhead. Fixed overhead is included only to the extent it is incremental or directly attributable; some companies allocate a share of normal factory overhead, but abnormal costs (wasted materials, labor inefficiency) are excluded, and any internal profit is eliminated. The asset cannot be carried above its recoverable amount: if building it in-house costs more than buying a similar asset, the excess is a loss.
Capitalization of interest
ASC 835-20 requires interest to be capitalized on qualifying assets, those constructed or produced for an entity's own use or for sale or lease as discrete projects (such as ships or real estate developments) that take time to prepare, but not on inventories routinely produced in large quantities or assets already in use. The amount capitalized is the avoidable interest: the interest that would not have been incurred if the expenditures had not been made. It is computed by applying an interest rate to the weighted-average accumulated expenditures (WAAE) during the period: the rate on specific borrowings for the asset to expenditures up to that amount, and the weighted-average rate on other borrowings to any excess. The amount capitalized cannot exceed actual interest incurred. Unlike IFRS, investment income earned on unspent borrowed funds is generally not offset against capitalized interest. IFRS's IAS 23 is similar in concept but differs in such details.
# Interest capitalized on a self-constructed test facility (illustrative)
# Expenditures during the year: (month spent, amount)
spend = [(1, 600_000), (4, 1_200_000), (9, 900_000)]       # facility completed 31 Dec
specific_loan, specific_rate = 1_000_000, 0.06               # borrowed for the project
general_debt, general_interest = 5_000_000, 400_000          # other borrowings
general_rate = general_interest / general_debt

waae = sum(amount * (12 - (m - 1)) / 12 for m, amount in spend)   # months outstanding
print(f"Weighted-average accumulated expenditures: {waae:,.0f}")
on_specific = min(waae, specific_loan) * specific_rate
on_general = max(waae - specific_loan, 0) * general_rate
avoidable = on_specific + on_general
actual = specific_loan * specific_rate + general_interest
capitalized = min(avoidable, actual)
print(f"Specific {on_specific:,.0f} + general at {general_rate:.1%} {on_general:,.0f} = {avoidable:,.0f}")
print(f"Actual interest {actual:,.0f}; capitalized {capitalized:,.0f}; expensed {actual - capitalized:,.0f}")Weighted-average accumulated expenditures: 1,800,000 Specific 60,000 + general at 8.0% 64,000 = 124,000 Actual interest 460,000; capitalized 124,000; expensed 336,000
Northlake spends $2.7 million building a wind-tunnel test facility over the year. Weighted for the months each amount was outstanding, accumulated expenditures average $1.8 million. The first $1 million is financed by a specific 6 percent loan, giving $60,000; the remaining $800,000 attracts the 8 percent general rate, giving $64,000. Capitalized interest is $124,000, well below actual interest of $460,000, so the rest is expensed. Under US GAAP, interest earned on temporarily invested borrowings is generally not netted against capitalized interest.
Deferred payment, exchanges and government assistance
An asset bought on deferred payment terms beyond normal credit is recorded at its cash price equivalent, the present value of the payments; the difference is interest expense over the payment period. An asset acquired by issuing shares is recorded at the fair value of the asset received (or of the shares, if more reliably measurable). An asset contributed by a shareholder or donated is recorded at fair value with a corresponding credit to contributed surplus (or, for donations, income under the applicable standard).
When an asset is acquired in exchange for a nonmonetary asset, ASC 845 measures it at fair value (with a gain or loss on the asset given up) unless fair value is not determinable, the exchange lacks commercial substance or it is an exchange of inventory to facilitate sales to customers; in those cases the new asset is recorded at the carrying amount of the asset given up (plus any cash paid), with gains generally not recognized unless cash (boot) is received. An exchange has commercial substance if the entity's future cash flows are expected to change significantly. IFRS (IAS 16) is similar.
Worked problem
Trading in vans
Northlake trades in an old van (cost $60,000, accumulated depreciation $42,000, fair value $14,000) plus $46,000 cash for a new electric van with a list price of $62,000. The exchange has commercial substance. Record it.
Show solution
- Cost of the new van = fair value of the old van given up + cash = 14,000 + 46,000 = $60,000 (the dealer's list price is not the measure when a better fair value is available).
- Carrying amount of old van = 60,000 − 42,000 = $18,000. Loss on disposal = 18,000 − 14,000 = $4,000.
- Entry: debit new van 60,000; debit accumulated depreciation 42,000; debit loss 4,000; credit old van 60,000; credit cash 46,000.
- If the exchange lacked commercial substance, the new van would be recorded at 18,000 + 46,000 = $64,000 and no gain or loss recognized (although the asset would then be tested for impairment).
Answer: With commercial substance: new van $60,000 and a $4,000 loss.
US GAAP has no comprehensive standard on government grants to business entities. Many companies analogize to IAS 20 (recognizing grants when there is reasonable assurance of compliance and receipt, and presenting asset-related grants as deferred income or as a reduction of the asset's cost) or to the contribution guidance in ASC 958-605. ASU 2021-10 requires annual disclosure of transactions with a government accounted for by analogy to a grant or contribution model: the nature of the transaction, the method used, the line items affected and significant terms. Recent federal programs, such as manufacturing and clean-energy incentives, made this disclosure more important; some tax credits that are transferable or refundable raise their own accounting questions.
Worked problem
Asset-related government grant
Northlake receives a $300,000 grant toward a $1,500,000 clean-manufacturing line with a 10-year life and no residual value. Show the two presentation options.
Show solution
- Option 1 (deduct from the asset): record the line at $1,200,000; depreciation $120,000 a year.
- Option 2 (deferred income): record the line at $1,500,000 with depreciation of $150,000 a year, and deferred grant income of $300,000 recognized at $30,000 a year.
- Net effect on profit is the same: $120,000 a year.
Answer: Either way, the grant reduces the net annual cost of the asset to $120,000.
Components and subsequent expenditure
US GAAP permits but does not require component depreciation; most US companies depreciate assets as single units, and major overhauls may be expensed, capitalized and amortized until the next overhaul (the deferral method), or capitalized as a component (the built-in overhaul method), depending on the industry and policy. IFRS (IAS 16) requires significant parts with different useful lives to be depreciated separately, which is one of the more noticeable practical differences for companies with large, complex assets such as aircraft or factories.
After initial recognition, the costs of day-to-day servicing (repairs and maintenance: labor, consumables, small parts) are expensed. Costs that replace a part, add to the asset or improve it so that future benefits increase (longer life, greater capacity, better quality of output, lower operating costs) are capitalized, and the carrying amount of any replaced part is derecognized. Northlake's replacement of a van's battery pack that extends its range and life is capitalized, with the old pack's remaining carrying amount written off; an oil change is an expense.
Common mistakes
MistakeCapitalizing staff training on new equipment.
InsteadTraining is not necessary to bring the asset to working condition; expense it.
MistakeAllocating a lump-sum price only between land and building and ignoring equipment included.
InsteadAllocate to every asset acquired in proportion to fair values.
MistakeCapitalizing interest on assets already in use or on routinely produced inventory.
InsteadOnly qualifying assets that take a substantial period to get ready attract capitalized borrowing costs.
MistakeRecording an exchanged asset at the dealer's list price.
InsteadUse the fair value of the asset given up (or received, if clearer), or carrying amount if the exchange lacks commercial substance.
MistakeCapitalizing routine repairs that only maintain the asset.
InsteadExpense day-to-day servicing; capitalize only replacements and improvements that increase future benefits.
Summary and key terms
- PP&E is recognized when future benefits are probable and cost can be measured reliably.
- Cost includes the purchase price, directly attributable costs and estimated dismantling and restoration obligations.
- Training, opening, advertising, administration and initial operating losses are expensed.
- Lump-sum purchases are allocated in proportion to the fair values of the assets acquired.
- ASC 835-20 requires avoidable interest on qualifying assets to be capitalized, based on weighted-average accumulated expenditures.
- Exchanges with commercial substance are measured at fair value with a gain or loss; otherwise at the carrying amount given up.
- US GAAP permits but does not require component depreciation.
- Weighted-average accumulated expenditures
- Construction expenditures weighted by the time they were outstanding during the period, used to compute avoidable interest.
- Property, plant and equipment
- Tangible items held for use in operations and expected to be used during more than one period.
- Directly attributable cost
- A cost necessary to bring an asset to the location and condition to operate as intended.
- Lump-sum purchase
- The acquisition of several assets for a single price, allocated by relative fair values.
- Qualifying asset
- An asset that necessarily takes a substantial period of time to get ready for its intended use or sale.
- Commercial substance
- The expectation that an exchange will significantly change the entity's future cash flows.
- Government grant
- Assistance by government in the form of a transfer of resources in return for compliance with conditions.
- Componentization
- Depreciating significant parts of an asset with different useful lives separately.
- Capital expenditure
- A cost capitalized as part of an asset because it provides future benefits.
- Revenue expenditure
- A cost, such as routine repair, expensed as incurred.
- Capitalization threshold
- A materiality-based policy amount below which asset purchases are expensed.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Which of these are capitalized: delivery, installation, staff training, testing?
Show answer
Delivery, installation and testing.
A building is bought with land for $900,000; fair values land $400,000, building $600,000. Allocate.
Show answer
Land $360,000; building $540,000.
Why does the land and building allocation matter?
Show answer
Land is not depreciated; the building is.
Name two conditions for capitalizing borrowing costs or interest.
Show answer
A qualifying asset; expenditures and borrowing costs being incurred; activities to prepare the asset under way.
WAAE $800,000, specific loan $500,000 at 5 percent, general rate 8 percent. Avoidable interest?
Show answer
25,000 + 300,000 × 8% = $49,000.
An asset with a carrying amount of $30,000 and fair value $25,000 is exchanged plus $10,000 cash, with commercial substance. Cost of new asset and gain or loss?
Show answer
Cost $35,000; loss $5,000.
Same exchange without commercial substance. Cost?
Show answer
$40,000 (carrying amount plus cash), with no loss recognized.
A $200,000 grant toward a $1,000,000 machine with a 5-year life. Annual net expense?
Show answer
$160,000.
Northlake replaces a van battery pack, extending life by three years. Capitalize or expense?
Show answer
Capitalize, and derecognize the carrying amount of the old pack.
Rerun the interest program with the September expenditure removed. What is capitalized?
Show answer
WAAE $1,500,000; capitalized 60,000 + 500,000 × 8% = $100,000.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.