
MBA-511 · Lesson 6 of 12 · 19 min
Estimating project cash flows
When the cohort reconvenes, Dr. Varga puts the press-line figures from lesson 5 back on the screen and admits that he simplified them. A real proposal does not arrive with a tidy row of after-tax cash flows. It arrives with an engineering estimate of the equipment cost, a production manager's guess at the labour saved, a purchasing estimate of scrap reduction, and a spreadsheet from the accounting team showing the project's effect on reported earnings. Turning those into the cash flows that belong in an NPV calculation is where most of the judgment in capital budgeting lies, and where most of the errors are made.
The incremental principle
The cash flows that matter are incremental: the difference between the firm's cash flows with the project and without it. Everything follows from that principle. A cost that will be incurred whether or not the project goes ahead is irrelevant. A benefit that the firm would enjoy anyway is irrelevant. What counts is how the decision changes the firm's future cash.
Four kinds of item commonly trip up analysts. Sunk costs, money already spent, should be ignored; Northfield's 400,000 dollars of engineering studies for the press line are gone whatever the board decides. Opportunity costs, the value of resources the project uses that could be used elsewhere, should be included even when no cash changes hands; if the press line occupies floor space that could otherwise be leased to a neighbouring firm for 250,000 dollars a year, that forgone rent is a cost of the project. Side effects on the firm's other products count: a new product that takes sales from an existing one, called cannibalization, reduces the incremental benefit, while one that helps sell other products adds to it. And allocated overhead counts only to the extent that it actually changes; if head office costs are spread across projects by a formula but would not rise, they are not incremental.
| Item | Include? | Reason |
|---|---|---|
| Engineering study already paid | No | Sunk cost |
| Floor space that could be leased out | Yes | Opportunity cost |
| Lost sales of the old bracket line | Yes, as a reduction | Cannibalization |
| Share of head office costs, unchanged in total | No | Not incremental |
| Extra inventory of spare parts | Yes | Investment in working capital |
| Interest on the loan to buy the press | No | Financing is reflected in the discount rate |
Cash flow, not profit
The NPV calculation uses after-tax cash flows, not accounting profit. Three adjustments turn one into the other. First, depreciation is not a cash outflow; the cash was spent when the equipment was bought. But depreciation for tax purposes reduces the taxes the firm pays, and that tax saving, the depreciation tax shield, is a real cash benefit. Second, investment in working capital, such as inventory, receivables and spare parts, ties up cash at the start and releases it when the project ends. Third, interest is excluded from project cash flows, because the cost of financing is captured in the discount rate; including it would count the cost of debt twice.
In this formula, revenue minus cash operating costs is taxed at the tax rate, the depreciation deduction saves tax equal to the tax rate times the deduction, and capital spending and increases in working capital are subtracted. An equivalent form starts with operating profit after tax and adds back depreciation, the same structure as free cash flow to the firm in lesson 4. Project analysis and company valuation use the same building blocks.
Depreciation for tax
In Canada, tax depreciation is called capital cost allowance, CCA. Assets are grouped in classes, each with a prescribed rate, and most classes use the declining-balance method: each year the firm may deduct the class rate times the undepreciated capital cost, UCC, the balance not yet deducted. Under the half-year rule, only half the normal rate may be claimed in the year an asset is acquired. To encourage investment, the federal government introduced the accelerated investment incentive in 2018, which for eligible property suspends the half-year rule and allows one and a half times the normal first-year rate, and for some classes, such as manufacturing and processing machinery and clean energy equipment, allowed full expensing for several years. The incentive began phasing out from 2024, and the November 2025 federal budget, under its productivity super-deduction, proposed restoring the enhanced first-year write-off for most capital assets and allowing immediate expensing of eligible manufacturing and processing buildings acquired from Budget Day and available for use before 2030. Because the rules change often, an analyst should confirm the class, the rate and the first-year treatment for each asset before building the model.
When CCA continues indefinitely on a declining balance, the present value of all the tax savings from an asset has a closed form. With the half-year rule, a capital cost C, a CCA rate d, a tax rate T and a discount rate k, the present value of the CCA tax shield is the expression below, less a similar term for the salvage value removed from the class when the asset is sold. The formula is a compact way to see why faster write-offs matter: they move tax savings closer to the present.
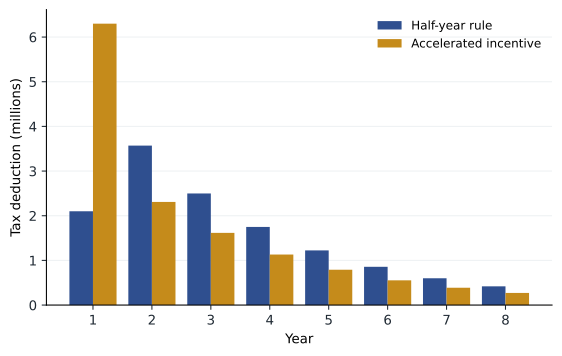
Northfield's press line in full
The press line costs 14 million dollars. Engineering expects it to save enough in labour and scrap to add 3.4 million dollars a year after tax, which at Northfield's combined federal and Ontario tax rate of 26.5 per cent is about 4.63 million before tax. It requires 0.8 million dollars of spare parts and tooling, recovered at the end of eight years, when the line can be sold for about 1.5 million. Assume it falls in a class with a 30 per cent declining-balance rate, and for simplicity that the remaining balance is deducted when the asset is sold. The general federal corporate rate is 15 per cent, and provincial rates add between about 8 and 16 points; Canadian-controlled private corporations pay a lower combined rate, with a federal small business rate of 9 per cent, on the first 500,000 dollars of active business income, which Northfield, with taxable income well above that, mostly does not benefit from.
# Northfield press line: incremental after-tax cash flows with CCA (millions)
cost, life, salvage = 14.0, 8, 1.5
savings, tax, r = 3.4 / (1 - 0.265), 0.265, 0.09   # pre-tax savings giving 3.4 after tax
nwc = 0.8                                           # spare parts and tooling, recovered at the end
d = 0.30                                            # declining-balance CCA rate for the class

def cca_schedule(cost, d, years, first_year_factor):
    ucc, out = cost, []
    for t in range(1, years + 1):
        rate = d * first_year_factor if t == 1 else d
        claim = ucc * rate
        out.append(claim)
        ucc -= claim
    return out, ucc

def project(first_year_factor):
    cca, ucc_end = cca_schedule(cost, d, life, first_year_factor)
    flows = [-cost - nwc]
    for t in range(1, life + 1):
        cf = savings * (1 - tax) + cca[t - 1] * tax
        if t == life:
            cf += salvage + nwc
            cf += (ucc_end - salvage) * tax      # terminal loss treated as fully deductible here
        flows.append(cf)
    return sum(f / (1 + r) ** t for t, f in enumerate(flows)), cca

for label, factor in [("half-year rule", 0.5), ("accelerated incentive", 1.5)]:
    v, cca = project(factor)
print(f"{label:22s} first-year CCA {cca[0]:5.2f} NPV {v:5.2f}")half-year rule first-year CCA 2.10 NPV 7.74 accelerated incentive first-year CCA 6.30 NPV 7.96
Two lessons emerge. First, once the tax shield, working capital and salvage value are included, the NPV rises to about 7.7 million dollars, well above the simple figure of 4.8 million in lesson 5, which treated 3.4 million a year as the whole after-tax cash flow and left out the tax value of the CCA deductions. Second, the accelerated incentive adds about 0.2 million dollars of value by moving tax deductions forward. For a capital-intensive firm making many such investments, the incentive changes which projects clear the hurdle, which is exactly what the policy intends.
Working capital and terminal values
Working capital is easy to forget and can change a decision. A new store needs inventory before it makes its first sale; a new product line needs receivables because customers pay on credit. These investments are cash outflows at the start and, if the project ends, cash inflows when the inventory is sold off and receivables are collected. Grace's estimate for a new Fairway store includes 1.1 million dollars of inventory, partly offset by 0.7 million of supplier credit, so the net working capital investment is 0.4 million. Cedarline, the cohort's case company, shows what happens when working capital is ignored: its inventory grew from 58 to 128 million dollars over four years, absorbing cash that its reported profits never revealed.
At the end of the forecast, a project may have a salvage value, or it may continue indefinitely, in which case a terminal value is needed, usually a growing perpetuity of the final year's cash flow. When an asset is sold, the tax consequences depend on how its sale price compares with its remaining tax value: a sale above that value creates a taxable recapture or gain, a sale below it a deductible loss. These end-of-life effects are small for long projects at high discount rates but can matter for short ones.
Inflation, scenarios and forecasting bias
Forecasts should be consistent about inflation. If the discount rate is nominal, as rates observed in markets are, the cash flows should include expected inflation in prices, wages and materials. A common mistake is to hold revenues flat in today's dollars and discount at a nominal rate, which understates the NPV of every long project. Tax depreciation, by contrast, is fixed in nominal terms at the original cost, so its real value falls with inflation.
Forecasts are also systematically optimistic. Studies of large capital projects, notably by Bent Flyvbjerg, find that cost overruns and benefit shortfalls are the norm, not the exception, and that the cause is less often bad luck than a combination of optimism and strategic misrepresentation by project sponsors. Dr. Varga recommends three defences. Reference-class forecasting compares a project's estimates with the actual outcomes of similar past projects. Scenario analysis builds a pessimistic, base and optimistic case with internally consistent assumptions, rather than flexing one variable at a time. And break-even analysis asks how far a key assumption, such as annual savings, could fall before the NPV reaches zero; for the press line, after-tax savings could fall by about two fifths before the project destroys value.
Worked problem
A new Fairway store
Grace estimates that a new store will cost 9 million dollars to fit out and will generate pre-tax operating cash flow of 1.6 million dollars a year for 15 years. Net working capital of 0.4 million is needed at the start and recovered at the end. Ignore depreciation for a moment and use a tax rate of 25 per cent and a cost of capital of 8 per cent. What is the NPV before the depreciation tax shield, and what does the answer tell Grace?
Show solution
- After-tax operating cash flow: 1.6 times 0.75 = 1.2 million dollars a year.
- PV of 15 years of 1.2 million at 8 per cent: annuity factor 8.559, so 10.27 million.
- Initial outlay: 9.0 plus 0.4 = 9.4 million. PV of working capital recovered in year 15: 0.4 / 3.172 = 0.13 million.
- NPV before the tax shield = 10.27 + 0.13 minus 9.4 = about 1.0 million dollars.
Answer: The store has an NPV of about 1.0 million dollars before counting the tax value of depreciation on the fit-out, which would add more. It is a modest positive. Because store openings across the industry often fall short of their forecasts, Grace should test how far first-year sales could miss before the NPV turns negative.
Common mistakes
MistakeMoney already spent on a feasibility study is a cost of the project.
InsteadIt is sunk; only future cash flows that change with the decision count.
MistakeDepreciation is a cash outflow.
InsteadDepreciation is not cash, but its tax deduction saves cash.
MistakeInterest on the loan should be subtracted from project cash flows.
InsteadFinancing costs are captured in the discount rate.
MistakeWorking capital can be ignored because it is recovered at the end.
InsteadTying up cash for years has a real cost in present value terms.
Summary and key terms
- Project cash flows are incremental: the difference between the firm's cash flows with and without the project.
- Ignore sunk costs; include opportunity costs, cannibalization and side effects; exclude unchanged overhead and interest.
- After-tax cash flow equals operating cash flow after tax plus the depreciation tax shield, minus capital spending and working capital investment.
- Accelerated tax depreciation adds value by moving tax savings closer to the present.
- Use nominal flows with nominal rates, build consistent scenarios and check forecasts against past projects.
- Incremental cash flow
- The change in a firm's cash flow that results from a decision.
- Sunk cost
- A cost already incurred that cannot be recovered and should not affect a decision.
- Opportunity cost
- The value of the best alternative use of a resource.
- Cannibalization
- The loss of sales of existing products caused by a new product.
- Depreciation tax shield
- The tax saved because depreciation is deductible, equal to the tax rate times the deduction.
- Accelerated depreciation
- Tax depreciation that allows larger deductions in an asset's early years than in its later years.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A project uses a warehouse that the firm owns and could lease out for 300,000 dollars a year. Should that amount be in the project analysis?
Show answer
Yes. The forgone rent is an opportunity cost of using the warehouse for the project.
A firm with a 25 per cent tax rate claims 2 million dollars of tax depreciation in a year. What is the tax shield?
Show answer
0.25 times 2 million = 500,000 dollars of tax saved.
A new product will sell 10 million dollars a year but will reduce sales of an existing product by 3 million. What revenue should go in the analysis?
Show answer
The incremental revenue of 7 million dollars, along with the incremental costs.
Why does faster tax depreciation raise a project's NPV if total deductions are unchanged?
Show answer
The tax savings arrive sooner, so their present value is higher.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.