
MBA-511 · Lesson 10 of 12 · 19 min
Payout policy: dividends and buybacks
Fairway Grocers has had a good year. Its new distribution centre is running, its capital spending is falling back to maintenance levels, and its finance team expects free cash flow of about 60 million dollars, well above what it needs. Grace sits on the steering committee that will recommend what to do with the cash. One director wants to raise the dividend by a quarter. Another wants a share buyback, arguing that the shares are undervalued and that buying them back will raise earnings per share. A third wants to keep the cash for acquisitions. Dr. Varga uses the debate to ask a deceptively simple question: does it matter how a company returns cash to its shareholders, or whether it does at all?
Dividends and buybacks
A company can return cash in two main ways. It can pay a dividend, a cash payment to every shareholder in proportion to their holding, usually quarterly in North America, or as a one-time special dividend. Or it can repurchase its own shares, buying them in the open market over time, through a tender offer at a fixed price, or by private negotiation with a large holder. Both put cash in shareholders' hands and reduce the company's equity. The difference is who receives it. A dividend goes to everyone; a buyback goes only to shareholders who choose to sell, while those who keep their shares end up owning a larger fraction of a smaller company.
In Canada, most open-market buybacks are conducted as normal course issuer bids, NCIBs, under stock exchange rules. On the Toronto Stock Exchange, a company may generally buy back, over twelve months, up to the greater of 10 per cent of its public float or 5 per cent of its outstanding shares, and on any day no more than 25 per cent of its average daily trading volume, with some exceptions. Larger or faster repurchases require a substantial issuer bid, a formal tender offer to all shareholders. In 2024, Canada also introduced a federal tax of 2 per cent on the net value of shares that public corporations repurchase, a measure modelled on the US excise tax, though its future has been debated since.
Over the past few decades, buybacks have grown from a minor part of payouts to the larger part for many large companies, a shift that began in the 1980s and accelerated after US regulators clarified the rules in 1982. Dividends remain important for mature companies with steady cash flows, such as banks, utilities, telecommunications and pipeline companies, and many investors, including retirees and pension funds, value a predictable income.
The irrelevance benchmark
In 1961, Merton Miller and Franco Modigliani applied the logic of lesson 9 to payouts. Hold the firm's investment policy fixed. If there are no taxes, transaction costs or information differences, then how the firm distributes its cash cannot affect its value. A shareholder who wants more cash than the dividend can sell some shares; one who wants less can reinvest the dividend. Paying a dividend lowers the share price by the amount paid, so shareholder wealth is unchanged. A buyback at a fair price leaves the remaining shares worth exactly what they were. Value is created by the investments the firm makes, not by how it hands back the cash those investments generate.
The key phrase is holding investment fixed. Payout policy matters a great deal if it changes investment, for example if a firm cuts good projects to pay a dividend, or if cash left inside a firm is wasted on poor acquisitions. The director who wants to keep Fairway's 60 million dollars for acquisitions is making an investment proposal, which should be judged by its NPV, not a payout proposal.
Why buybacks raise earnings per share, and why that is not the point
A buyback reduces the number of shares, so if earnings are unchanged, earnings per share rise. But earnings are not unchanged: the cash used for the buyback was earning interest, or the debt used to fund it costs interest. Whether EPS rises depends on whether the after-tax yield on the cash given up is lower than the earnings yield on the shares bought, the inverse of the price-earnings ratio. For a company trading at a high P/E, paying with cash that earns little, EPS almost always rises. That does not mean value has been created. As MM showed, a buyback at a fair price leaves the value per share unchanged; the higher EPS is offset by higher risk, because the firm now has less cash or more debt, so the P/E falls.
# Dividend versus buyback: effect on EPS, share price and shareholder wealth (millions)
shares, price = 100.0, 30.0         # millions of shares, price per share
earnings_ops = 210.0                # operating earnings after tax
cash, cash_yield, tax = 60.0, 0.04, 0.25
interest_on_cash = cash * cash_yield * (1 - tax)
eps0 = (earnings_ops + interest_on_cash) / shares
value0 = shares * price             # includes the cash

# Option 1: special dividend of all 60
div_per_share = cash / shares
price_div = (value0 - cash) / shares
eps_div = earnings_ops / shares
# Option 2: buy back shares at the fair price
bought = cash / price
price_bb = (value0 - cash) / (shares - bought)
eps_bb = earnings_ops / (shares - bought)
print(f"before:   EPS {eps0:.3f}, price {price:.2f}, P/E {price / eps0:.1f}")
print(f"dividend: EPS {eps_div:.3f}, price {price_div:.2f} + cash {div_per_share:.2f} per share")
print(f"buyback:  EPS {eps_bb:.3f}, price {price_bb:.2f}, shares {shares - bought:.1f}, P/E {price_bb / eps_bb:.1f}")
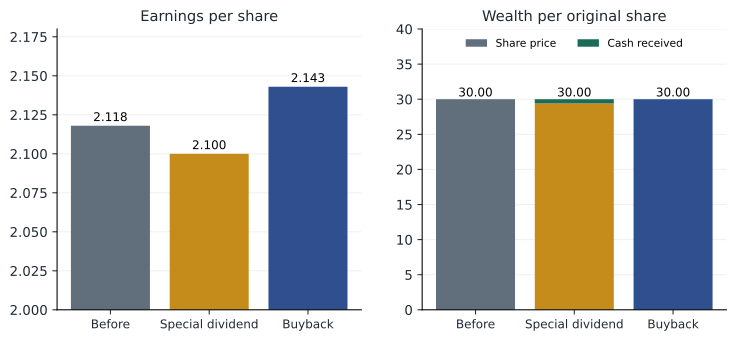
print(f"wealth per original share: dividend {price_div + div_per_share:.2f}, buyback {price_bb:.2f}")before: EPS 2.118, price 30.00, P/E 14.2 dividend: EPS 2.100, price 29.40 + cash 0.60 per share buyback: EPS 2.143, price 30.00, shares 98.0, P/E 14.0 wealth per original share: dividend 30.00, buyback 30.00
In the example, the buyback raises EPS by about 1 per cent while the dividend lowers it, yet a shareholder's wealth is 30 dollars a share either way. The P/E ratio falls after the buyback, reflecting the loss of the safe cash. Dr. Varga warns that executive pay tied to EPS creates an incentive to prefer buybacks for the wrong reason, and that boards should judge payout decisions on their effect on value per share, not EPS.
Taxes
Taxes break the irrelevance result. In Canada, dividends from Canadian corporations receive the dividend tax credit, which is designed to integrate corporate and personal tax: the individual grosses up the dividend, 38 per cent for eligible dividends from large public companies, and then claims a credit for the corporate tax already paid. At top rates the combined personal tax on eligible dividends in most provinces is roughly 35 to 47 per cent, compared with roughly 24 to 27 per cent on capital gains, of which only half is taxable. Shareholders who sell in a buyback pay capital gains tax only on their gain, and only when they sell, while those who keep their shares defer tax. For taxable individuals, buybacks are therefore often more tax-efficient than dividends, though the gap is smaller than the headline rates suggest. Pension funds and registered accounts such as RRSPs and TFSAs pay no tax on either, and Canadian corporations generally receive dividends from other Canadian corporations tax-free.
Because different investors face different tax treatment, firms tend to attract shareholders who like their payout policy, the clientele effect. Retirees who want income and tax-exempt pension funds hold high-dividend utilities and banks; taxable investors who prefer gains hold growth companies that pay little. Once a clientele has formed, changing the policy abruptly can impose costs on the firm's own shareholders.
Signalling and smoothing
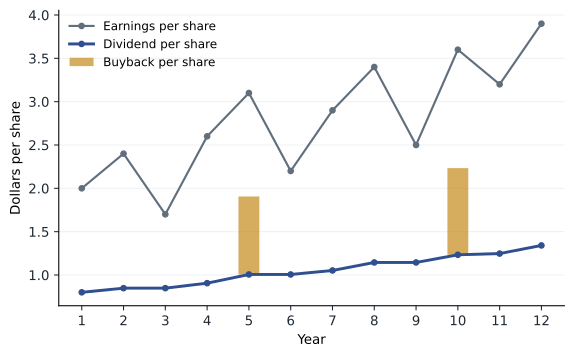
Managers know more about their firm's prospects than investors do, and payouts convey information. John Lintner's interviews with managers in the 1950s found that firms set a long-run target payout ratio, adjust dividends gradually towards it, and are very reluctant to cut them. Later studies, including a survey of chief financial officers by Alon Brav and colleagues in 2005, found that this reluctance remains strong. Because a dividend increase is a commitment managers expect to sustain, investors read it as a sign of confidence, and share prices rise on announcements of increases and fall sharply on cuts. Buybacks are more flexible, and investors treat them as less of a commitment, which is exactly why firms use them for cash flows they are not sure will last.
Buyback announcements carry their own signal: they suggest management believes the shares are undervalued. Studies find that share prices rise on average on announcements of open-market programs, and that firms with long buyback programs have on average outperformed, though many announced programs are never completed. A buyback at a price above intrinsic value transfers wealth from the shareholders who remain to those who sell, so the case for buybacks depends on the board's honest judgment of value, not on the mechanics of EPS.
A practical framework
Dr. Varga closes with a framework that Grace takes back to Fairway. First, fund all positive-NPV investments and keep enough liquidity and borrowing capacity for flexibility. Second, set a regular dividend at a level the firm is confident it can sustain through a downturn, and grow it in line with sustainable earnings. Third, return the remaining excess cash through buybacks when the shares appear fairly or undervalued, or through special dividends when they do not. Fourth, consider shareholders' tax position and the firm's clientele. Fifth, never borrow to fund a payout that would weaken the firm's credit or its ability to invest.
Payouts in private and not-for-profit organizations
The same logic applies outside listed companies, though the mechanics differ. At Northfield, a family-owned firm, the payout decision is a negotiation between the family's need for income and diversification, discussed in lesson 9, and the company's need to fund investment. Because there is no market price to signal value, the family should base any repurchase of a relative's shares on an independent valuation. At Kestrel, payouts are years away: a young, fast-growing firm that needs outside capital should not be returning cash at all. And at Lakeview, which has no shareholders, the question becomes how much surplus to keep as reserves against future shocks and how much to spend on care, a judgment its board makes with the same attention to liquidity and flexibility.
Worked problem
Fairway's 60 million dollars
Fairway has 80 million shares trading at 25 dollars, a regular dividend of 0.80 dollars a year and expected free cash flow of 60 million dollars in excess of its investment needs, of which management is confident that about 20 million will recur in future years. How might the committee divide the payout?
Show solution
- Recurring excess cash of 20 million supports a dividend increase of 20 / 80 = 0.25 dollars a share, from 0.80 to 1.05 dollars, which the board can sustain.
- The remaining 40 million is a one-time surplus and should not be committed as a regular dividend.
- If the board believes the shares are fairly valued or cheap, a buyback of 40 million would retire about 1.6 million shares, 2 per cent of the total, at 25 dollars.
- If the board thinks the shares are expensive, a special dividend of 0.50 dollars a share returns the cash without buying at an inflated price.
Answer: A sustainable dividend increase of about 0.25 dollars a share plus a 40 million dollar buyback or special dividend returns the cash while matching each form of payout to the nature of the cash flow. The acquisition proposal should be considered separately, on its own NPV.
Common mistakes
MistakeA buyback creates value because it raises EPS.
InsteadEPS may rise, but at a fair price value per share is unchanged and risk is higher.
MistakeHigh dividends make a company more valuable.
InsteadWith investment fixed and no taxes, payout form does not change value; taxes often favour buybacks.
MistakeA dividend cut always means the firm is in trouble.
InsteadIt is often read that way, which is why firms avoid cuts, but a cut to fund good investments can raise value.
MistakeBuybacks at any price benefit remaining shareholders.
InsteadBuying above intrinsic value transfers wealth to selling shareholders.
Summary and key terms
- Firms return cash through dividends and share repurchases; buybacks have grown to a large share of payouts.
- With investment fixed and no taxes or frictions, payout policy does not affect value.
- Buybacks raise EPS when the earnings yield exceeds the after-tax return on cash, but this does not by itself create value.
- Taxes, clienteles and signalling explain real-world payout choices; dividends are smoothed and rarely cut.
- Pay a sustainable regular dividend and return excess, uncertain cash through buybacks or special dividends.
- Share repurchase
- A company's purchase of its own shares from investors.
- Normal course issuer bid
- A Canadian program of open-market share repurchases within exchange limits.
- Dividend tax credit
- A Canadian personal tax credit that offsets corporate tax already paid on dividends.
- Clientele effect
- The tendency of investors to hold firms whose payout policies suit their needs and tax positions.
- Dividend smoothing
- The practice of adjusting dividends gradually and avoiding cuts.
- Signalling
- The communication of management's information to investors through actions such as dividend changes.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A share trades at 40 dollars just before going ex-dividend on a 1 dollar dividend. Ignoring taxes, what should its price be just after?
Show answer
About 39 dollars; the price falls by the dividend.
A company with 50 million shares at 20 dollars uses 100 million dollars of cash, earning 3 per cent after tax, to buy back shares. Earnings before the buyback are 90 million dollars. What happens to EPS?
Show answer
It buys 5 million shares. Earnings fall by 3 million to 87 million; EPS rises from 1.80 to 87 / 45 = 1.93 dollars.
Why are firms more willing to vary buybacks than dividends?
Show answer
Investors treat dividends as a commitment and punish cuts, while buybacks are seen as discretionary.
A board thinks its shares are overvalued by about 20 per cent. Should it buy back shares?
Show answer
No. Buying above intrinsic value transfers wealth from remaining shareholders to sellers; a special dividend would be better.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.