
MBA-511 · Lesson 3 of 12 · 19 min
Valuing bonds and interest rates
Owen Tremblay's employer, Prairie Ridge Energy, is planning to issue 500 million dollars of ten-year bonds to refinance a bank loan and fund a pipeline connection. The investment bankers have proposed a coupon of 6.25 per cent, and the company's treasurer has asked Owen, who sits on the capital planning committee, to understand how the bonds will be priced and what could go wrong between now and the issue date. Dr. Varga uses the case to show that a bond is nothing more than an annuity plus a lump sum, and that its price and its yield are two ways of stating the same thing.
How a bond works
A bond is a loan sold to investors in pieces. The issuer promises to pay a fixed coupon at regular intervals, usually every six months in North America, and to repay the face value, also called par or principal, at maturity. A ten-year, 6.25 per cent bond with a face value of 1,000 dollars pays 31.25 dollars every six months for ten years and 1,000 dollars at the end. Once issued, the bond trades between investors, and its price moves as market interest rates change. The coupon is fixed; the price is not.
The price of a bond is the present value of its promised payments, discounted at the market's required yield for bonds of that maturity and risk. With semi-annual coupons, both the coupon and the yield are split into half-year periods.
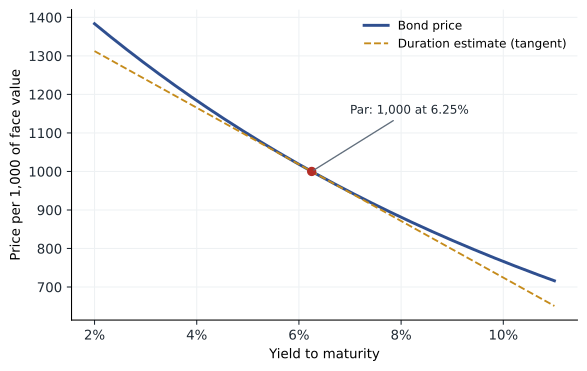
Here C is the annual coupon, F the face value, T the years to maturity and y the annual yield to maturity, quoted as twice the semi-annual rate. If investors require exactly 6.25 per cent, the bond sells at par, 1,000 dollars. If they require more, say 7 per cent, the fixed coupons are worth less and the bond sells at a discount, about 947 dollars. If they require less, it sells at a premium. Price and yield always move in opposite directions.
Yield to maturity
The yield to maturity is the single discount rate that makes the present value of a bond's promised payments equal to its market price. It is the bond equivalent of an internal rate of return. Unlike the price, it cannot be solved with a simple formula, so it is found by trial and error, which a spreadsheet or a few lines of code do instantly. The yield to maturity is the return an investor earns if the bond is held to maturity, every payment is made on time and every coupon is reinvested at the same yield. It is a promised return, not an expected one: for a risky borrower, the expected return is lower than the yield because some payments may not be made.
# Bond price, yield to maturity by bisection, and duration
def price(face, coupon_rate, years, y, freq=2):
    c = face * coupon_rate / freq
    n = int(round(years * freq))
    r = y / freq
    return sum(c / (1 + r) ** t for t in range(1, n + 1)) + face / (1 + r) ** n

def ytm(p, face, coupon_rate, years, lo=0.0, hi=1.0):
    for _ in range(200):                  # bisection: price falls as yield rises
        mid = (lo + hi) / 2
        if price(face, coupon_rate, years, mid) > p:
            lo = mid
        else:
            hi = mid
    return (lo + hi) / 2

def duration(face, coupon_rate, years, y, freq=2):
    c = face * coupon_rate / freq
    n = int(round(years * freq))
    r = y / freq
    p = price(face, coupon_rate, years, y, freq)
    t_weighted = sum((t / freq) * c / (1 + r) ** t for t in range(1, n + 1))
    t_weighted += years * face / (1 + r) ** n
    mac = t_weighted / p
    return mac, mac / (1 + r)

for y in (0.0525, 0.0625, 0.0725):
    print(f"yield {y:.2%}: price {price(1000, 0.0625, 10, y):8.2f}")
print(f"YTM if the bond trades at 947.00: {ytm(947.00, 1000, 0.0625, 10):.3%}")
mac, mod = duration(1000, 0.0625, 10, 0.0625)
print(f"Macaulay duration {mac:.2f} years, modified duration {mod:.2f}")
print(f"Approximate price change for +0.50% yield: {-mod * 0.005:.2%}")yield 5.25%: price 1077.03 yield 6.25%: price 1000.00 yield 7.25%: price 929.74 YTM if the bond trades at 947.00: 6.996% Macaulay duration 7.58 years, modified duration 7.35 Approximate price change for +0.50% yield: -3.68%
Interest rate risk and duration
Because the price of a bond moves inversely with yields, a bondholder faces interest rate risk. The sensitivity depends on how far in the future the payments are. A long bond, whose cash arrives mostly in later years, loses more value when rates rise than a short one. Duration measures this sensitivity. Macaulay duration is the weighted average time until a bond's cash flows are received, with each time weighted by the share of the bond's value received then. Modified duration, Macaulay duration divided by one plus the periodic yield, gives the approximate percentage change in price for a one-point change in yield.
The ten-year 6.25 per cent bond has a modified duration of about 7.3, so a rise in yields of half a point lowers its price by about 3.7 per cent. Because the price-yield curve is convex, the true change is slightly smaller for rises in yield and slightly larger for falls, and duration is only a first approximation for large moves. For Prairie Ridge, the practical point is that the price investors will pay depends on where yields are on the day of issue. If rates rise before the bonds are sold, the company must offer a higher coupon. Treasurers sometimes hedge this risk in advance with interest rate swaps or by locking in a rate with a forward-starting swap.
For a company, duration has a second use: matching the duration of assets and liabilities. Pension plans and insurers, which owe long-dated payments, buy long bonds so that rises and falls in rates affect both sides of the balance sheet similarly. A firm that funds a thirty-year pipeline with one-year bank loans is exposed to rising rates every year it refinances.
The term structure of interest rates
Yields differ by maturity. The yield curve plots the yields of government bonds against their maturities. In October 2026, the yield on the Government of Canada ten-year bond was close to 3.8 per cent. A normal yield curve slopes upward, because investors demand extra return for tying money up longer and bearing more interest rate risk, and because rates are expected to rise as the economy grows. An inverted curve, with short yields above long ones, has often preceded recessions, because it suggests that markets expect the central bank, here the Bank of Canada, to cut rates. Government of Canada bonds and Treasury bills form the benchmark curve against which Canadian corporate and provincial bonds are priced.
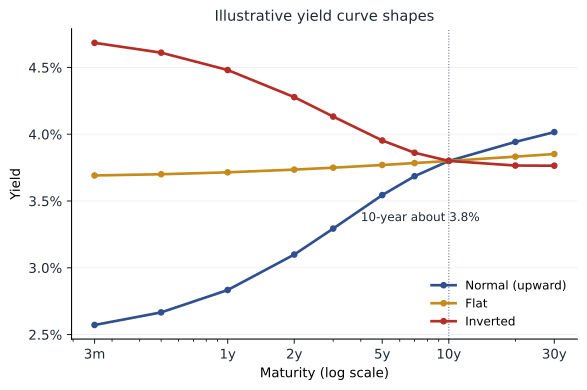
Two theories explain the shape. The expectations theory says that long yields are averages of expected future short yields, so an upward slope signals expected rate rises. The liquidity preference theory adds a term premium for bearing interest rate risk, which is why the curve usually slopes up even when rates are not expected to change. Neither theory is complete, and estimates of the term premium vary over time, but together they explain why the curve carries information about expected monetary policy and growth.
Credit risk and spreads
A corporate bond yields more than a government bond of the same maturity because it might not be repaid. The difference, the credit spread, compensates investors for expected default losses, for the uncertainty about those losses and for the lower liquidity of corporate bonds. Rating agencies classify issuers by credit quality. Bonds rated BBB or higher are investment grade; those rated below are high yield, sometimes called junk. Spreads widen sharply in recessions, when investors fear defaults, and narrow when the economy is strong.
Prairie Ridge is rated BBB by DBRS Morningstar, the Canadian rating agency, and by S&P Global. Its bankers expect a spread of about 2.4 points over Government of Canada bonds, which with a ten-year benchmark near 3.8 per cent implies a yield of about 6.2 per cent, consistent with the proposed coupon of 6.25 per cent. The bonds would be sold mainly to Canadian pension funds, insurers and bond funds, and because the company also lists its shares in New York, it could issue in US dollars if spreads were narrower there.
Bonds also carry features that change their value. A call provision lets the issuer repay early, which it will do when rates fall, so investors demand a higher yield on callable bonds. Covenants restrict the issuer's further borrowing, asset sales or dividends. Seniority and security determine who is paid first in bankruptcy: secured bonds are backed by specific assets, senior unsecured bonds rank ahead of subordinated ones. For a manager, the lesson is that the cost of debt depends on the firm's credit quality and on the terms it accepts, both of which it can influence.
Inflation-linked bonds and real yields
Governments also issue bonds whose payments rise with inflation. Real return bonds issued by the Government of Canada adjust their principal with the consumer price index, so their yield is a real yield, the return above inflation. The gap between the yield on an ordinary bond and a real return bond of similar maturity, the breakeven inflation rate, is a rough market estimate of expected inflation plus a risk premium. Ottawa stopped issuing new real return bonds in 2022, which has reduced their liquidity, but the existing bonds still trade and the concept remains useful. For a manager, the breakeven rate offers a market-based check on the inflation assumption built into a long-term forecast: if a project model assumes 4 per cent inflation while breakeven inflation is near 2 per cent, the model is probably too optimistic about future prices.
Owen notices a further use. Some of Prairie Ridge's long-term transport contracts escalate with inflation, while its bonds pay a fixed coupon. When inflation turns out higher than expected, the company's revenues rise while its debt payments do not, a natural hedge that lenders and rating agencies take into account. Matching the inflation sensitivity of assets and liabilities, like matching their duration, is part of a treasurer's job.
Worked problem
Pricing Prairie Ridge's bond after a rate move
Between the bankers' proposal and the issue date, benchmark yields rise by 0.40 points and Prairie Ridge's spread is unchanged. If the coupon stays at 6.25 per cent, what price would investors pay per 1,000 dollars of face value, and what coupon would bring the price back to par?
Show solution
- The required yield rises from 6.25 to 6.65 per cent.
- Estimate with duration: modified duration is about 7.3, so the price falls by about 7.3 times 0.40 = 2.9 per cent, to about 971 dollars.
- An exact calculation at 6.65 per cent gives a price of about 971.1 dollars, consistent with the estimate.
- To issue at par, the coupon must equal the new yield, 6.65 per cent.
Answer: Investors would pay about 971 dollars per 1,000 of face value, so a 500 million dollar face issue would raise only about 486 million. To raise the full amount at par, the coupon would rise to about 6.65 per cent, adding 2 million dollars a year in interest. This is why treasurers watch rates closely in the weeks before an issue.
Common mistakes
MistakeA bond with a 6 per cent coupon always yields 6 per cent.
InsteadThe yield depends on the price; only a bond trading at par yields its coupon rate.
MistakeYield to maturity is the return investors expect to earn.
InsteadIt is the promised return; for risky bonds the expected return is lower because of possible default.
MistakeLong and short bonds are equally affected by a change in rates.
InsteadLonger duration means greater price sensitivity to yields.
MistakeAn inverted yield curve guarantees a recession.
InsteadIt has often preceded recessions but is a signal of expectations, not a certainty.
Summary and key terms
- A bond price is the present value of its coupons and face value at the market yield.
- Price and yield move inversely; bonds trade at a premium when yields are below the coupon and at a discount when above.
- Duration measures interest rate sensitivity: the percentage price change is about minus modified duration times the change in yield.
- The yield curve shows government yields by maturity and reflects expected rates and a term premium.
- Credit spreads compensate for default risk and illiquidity, and depend on ratings, seniority and covenants.
- Coupon
- The fixed interest payment a bond makes, usually stated as an annual percentage of face value.
- Yield to maturity
- The discount rate that equates the present value of a bond's promised payments to its price.
- Duration
- A measure of the weighted average timing of a bond's cash flows and of its sensitivity to interest rates.
- Yield curve
- A graph of government bond yields against maturity.
- Credit spread
- The extra yield on a corporate bond over a government bond of the same maturity.
- Investment grade
- A credit rating of BBB or Baa or higher.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A five-year bond with a 4 per cent annual coupon paid semi-annually has a yield of 5 per cent. Is its price above or below 1,000 dollars, and roughly what is it?
Show answer
Below par, because the yield exceeds the coupon. The price is the present value of 20 dollars for 10 half-years plus 1,000 dollars at 2.5 per cent per half-year, about 956 dollars.
A bond has a modified duration of 12. Yields fall by 0.25 points. What happens to its price?
Show answer
It rises by about 12 times 0.25 = 3 per cent.
Why does a callable bond yield more than an otherwise identical non-callable bond?
Show answer
The issuer will call it when rates fall, just when the bond would have gained in value, so investors give up upside and demand compensation.
A company's ten-year bonds yield 7.1 per cent while the government ten-year yields 4.0 per cent. What is the spread, and what does it compensate for?
Show answer
The spread is 3.1 points. It compensates for expected default losses, uncertainty about defaults and lower liquidity.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.