
ACCT-311 · Lesson 9 of 12 · 25 min
Control and structured entities
Most subsidiaries are controlled the ordinary way: the parent owns most of the voting shares and elects the board. Some entities, however, are designed so that voting rights are not what determines who directs them. A securitization vehicle that buys a company's receivables, a leasing entity created to own a single building, a research partnership funded by a sponsor or an investment fund run by a manager may have little or no voting equity, and their activities are set largely by contracts drawn up when they were created. Enron's use of such entities to keep debt off its balance sheet in the 1990s led standard setters to write rules that look past voting rights to who really directs the entity and who bears its risks and rewards. This lesson explains those rules.
The IFRS 10 control model
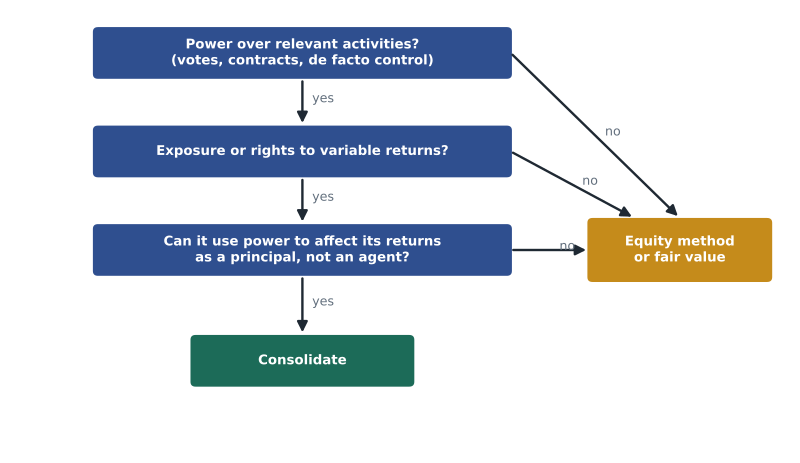
IFRS 10 applies a single control model to all investees. An investor controls an investee when it has all three of these elements: power over the investee; exposure, or rights, to variable returns from its involvement with the investee; and the ability to use its power over the investee to affect the amount of the investor's returns. The assessment is made continuously, and the investor reassesses whether it controls an investee if facts and circumstances indicate that any of the three elements has changed.
Power means existing rights that give the investor the current ability to direct the relevant activities, the activities that significantly affect the investee's returns. For a manufacturing company these are its operating and financing decisions; for a receivables vehicle they may be only the management of defaulted receivables. Rights must be substantive, meaning the holder has the practical ability to exercise them; protective rights, designed to protect the holder's interest without giving power, such as a lender's right to block a sale of assets, do not count. Potential voting rights, such as share options, are considered if they are substantive, for example if they are currently exercisable at a price that is not prohibitive.
Power can also come without a majority of votes. An investor holding a large minority stake when the remaining shares are widely dispersed among many small holders who are unlikely to organize may have de facto control. Contracts may give power, for example a management agreement that lets the investor direct a structured entity's activities. The IFRS 10 guidance also asks how the investee was designed and whether the investor was involved in that design, because involvement in setting up a structured entity often indicates that the investor has power.
Structured entities
IFRS 12 defines a structured entity as one designed so that voting or similar rights are not the dominant factor in deciding who controls it, such as when voting rights relate only to administrative tasks and the relevant activities are directed by contract. Typical features include restricted activities, a narrow and well-defined objective, insufficient equity to finance activities without subordinated support, and financing through multiple contractually linked instruments that create concentrations of credit or other risk (tranches). IFRS 10 applies the same control model to structured entities, but the analysis focuses on contracts, design and exposure to variability rather than on votes.
Worked problem
Larkspur's receivables vehicle
In 2028 Larkspur creates a trust to buy $20,000,000 of its customer receivables. The trust issues $18,400,000 of senior notes to banks and a $1,600,000 subordinated note to Larkspur, which absorbs the first losses. The trust has nominal voting equity held by a charitable trust. Larkspur services the receivables, including deciding how to work out defaulted accounts, under a servicing agreement it cannot be removed from without cause. Does Larkspur control the trust?
Show solution
- Voting rights are not the dominant factor: the trust is a structured entity whose relevant activity is managing defaults.
- Power: Larkspur directs that activity through the servicing agreement and helped design the trust.
- Variable returns: the subordinated note absorbs the first losses, a significant exposure.
- Link: Larkspur acts as principal, using its power for its own benefit as first-loss holder. It controls the trust and consolidates it, so the receivables stay on its balance sheet.
Answer: Larkspur consolidates the trust.
# Who absorbs the variability? Expected losses of a receivables vehicle (illustrative)
import statistics
scenarios = [(0.60, 0), (0.25, 300_000), (0.10, 900_000), (0.05, 2_400_000)]   # (probability, credit losses)
assets = 20_000_000
tranches = [("Larkspur subordinated note", 1_600_000), ("Bank senior notes", 18_400_000)]
expected = sum(p * l for p, l in scenarios)
print(f"Expected credit losses on {assets:,.0f} of receivables: {expected:,.0f}")
absorbed = {n: 0.0 for n, _ in tranches}
for p, loss in scenarios:
    remaining = loss
    for n, size in tranches:                      # first loss goes to the subordinated note
        take = min(remaining, size); absorbed[n] += p * take; remaining -= take
for n, v in absorbed.items():
print(f"{n:<28} expected loss absorbed {v:>10,.0f} ({v / expected:.0%})")Expected credit losses on 20,000,000 of receivables: 285,000 Larkspur subordinated note expected loss absorbed 245,000 (86%) Bank senior notes expected loss absorbed 40,000 (14%)
The expected-loss program shows why the first-loss position matters. Across the scenarios, expected credit losses are $285,000, and Larkspur's $1,600,000 subordinated note absorbs about 86 per cent of them, because it takes every loss up to $1,600,000 before the banks lose anything. Under current standards the analysis is qualitative, focusing on power and the potential significance of exposure, but quantitative work like this supports the judgement that the exposure is significant.
Principals and agents
A decision maker with power may be acting as an agent for others rather than for itself. A fund manager that directs a fund's investments under a contract with investors uses its power on their behalf. The standards look at the scope of the decision maker's authority, the rights held by others (especially rights to remove the decision maker without cause), its remuneration and whether it is commensurate with the services provided and on market terms, and its exposure to variability from other interests it holds. A manager with a market-rate fee and a small investment, who can be removed by a simple majority of independent investors, is usually an agent and does not consolidate the fund.
# Assessing control of four entities (illustrative assessments)
entities = {
    "Receivables trust": {"vote_pct": 0.00, "power_by_contract": True,  "variable_returns": "subordinated note, 8% of assets", "agent": False},
    "Fjord supplier":    {"vote_pct": 0.00, "power_by_contract": False, "variable_returns": "guarantees supplier debt",        "agent": False},
    "Sensor fund":       {"vote_pct": 0.02, "power_by_contract": True,  "variable_returns": "1% fee, 2% units",                "agent": True},
    "Prairie Labs":      {"vote_pct": 0.45, "power_by_contract": False, "variable_returns": "45% of dividends",                "agent": False},
}
dispersed_others = {"Prairie Labs": True}
for name, e in entities.items():
    power = e["vote_pct"] > 0.5 or e["power_by_contract"] or (e["vote_pct"] >= 0.40 and dispersed_others.get(name, False))
    controls = power and bool(e["variable_returns"]) and not e["agent"]
    reason = "agent, not principal" if e["agent"] else ("no power over relevant activities" if not power else "power + returns + link")
print(f"{name:<18} power={str(power):<5} consolidate={str(controls):<5} ({reason})")Receivables trust power=True consolidate=True (power + returns + link) Fjord supplier power=False consolidate=False (no power over relevant activities) Sensor fund power=True consolidate=False (agent, not principal) Prairie Labs power=True consolidate=True (power + returns + link)
The program applies a simplified version of the analysis. Larkspur consolidates the receivables trust (power by contract plus first-loss exposure) and Prairie Labs, where its 45 per cent stake gives de facto control because the other shareholders are widely dispersed. It does not consolidate the sensor fund, where it acts as an agent, or the Fjord supplier, where a guarantee gives it exposure but no power over the supplier's activities. Real assessments involve more facts and judgement, and IFRS and US GAAP can reach different answers on de facto control.
US GAAP generally does not recognize de facto control under the voting interest model: a large minority holding without majority voting rights or contractual control usually leads to the equity method, not consolidation. This is one of the clearest practical differences between IFRS 10 and ASC 810.
Investment entities
IFRS 10 contains an exception for investment entities, such as venture capital and private equity funds, that obtain funds from investors to provide investment management services, commit to investing solely for capital appreciation or investment income, and measure and evaluate substantially all investments on a fair value basis. An investment entity does not consolidate its controlled investees; it measures them at fair value through profit or loss. The exception does not carry up to a parent that is not itself an investment entity, which must consolidate all entities it controls, including those held through an investment entity subsidiary.
Private company and other options
Canadian private enterprises applying ASPE define a subsidiary by reference to the continuing power to determine strategic operating, investing and financing policies without the co-operation of others (Section 1591), and the Handbook also includes guidance on variable interest entities. Because ASPE lets a private enterprise account for subsidiaries by the equity or cost method instead of consolidating, the practical consequences of a control conclusion are smaller than for IFRS reporters; readers should check the current Handbook for how the policy choice applies to particular arrangements.
| Issue | IFRS 10 | ASC 810 |
|---|---|---|
| Models | Single control model | VIE model, then voting interest model |
| De facto control with large minority stake | Can lead to consolidation | Generally not, under the voting model |
| Potential voting rights | Considered if substantive | Generally not considered unless exercised |
| Principal versus agent | Explicit guidance | Guidance on fees as variable interests and kick-out rights |
| Investment entity subsidiaries | Fair value exception does not carry to a non-investment parent | Fair value retained in parent's consolidation |
| Private company relief | Not applicable (ASPE has its own options) | Common-control VIE alternative |
Why it matters
Whether a structured entity is consolidated changes reported assets, debt and ratios, sometimes dramatically. Securitizations kept off the balance sheet before 2008 hid exposures that returned to banks' balance sheets during the financial crisis. Current rules bring most sponsor-designed vehicles onto the sponsor's balance sheet, and disclosures about unconsolidated structured entities and VIEs, including the maximum exposure to loss, tell users about risks that remain off balance sheet.
Disclosures about involvement with other entities
IFRS 12 requires disclosure of the significant judgements and assumptions made in deciding whether the entity controls, jointly controls or significantly influences another entity, the interests of NCI in group activities, restrictions on using group assets, and the nature of and risks associated with interests in consolidated and unconsolidated structured entities, including the maximum exposure to loss and any financial support provided without a contractual obligation. These disclosures let users see the judgements behind the consolidation boundary.
Common mistakes
MistakeAssuming no voting shares means no consolidation.
InsteadPower can come from contracts and design; first-loss holders that direct key activities usually consolidate.
MistakeCounting protective rights as power.
InsteadOnly substantive rights to direct relevant activities give power; protective rights do not.
MistakeTreating every decision maker as a principal.
InsteadAssess removal rights, remuneration and other interests; many managers are agents.
MistakeIgnoring de facto control.
InsteadA large minority stake with dispersed other holders can give control under IFRS 10.
MistakeConcluding that an investment entity parent's fair value exception carries to its non-investment parent.
InsteadUnder IFRS 10 the non-investment parent consolidates all controlled entities.
Summary and key terms
- IFRS 10 uses one control model: power, exposure to variable returns, and the link between them.
- Power comes from substantive rights to direct relevant activities; protective rights do not give power.
- Structured entities are designed so that votes are not the dominant factor; contracts and design matter.
- Large minority stakes can give de facto control under IFRS 10.
- Decision makers acting as agents for others do not consolidate.
- Investment entities measure controlled investees at fair value instead of consolidating.
- Consolidation decisions on structured entities can change reported debt and ratios significantly.
- Structured entity
- An entity designed so that voting rights are not the dominant factor in deciding who controls it.
- De facto control
- Control arising from a large minority holding when other holdings are widely dispersed.
- Relevant activities
- The activities of an investee that significantly affect its returns.
- Substantive right
- A right the holder has the practical ability to exercise.
- Protective right
- A right designed to protect the holder's interest without giving power over the investee.
- Principal
- A decision maker using power primarily for its own benefit.
- Agent
- A decision maker using power on behalf of others.
- Investment entity
- An entity that invests for returns from capital appreciation or income and measures investments at fair value.
- Securitization
- Transferring financial assets to a vehicle that funds them by issuing notes.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A vehicle's only relevant activity is managing defaulted loans, done by a servicer that holds the first-loss tranche. Who controls it?
Show answer
The servicer, if it cannot be removed without cause and acts as principal.
A lender can block the sale of a borrower's main asset. Power?
Show answer
No; it is a protective right.
An investor holds 42 per cent; the rest is spread among thousands of holders who rarely vote. Control under IFRS 10?
Show answer
Possibly; this may be de facto control.
A fund manager earns a market fee, owns 1 per cent of units and can be removed by a simple majority of investors. Principal or agent?
Show answer
Agent; it does not consolidate the fund.
Rerun the expected-loss program with a subordinated note of $800,000 and senior notes of $19,200,000. Share absorbed by the subordinated note?
Show answer
About 68 per cent.
Name two features of a structured entity.
Show answer
Restricted activities, narrow objective, insufficient equity, tranched financing (any two).
Can an investment entity parent's fair value treatment carry up to a non-investment parent under IFRS 10?
Show answer
No.
Why did standard setters tighten rules after Enron?
Show answer
Special purpose entities were used to keep debt and losses off sponsors' balance sheets.
Rerun the control program setting Prairie Labs' other holders as concentrated. Result?
Show answer
Prairie Labs is no longer consolidated; power is lacking.
What disclosure helps users assess unconsolidated structured entities?
Show answer
The nature of involvement and the maximum exposure to loss.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.