
ACCT-311 · Lesson 12 of 12 · 30 min
Partnerships, trusts and segment reporting
The course has concentrated on corporations and their investments, but many businesses are organized as partnerships, especially in professional services, and trusts hold assets for beneficiaries in estates, pension plans and investment vehicles. This final lesson covers the accounting that is distinctive to partnerships (formation, sharing profit, changes in partners and liquidation), introduces trusts, and then returns to the Larkspur group to see how segment reporting tells users what a consolidated group is made of. It ends by drawing the course together.
Partnerships
A partnership is the relation between persons carrying on a business in common with a view to profit, governed in Canada by provincial partnership statutes and the partnership agreement. In a general partnership each partner is personally liable for the partnership's debts; in a limited partnership, limited partners' liability is restricted to their investment, provided they do not take part in management; and limited liability partnerships, available to professionals such as accountants and lawyers in most provinces, shield partners from liability for other partners' negligence. A partnership is not a taxable entity: its income is allocated to the partners and taxed in their hands, and many partnerships file an annual information return (form T5013). Partnerships generally report under ASPE, which has no special partnership standard, so the distinctive accounting is in the owners' equity section.
Each partner has a capital account, credited with contributions and their share of profit and debited with withdrawals (drawings) and their share of losses. Non-cash contributions are recorded at their fair value at the date of contribution, because the partners have bargained over that value; a partner who contributes land worth $300,000 that cost $120,000 is credited with $300,000. Liabilities assumed by the partnership reduce the contributing partner's credit.
Sharing profit
The partnership agreement sets how profit and losses are shared. Without an agreement, partnership law generally divides them equally. Agreements often recognize differences in what partners contribute: salary allowances for partners who work more, interest on capital for those who invest more, and a residual ratio for whatever remains. Salary allowances and interest are not expenses of the partnership; they are steps in dividing profit, and they apply even if profit is too small to cover them, in which case the shortfall is shared in the residual ratio.
Worked problem
Moraine Advisory
Ada, Ben and Cleo are partners in Moraine Advisory, an invented consulting firm. The agreement gives Ada a salary allowance of $60,000 and Ben $40,000, 5 per cent interest on opening capital (Ada $200,000, Ben $150,000, Cleo $250,000), and divides the remainder 40:30:30. Divide profit of $180,000 and then of $100,000.
Show solution
- Salaries total $100,000 and interest $30,000 (10,000; 7,500; 12,500), so $130,000 is allocated before the residual.
- Profit $180,000: residual $50,000, shared 20,000; 15,000; 15,000. Ada 90,000; Ben 62,500; Cleo 27,500.
- Profit $100,000: residual −$30,000, shared −12,000; −9,000; −9,000. Ada 58,000; Ben 38,500; Cleo 3,500.
- The allowances are applied in full in both cases; the shortfall in the second case reduces each partner's share.
Answer: Ada 90,000, Ben 62,500, Cleo 27,500; then 58,000, 38,500 and 3,500.
# Dividing partnership profit: salaries, interest on capital, then a residual ratio (illustrative)
partners = {"Ada": {"capital": 200_000, "salary": 60_000, "ratio": 0.40},
            "Ben": {"capital": 150_000, "salary": 40_000, "ratio": 0.30},
            "Cleo": {"capital": 250_000, "salary": 0, "ratio": 0.30}}
rate = 0.05                                   # interest on opening capital
def divide(profit):
    out = {}
    fixed = sum(p["salary"] + rate * p["capital"] for p in partners.values())
    residual = profit - fixed                 # may be negative: shared in the ratio anyway
    for name, p in partners.items():
        out[name] = round(p["salary"] + rate * p["capital"] + residual * p["ratio"])
    return residual, out
for profit in (180_000, 100_000):
    residual, out = divide(profit)
print(f"Profit {profit:>9,}: residual {residual:>9,.0f} " + " ".join(f"{n} {v:,}" for n, v in out.items()))Profit 180,000: residual 50,000 Ada 90,000 Ben 62,500 Cleo 27,500 Profit 100,000: residual -30,000 Ada 58,000 Ben 38,500 Cleo 3,500
Admitting and withdrawing partners
A new partner can join in two ways. Buying an interest from an existing partner is a private transaction between them: the partnership simply transfers capital from the seller's account to the buyer's, whatever price is paid. Investing in the partnership increases its assets and total capital. When the new partner pays more than the book value of the interest received, the excess is usually treated as a bonus to the existing partners, credited to their capital in the residual ratio. Some partnerships instead record goodwill implied by the price, but because internally generated goodwill is not recognized under general-purpose accounting standards, the bonus method is more common.
Worked problem
Admitting Dev
Moraine's partners' capital totals $600,000 when Dev invests $200,000 cash for a 20 per cent interest in capital and profit. Record the admission by the bonus method and show what the goodwill method would record.
Show solution
- New total capital: 600,000 + 200,000 = 800,000. Dev's 20 per cent: 160,000.
- Bonus to existing partners: 200,000 − 160,000 = 40,000, shared 40:30:30: Ada 16,000; Ben 12,000; Cleo 12,000.
- Entry: Dr Cash 200,000; Cr Dev, capital 160,000; Cr Ada, Ben and Cleo, capital 40,000.
- Goodwill method: implied value 200,000 ÷ 0.20 = 1,000,000; goodwill 1,000,000 − 800,000 = 200,000 credited to existing partners 80,000; 60,000; 60,000; Dev's capital 200,000.
Answer: Bonus method: Dev 160,000 and a 40,000 bonus to the existing partners.
When a partner retires, the partnership pays out the capital balance, usually after revaluing assets to fair value so the retiring partner shares in unrecognized gains. Paying more than the capital balance is a bonus to the retiring partner, charged to the remaining partners in their ratio; paying less is a bonus to the remaining partners.
Liquidation
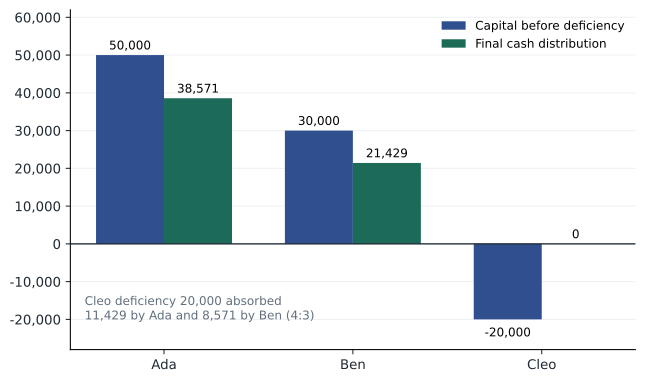
When a partnership ends, it sells its assets (realization), pays creditors, shares gains and losses on realization in the profit ratio, and distributes remaining cash according to the partners' capital balances, not their profit ratio. If a partner's capital becomes negative, that partner must contribute cash to cover the deficiency; if they cannot, the deficiency is absorbed by the other partners in their relative profit ratio. Because the order and amounts of realization are uncertain, partnerships distributing cash in instalments prepare a safe payments schedule that assumes all unsold assets are worthless and no deficient partner will pay, so no partner is paid cash that might later have to be returned.
# Liquidation: a partner with a capital deficiency who cannot pay (illustrative)
capital = {"Ada": 50_000, "Ben": 30_000, "Cleo": -20_000}   # after realizing assets and paying creditors
ratio = {"Ada": 0.40, "Ben": 0.30, "Cleo": 0.30}
deficit = {n: -c for n, c in capital.items() if c < 0}
solvent = [n for n in capital if capital[n] > 0]
for d, amt in deficit.items():
    share = sum(ratio[n] for n in solvent)
    for n in solvent:
        capital[n] -= amt * ratio[n] / share  # absorbed in the solvent partners' relative ratio
    capital[d] = 0
cash = sum(v for v in capital.values())
for n, v in capital.items():
    print(f"{n:<5} final cash distribution {v:>10,.0f}")
print(f"Cash available {cash:,.0f}")Ada final cash distribution 38,571 Ben final cash distribution 21,429 Cleo final cash distribution 0 Cash available 60,000
In the program, Cleo's $20,000 deficiency is shared by Ada and Ben in their relative ratio of 40:30, so Ada absorbs $11,429 and Ben $8,571, leaving Ada $38,571 and Ben $21,429 of the $60,000 cash. If Cleo later pays, Ada and Ben recover their shares. Creditors are paid before partners, and personal creditors of a partner have prior claim on that partner's personal assets in many jurisdictions.
Trusts
A trust is a relationship in which a trustee holds property for the benefit of beneficiaries under terms set by the settlor. Accountants meet trusts in estates, family trusts, pension plans and investment funds. A trustee accounts to beneficiaries, often distinguishing capital (corpus) from income because the beneficiaries entitled to each may differ; the trust deed and provincial trust law govern that division. Trusts file T3 returns and are generally taxed on income not distributed to beneficiaries. Publicly traded income trusts, popular in Canada in the early 2000s, were largely converted to corporations after the specified investment flow-through (SIFT) rules took full effect in 2011. Under IFRS, units of a trust that must distribute its income or that holders can put back to the trust are financial liabilities unless the narrow puttable instrument exception in IAS 32 applies, which affects how many real estate investment trusts present their equity.
Whether a trust is consolidated by someone else is a control question from lesson 9: a sponsor that directs a trust's relevant activities and is exposed to its variable returns may have to consolidate it, as Larkspur did with its receivables trust.
Segment reporting
A consolidated statement adds together businesses with very different prospects. IFRS 8 Operating Segments requires listed entities to disclose information about their operating segments using the management approach: segments are the components whose operating results are regularly reviewed by the chief operating decision maker (CODM) to allocate resources and assess performance, and the amounts disclosed are those the CODM uses, reconciled to the consolidated totals. Segments may be aggregated if they have similar economic characteristics. A segment is reportable if its revenue (external and intersegment), its absolute profit or loss, or its assets are 10 per cent or more of the combined amounts; if reportable segments' external revenue is less than 75 per cent of the entity's revenue, more segments must be reported. IFRS 18, effective for annual periods beginning on or after 1 January 2027, adds requirements for management-defined performance measures but leaves the segment model intact. ASPE has no segment reporting requirement.
Worked problem
Larkspur's segments
By 2027 Larkspur's CODM, its chief executive, reviews five operating segments: Sensors, Controls (Blue Heron), Optics (Osprey), Service contracts and Software. Using the figures in the program below, which segments are reportable?
Show solution
- Combined revenue including intersegment sales is $22.1 million, so the revenue threshold is $2.21 million: Sensors, Controls and Optics pass.
- Combined profit of profitable segments is $3.42 million, exceeding combined losses of $0.25 million, so the profit threshold is $342,000: Service ($140,000) and Software (a $250,000 loss) fail.
- Combined assets are $27.3 million, so the asset threshold is $2.73 million: Service and Software fail.
- Reportable segments' external revenue is $19.6 million, 92.9 per cent of $21.1 million, so the 75 per cent test is met; Service and Software are combined as all other segments.
Answer: Sensors, Controls and Optics are reportable.
# Which operating segments are reportable? The 10% and 75% tests (illustrative, $ thousands)
seg = {"Sensors":  (12_000, 300, 1_900, 16_000),     # external revenue, intersegment revenue, profit, assets
       "Controls": (3_500,  500,   860,  5_800),
       "Optics":   (4_100,    0,   520,  4_000),
       "Service":  (900,      0,   140,    600),
       "Software": (600,    200,  -250,    900)}
rev = sum(e + i for e, i, _, _ in seg.values())
prof = max(sum(p for _, _, p, _ in seg.values() if p > 0), -sum(p for _, _, p, _ in seg.values() if p < 0))
assets = sum(a for *_, a in seg.values())
reportable = []
for name, (e, i, p, a) in seg.items():
    tests = [(e + i) >= 0.1 * rev, abs(p) >= 0.1 * prof, a >= 0.1 * assets]
    if any(tests): reportable.append(name)
    print(f"{name:<9} revenue {(e + i) / rev:5.1%}  profit {abs(p) / prof:5.1%}  assets {a / assets:5.1%}  reportable={any(tests)}")
ext = sum(seg[n][0] for n in reportable) / sum(e for e, *_ in seg.values())
print(f"External revenue of reportable segments: {ext:.1%} (must be at least 75%)")Sensors revenue 55.7% profit 55.6% assets 58.6% reportable=True Controls revenue 18.1% profit 25.1% assets 21.2% reportable=True Optics revenue 18.6% profit 15.2% assets 14.7% reportable=True Service revenue 4.1% profit 4.1% assets 2.2% reportable=False Software revenue 3.6% profit 7.3% assets 3.3% reportable=False External revenue of reportable segments: 92.9% (must be at least 75%)
Entity-wide disclosures apply even to an entity with a single segment: revenue by product and service, revenue and non-current assets by geographic area (domestic and all foreign countries, with material individual countries shown separately), and reliance on major customers, being any customer providing 10 per cent or more of revenue, with the segment concerned but not the customer's name.
Bringing the course together
| Investee | Relationship | IFRS treatment | Lesson |
|---|---|---|---|
| Listed share portfolio | Passive | Fair value through profit or loss or OCI election | 1 |
| Cedar Point (30 per cent, then 70) | Significant influence, then control | Equity method, then step acquisition | 2, 8 |
| Northgate | Joint venture | Equity method | 2 |
| Blue Heron (80 per cent) | Control | Consolidation with NCI | 3–8 |
| Receivables trust | Structured entity | Consolidation | 9 |
| Osprey Instruments | Foreign subsidiary | Translation, then consolidation | 10–11 |
| Moraine Advisory | Outside the group | Partnership accounting | 12 |
The common thread is that the accounting follows the economic relationship: passive investments are measured at fair value, significant influence leads to the equity method, control leads to consolidation regardless of legal form, and foreign operations are translated in a way that reflects how their cash flows affect the parent. Judgements about influence, control and functional currency drive everything else, which is why they receive extensive disclosure. ACCT-470 applies these judgements to complex cases, and ACCT-412 covers public sector and not-for-profit organizations, which have their own standards on controlled and related entities.
Common mistakes
MistakeTreating partner salary allowances as expenses of the partnership.
InsteadThey are steps in dividing profit and are applied even when profit is insufficient.
MistakeRecording a purchase of an interest from an existing partner at the price paid.
InsteadThe partnership only transfers the seller's capital balance; the price is private.
MistakeDistributing liquidation cash in the profit ratio.
InsteadCash is distributed according to final capital balances after sharing gains, losses and deficiencies.
MistakeDefining segments by legal entity or by what outsiders expect.
InsteadSegments follow the internal reports the CODM uses.
MistakeIgnoring intersegment revenue in the 10 per cent revenue test.
InsteadThe revenue test uses external plus intersegment revenue; the 75 per cent test uses external revenue only.
Summary and key terms
- Partners' capital accounts record contributions at fair value, shares of profit and drawings.
- Profit is shared under the agreement: salary allowances and interest, then a residual ratio, even if this creates a residual loss.
- New partners may buy an interest privately or invest; bonuses go to existing or new partners in the residual ratio.
- Liquidation distributes cash by capital balances; deficiencies are absorbed by solvent partners in their relative ratio.
- Trusts separate capital and income for beneficiaries; puttable trust units are often liabilities under IAS 32.
- IFRS 8 uses the management approach with 10 per cent and 75 per cent tests.
- Influence, control and functional currency judgements determine the accounting throughout the course.
- Settlor
- The person who creates a trust and transfers property to it.
- Partnership
- Persons carrying on a business in common with a view to profit.
- Capital account
- A partner's equity, increased by contributions and profit and reduced by drawings and losses.
- Bonus method
- Recording admission or retirement by reallocating capital rather than recognizing goodwill.
- Capital deficiency
- A negative capital balance that the partner must make good.
- Safe payments schedule
- An instalment distribution plan assuming unsold assets are worthless.
- Chief operating decision maker
- The function that allocates resources to and assesses the performance of segments.
- Operating segment
- A component whose results the CODM reviews regularly and for which discrete information is available.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Rerun the profit-sharing program for profit of $250,000. Ada's share?
Show answer
$118,000.
In the same rerun, Cleo's share?
Show answer
$48,500.
A partner contributes equipment that cost $90,000 with fair value $70,000. Capital credit?
Show answer
$70,000.
Dev pays Ada $150,000 for half of her $200,000 capital. Entry?
Show answer
Dr Ada, capital 100,000; Cr Dev, capital 100,000.
Moraine's capital is $600,000; Eve invests $120,000 for a 20 per cent interest. Bonus?
Show answer
A bonus of $24,000 to Eve: 20 per cent of $720,000 is $144,000.
Rerun the liquidation program with Cleo's capital at −$35,000. Ada's final cash?
Show answer
About $30,000 (50,000 − 20,000).
Why prepare a safe payments schedule?
Show answer
So no partner receives cash that may later have to be returned.
Rerun the segment program with Service external revenue of 2,400. Is Service reportable?
Show answer
Yes; its revenue is about 10.2 per cent of the new combined revenue.
A customer provides 12 per cent of revenue. What must be disclosed?
Show answer
That fact, the amount and the segment, but not the customer's name.
What standard governs Canadian private enterprise partnerships' segment disclosure?
Show answer
None; ASPE has no segment requirement.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.