
ACCT-311 · Lesson 1 of 12 · 27 min
Intercorporate investments: an overview
Companies rarely stand alone. A Canadian manufacturer may own a few shares of a supplier, a third of a technology start-up, half of a joint venture with a competitor and all of a distribution company in the United States. Each of these holdings raises the same question for the accountant: how should the investor's financial statements show an investment in another entity? The answer depends on how much influence the investor has over the investee, and it ranges from carrying a few shares at fair value to combining the investee's assets, liabilities, revenues and expenses line by line with the investor's own. This course, Advanced Financial Accounting, is about that range. It builds on ACCT-211 and ACCT-212, which covered individual assets, liabilities and equity, and moves to groups of entities, foreign operations and other complex reporting situations.
Throughout the course we follow one invented group. Larkspur Holdings Ltd., a Calgary maker of industrial sensors with a December year end, reports under IFRS. In 2026 it holds a small portfolio of listed shares, buys 30 per cent of an analytics company, forms a joint venture and acquires 80 per cent of a controls manufacturer, Blue Heron Controls. Later it acquires a US subsidiary, Osprey Instruments Inc., whose functional currency is the US dollar. Where Canadian private enterprises would account differently under Accounting Standards for Private Enterprises (ASPE), we say so. All company names and figures are invented and illustrative.
Why companies invest in other companies
Intercorporate investments serve different purposes. Some are passive: a company with surplus cash buys shares of listed companies to earn dividends and price gains until it needs the money. Others are strategic. An investor may buy enough shares to win a seat on a supplier's board and secure a reliable source of components, or it may form a joint venture to share the cost and risk of entering a new market. At the far end, an investor buys control of another company to expand capacity, acquire technology, enter a new region or remove a competitor. The purpose often predicts the accounting, but the standards look at the substance of the relationship, not management's intention alone.
Ownership can be direct or indirect. A parent may own a subsidiary that in turn owns another company, creating a chain of control. Ownership may be held through common shares, through other instruments such as options and convertible debt that could become shares, or through contracts that give one party the power to direct another entity's activities without owning shares at all. The accounting framework must handle all of these.
The spectrum of influence
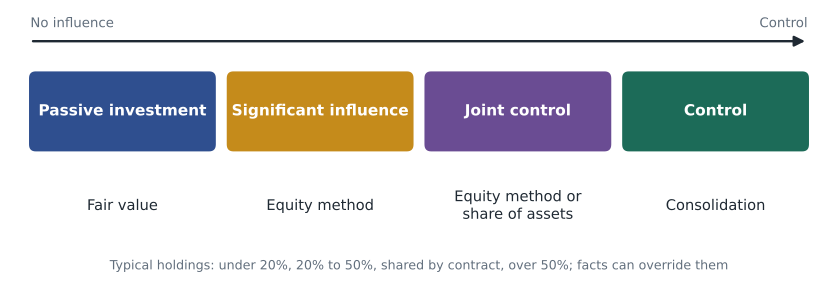
The standards sort investments into four broad categories according to the investor's ability to affect the investee's decisions. Passive investments give the investor no significant influence. Investments in associates give significant influence: the power to participate in, but not control, the investee's financial and operating policy decisions. Joint arrangements involve joint control, where decisions about the relevant activities require the unanimous consent of the parties sharing control. Subsidiaries are controlled: the investor has power over the investee, exposure or rights to variable returns, and the ability to use its power to affect those returns.
| Relationship | Typical ownership | Key concept | Accounting under IFRS |
|---|---|---|---|
| Passive investment | Under 20 per cent | No significant influence | Fair value through profit or loss, or through OCI if elected (IFRS 9) |
| Associate | 20 to 50 per cent | Significant influence | Equity method (IAS 28) |
| Joint venture | Shared | Joint control, rights to net assets | Equity method (IFRS 11, IAS 28) |
| Joint operation | Shared | Joint control, rights to assets and obligations | Recognize own share of assets, liabilities, revenues and expenses |
| Subsidiary | Over 50 per cent, or control by other means | Control | Consolidation (IFRS 10) |
The percentages are presumptions, not rules. Owning 20 per cent or more of the voting power is presumed to give significant influence unless it can be clearly shown otherwise, and owning less than 20 per cent is presumed not to, unless influence can be clearly shown. Evidence of significant influence includes representation on the board, participation in policy-making, material transactions between the investor and investee, interchange of managerial personnel and provision of essential technical information. An investor with 15 per cent and two of nine board seats may have significant influence; an investor with 25 per cent whose investee is controlled by a hostile majority shareholder that ignores it may not.
Passive investments
Under IFRS 9, an investment in equity instruments without significant influence is measured at fair value. Changes in fair value go to profit or loss unless, at initial recognition, the investor makes an irrevocable election, instrument by instrument, to present them in other comprehensive income (FVOCI). The election is available only for equity instruments that are not held for trading. Gains and losses in OCI are never recycled to profit or loss, even when the shares are sold; the cumulative amount may be transferred within equity to retained earnings. Dividends are recognized in profit or loss in either case. Investments in debt instruments are measured at amortized cost, at FVOCI with recycling, or at fair value through profit or loss (FVTPL), depending on the business model and the contractual cash flow characteristics.
Canadian private enterprises applying ASPE Section 3856 measure equity investments quoted in an active market at fair value with changes in net income; other equity investments are measured at cost less impairment. Section 3051 applies to investments subject to significant influence.
Worked problem
Passive investment in listed shares
On 3 February 2026 Larkspur buys 10,000 shares of a listed supplier at $42 a share. At 31 December 2026 the share price is $47, and Larkspur received dividends of $1.20 a share during the year. Show the effect on 2026 profit under each IFRS 9 option.
Show solution
- Cost: 10,000 × $42 = $420,000. Fair value at year end: 10,000 × $47 = $470,000.
- Dividend income: 10,000 × $1.20 = $12,000, recognized in profit in all cases.
- FVTPL: profit includes the $50,000 gain plus $12,000 dividends, $62,000 in total.
- FVOCI election: profit includes only the $12,000 dividends; the $50,000 gain goes to OCI and is never recycled.
Answer: Profit of $62,000 under FVTPL or $12,000 under FVOCI; the investment is $470,000 either way.
Significant influence and the equity method in brief
When an investor has significant influence, fair value no longer tells the whole story, and the cost method would let the investor manipulate income by influencing the timing of dividends. The equity method, covered in lesson 2, recognizes the investor's share of the investee's profit or loss as it is earned. The investment starts at cost, increases by the investor's share of profit, decreases by its share of losses and by dividends received, and is adjusted for the amortization of any excess of cost over the investor's share of the carrying amounts, and for unrealized profits on transactions between the two. The equity method is sometimes called one-line consolidation, because it produces the same profit attributable to the investor as consolidation would, but presents it in a single line.
Control and consolidation in brief
Control triggers consolidation. Under IFRS 10, an investor controls an investee when it has power over the investee, exposure or rights to variable returns from its involvement, and the ability to use its power to affect the amount of those returns. Power usually comes from a majority of voting rights, but it can come from contracts, from potential voting rights that are substantive, or from holding a large minority stake when the other shareholders are widely dispersed (de facto control). Consolidated financial statements present the parent and its subsidiaries as a single economic entity: all of the subsidiary's assets, liabilities, income and expenses are combined with the parent's, intragroup balances and transactions are eliminated, and the portion of the subsidiary not owned by the parent is shown as non-controlling interest (NCI) within equity.
ASPE is different. A Canadian private enterprise may choose, as an accounting policy applied to all subsidiaries, to consolidate them (Section 1601) or to account for them using the equity method or the cost method (Section 3051), with fair value required for subsidiaries whose shares are quoted in an active market if the cost method is chosen. A similar choice exists for significantly influenced investees (equity or cost method) and for interests in joint arrangements. This reflects the view that users of private company statements, often lenders and owners with access to more detailed information, may not need consolidated figures.
Business combinations
A business combination is a transaction or event in which an acquirer obtains control of one or more businesses. It can happen by buying shares, which creates a parent–subsidiary relationship, or by buying net assets directly, in which case the acquirer records the assets and liabilities in its own books and there is no subsidiary to consolidate. Both are accounted for using the acquisition method, covered in lesson 3: identify the acquirer, determine the acquisition date, recognize and measure the identifiable assets acquired, liabilities assumed and any non-controlling interest, and recognize goodwill or a gain on a bargain purchase.
# Classifying Larkspur's investments by influence (illustrative assessments)
holdings = [
    ("Listed supplier shares", 0.02, "no board seat", "passive"),
    ("Cedar Point Analytics", 0.30, "2 of 7 board seats", "significant influence"),
    ("Northgate JV", 0.50, "unanimous consent on budgets", "joint control"),
    ("Blue Heron Controls", 0.80, "majority of board", "control"),
    ("Data partner", 0.15, "1 board seat, key technology rights", "significant influence"),
]
method = {"passive": "fair value", "significant influence": "equity method",
          "joint control": "equity method (joint venture)", "control": "consolidate"}
print(f"{'Investee':<26}{'Owned':>7}  {'Evidence':<38}{'Method'}")
for name, pct, evidence, rel in holdings:
print(f"{name:<26}{pct:>7.0%} {evidence:<38}{method[rel]}")Investee Owned Evidence Method Listed supplier shares 2% no board seat fair value Cedar Point Analytics 30% 2 of 7 board seats equity method Northgate JV 50% unanimous consent on budgets equity method (joint venture) Blue Heron Controls 80% majority of board consolidate Data partner 15% 1 board seat, key technology rights equity method
The last row of the program's output makes the point about presumptions: a 15 per cent holding is accounted for by the equity method because the board seat and the technology rights give Larkspur significant influence. The ownership percentage is the starting point for judgement, not the end of it.
Why consolidation matters to users
Imagine Larkspur reported its 80 per cent interest in Blue Heron as a single investment line. Its balance sheet would hide Blue Heron's debt, its inventory, its plant and its customer receivables, and its income statement would hide Blue Heron's revenue and expenses. A lender assessing Larkspur's leverage, or an investor estimating its growth, would see only a fraction of the resources the group controls. Consolidation shows the full scale of the economic entity that management directs, while the NCI line shows how much of the subsidiary's net assets belongs to outside shareholders. Separate financial statements of the parent alone, prepared for legal or tax purposes, can still be issued, but they are not a substitute for consolidated statements under IFRS or US GAAP.
Consolidation also has limits. Creditors of a subsidiary generally have claims only against that subsidiary, not against the parent, unless the parent has guaranteed the debt. Dividends from subsidiaries may be restricted by local law, loan covenants or foreign exchange controls. Consolidated figures can therefore overstate the cash the parent can actually reach, which is why segment disclosures (lesson 12) and disclosures about restrictions on subsidiaries matter.
Disclosure
IFRS 12, Disclosure of Interests in Other Entities, requires information that helps users evaluate the nature of, and risks associated with, an entity's interests in subsidiaries, joint arrangements, associates and unconsolidated structured entities, and the effects of those interests on its financial position, performance and cash flows. It covers significant judgements about control, joint control and significant influence; the composition of the group; subsidiaries with material NCI; significant restrictions on access to assets; summarized financial information for material joint ventures and associates; and risks from unconsolidated structured entities. IFRS 18, which applies from 1 January 2027, changes the structure of the statement of profit or loss, including where the share of profit of equity-accounted investees is presented; it is noted where relevant in later lessons.
Looking ahead
The rest of the course follows the spectrum from left to right. Lesson 2 covers the equity method and joint arrangements. Lessons 3 to 9 cover business combinations and consolidation: the acquisition method, consolidation at and after acquisition, intercompany transactions, changes in ownership and control through contracts and structured entities. Lessons 10 and 11 deal with foreign currency, and lesson 12 covers partnerships, segment reporting and a capstone consolidation of the whole group. Not-for-profit and public sector reporting are covered separately in ACCT-412.
Common mistakes
MistakeTreating 20 per cent ownership as an automatic line between methods.
InsteadThe 20 per cent threshold is a rebuttable presumption; look at board representation, transactions and other evidence of influence.
MistakeRecycling FVOCI equity gains to profit when the shares are sold.
InsteadUnder IFRS 9, gains on equity investments designated at FVOCI are never recycled; they may be transferred within equity.
MistakeAssuming a parent needs a majority of shares to have control.
InsteadControl can arise from contracts, substantive potential voting rights or de facto control with a large minority stake.
MistakeThinking consolidation means the parent owns the subsidiary's assets outright.
InsteadConsolidation reports the economic entity the parent controls; outside owners' share is shown as non-controlling interest, and the subsidiary's creditors usually have claims only against the subsidiary.
MistakeIgnoring the reporting framework when comparing groups.
InsteadASPE lets private enterprises use the equity or cost method for subsidiaries instead of consolidating.
Summary and key terms
- The accounting for an intercorporate investment depends on the investor's influence over the investee.
- Passive equity investments are measured at fair value, through profit or loss or, by irrevocable election, through OCI without recycling.
- Significant influence, presumed at 20 per cent or more of voting power, leads to the equity method.
- Joint ventures are equity-accounted; joint operators recognize their own share of assets, liabilities, revenues and expenses.
- Control under IFRS 10 combines power, exposure to variable returns and the link between them, and leads to consolidation.
- Consolidated statements present the parent and subsidiaries as one economic entity, with non-controlling interest in equity.
- ASPE allows private enterprises to account for subsidiaries by the equity or cost method instead of consolidating.
- FVOCI election
- An irrevocable IFRS 9 election to present fair value changes on a non-trading equity investment in other comprehensive income without recycling.
- Associate
- Under IAS 28, an entity over which the investor has significant influence.
- Intercorporate investment
- A holding of shares or other interests in another entity.
- Significant influence
- The power to participate in, but not control or jointly control, an investee's financial and operating policy decisions.
- Joint control
- The contractually agreed sharing of control, where decisions about relevant activities require unanimous consent of the parties sharing control.
- Control
- Power over an investee, with exposure or rights to variable returns and the ability to use the power to affect those returns.
- Subsidiary
- An entity controlled by another entity, its parent.
- Consolidated financial statements
- Statements presenting a parent and its subsidiaries as a single economic entity.
- Non-controlling interest
- The equity in a subsidiary not attributable, directly or indirectly, to the parent.
- Business combination
- A transaction or event in which an acquirer obtains control of one or more businesses.
Practice problems
Work each problem on paper first, then reveal the answer to check.
An investor owns 18 per cent, appoints two of seven directors and supplies key technology. Method?
Show answer
Probably the equity method; significant influence is evident despite owning under 20 per cent.
An investor owns 35 per cent, but the 65 per cent holder ignores it and it has no board seat. Method?
Show answer
The presumption of significant influence may be rebutted; fair value accounting may apply.
Shares bought for $80,000 are worth $95,000 at year end, with $3,000 of dividends. Profit under FVTPL?
Show answer
$18,000: a $15,000 gain plus $3,000 of dividends.
Same shares, FVOCI election. Profit?
Show answer
$3,000; the $15,000 gain goes to OCI.
Name three indicators of significant influence.
Show answer
Board representation, participation in policy-making, material transactions, interchange of managers, essential technical information (any three).
What three elements make up control under IFRS 10?
Show answer
Power over the investee, exposure or rights to variable returns, and the ability to use power to affect those returns.
Why is the equity method called one-line consolidation?
Show answer
It produces the same profit attributable to the investor as consolidation but shows it in one line.
Why might consolidated cash overstate what a parent can use?
Show answer
Subsidiary cash may be restricted by local law, covenants or exchange controls, and subsidiary creditors have first claim.
A private enterprise using ASPE owns 100 per cent of a subsidiary. Must it consolidate?
Show answer
No; it may choose consolidation, the equity method or the cost method as a policy applied to all subsidiaries.
Rerun the classification program after changing the data partner to 15 per cent with no board seat and no licence. What changes?
Show answer
Its relationship becomes passive and the method becomes fair value.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.