
ECON-102 · Lesson 8 of 12 · 26 min
The Federal Reserve and monetary policy
The Federal Reserve System, usually called the Fed, is the central bank of the United States. It conducts monetary policy, supervises and regulates many banks, provides financial services to banks and the federal government, and oversees the payment system. Monetary policy, the management of short-term interest rates to promote maximum employment and stable prices, is the job that most directly affects households and businesses. When the Fed raised its policy rate from near zero to over 5 % in 2022–2023, mortgage and credit card rates soared; when it cut rates in 2024 and 2025, borrowing costs eased; and in September 2026 it raised rates again in response to an energy-driven rise in inflation. This lesson explains what the Fed is trying to achieve, the tools it uses, how its decisions spread through the economy, and the debates about how it should act.
Structure and independence
The Fed was created by the Federal Reserve Act of 1913. It consists of a Board of Governors in Washington, whose seven members are appointed by the President and confirmed by the Senate for 14-year terms, and twelve regional Federal Reserve Banks. Monetary policy is set by the Federal Open Market Committee (FOMC): the seven governors, the president of the Federal Reserve Bank of New York and four of the other eleven regional bank presidents, who serve in rotation. The FOMC meets eight times a year; after four of the meetings it publishes a Summary of Economic Projections showing each participant's forecasts. Kevin Warsh became chair in May 2026, succeeding Jerome Powell. The Fed's independence from day-to-day political pressure, established by law and practice, has been the subject of intense debate in 2025–2026, including public pressure on the Fed to cut rates and legal disputes over the President's power to remove governors.
Why make central banks independent? The main argument is credibility. Politicians facing elections may be tempted to stimulate the economy before a vote, accepting higher inflation later. If people expect this, they build higher inflation into wages and prices, and the economy ends up with higher inflation and no lasting gain in employment. Delegating monetary policy to an independent institution with a clear mandate makes low-inflation promises more believable. Cross-country evidence from the 1980s and 1990s found that countries with more independent central banks had lower average inflation without lower growth. Critics respond that independence gives significant power to unelected officials, which is why it comes with clear mandates, transparency and accountability to legislatures.
The mandate
Congress has given the Fed a dual mandate: to promote maximum employment and stable prices (together with moderate long-term interest rates, which follow from the first two). Since 2012 the FOMC has defined price stability as 2 % inflation measured by the PCE price index. In 2020 it adopted flexible average inflation targeting, aiming for inflation moderately above 2 % for some time after periods below target. In August 2025, after a five-year review, it revised its Statement on Longer-Run Goals: it dropped the averaging approach, removed language saying it would respond only to shortfalls of employment from its maximum level, and committed to a balanced approach when its employment and inflation goals conflict. The 2 % goal was unchanged.
Inflation targeting is flexible in practice. Central banks do not try to hit the target every month, which would require large swings in interest rates and output. They aim to bring inflation back to target over a horizon of roughly one to two years, while paying attention to employment, output and financial stability. Clear communication of the target helps anchor inflation expectations: if people believe inflation will average 2 %, they set wages and prices accordingly, which makes the target easier to hit.
The policy interest rate and how it is implemented
The Fed's main tool is its target range for the federal funds rate, the rate at which banks lend reserves to each other overnight. Because banks now hold abundant reserves, the Fed steers the federal funds rate mainly through administered rates: the interest rate on reserve balances (IORB), which sets a floor because banks will not lend for less than they can earn at the Fed, and the overnight reverse repurchase agreement rate, which sets a floor for money market funds and other lenders. Changes in the target range quickly pass through to the prime rate, credit card rates and adjustable-rate loans.
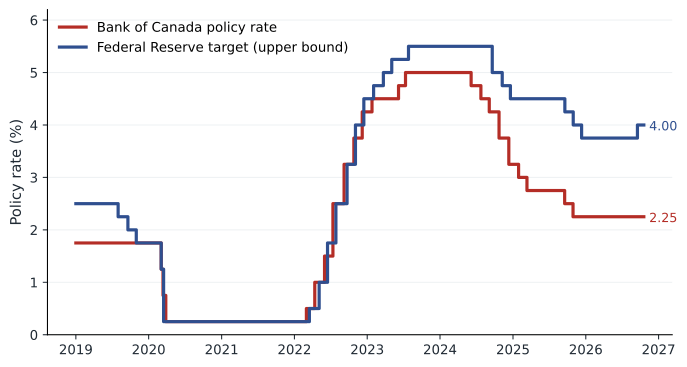
Central banks change their policy rates in steps, usually of 25 basis points (a quarter of a percentage point), occasionally 50 or more when conditions change quickly. The chart shows how closely the two central banks moved after 2020, and how their paths diverged in 2025–2026: the Bank of Canada cut further, because the Canadian economy was weaker and more exposed to US tariffs, while the Fed stopped cutting earlier and raised rates in 2026 when inflation rose.
Other tools: balance sheets and guidance
When the policy rate reaches its effective lower bound, near zero, central banks cannot cut it further in a meaningful way. In 2020 both central banks turned to other tools. Quantitative easing (QE) means buying large quantities of government bonds and, in the Fed's case, mortgage-backed securities, paid for by creating reserves. QE lowers longer-term interest rates by reducing the supply of bonds available to investors and by signaling that the policy rate will stay low. Forward guidance means communicating the likely future path of the policy rate; promising to keep rates low for an extended period lowers longer-term rates today. When inflation rose, the central banks reversed course with quantitative tightening (QT), letting bonds mature without replacing them, which shrinks the balance sheet.
The Fed's balance sheet more than doubled in 2020–2021 to about 9 trillion dollars. It began QT in June 2022 and, after slowing the pace in 2024 and 2025, ended balance sheet reduction on 1 December 2025, judging that reserves had fallen to a level close to ample.
How monetary policy works: the transmission mechanism
A change in the policy rate affects the economy through several channels. Through the interest rate channel, higher short-term rates raise the rates on mortgages, car loans, business loans and, via expectations, longer-term bonds, which discourages borrowing for houses, durable goods and investment. Through the wealth channel, higher rates tend to lower the prices of stocks, bonds and houses, making households feel less wealthy and spend less. Through the exchange rate channel, higher rates attract foreign capital, raising the value of the currency, which makes exports more expensive and imports cheaper. Through the credit channel, higher rates weaken borrowers' balance sheets and make banks more cautious. And through the expectations channel, credible policy actions shape expected inflation, which feeds into wages and prices.
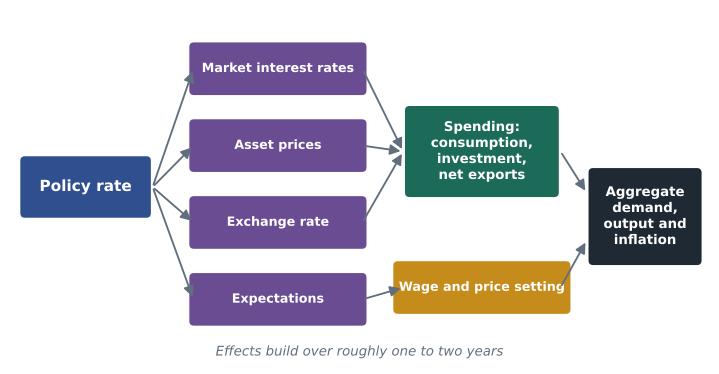
These effects take time. Most estimates suggest that a change in the policy rate has its largest effect on output after about a year and on inflation after one to two years. The lags are long and variable, which means central banks must act on forecasts rather than current data, and must accept uncertainty about the effects of their decisions.
The housing channel works differently in the United States, because most mortgages are 30-year fixed-rate loans. When rates rose in 2022–2023, existing homeowners were insulated from higher payments, which weakened the effect of tighter policy on their spending, but many became reluctant to sell and give up low-rate mortgages, freezing the housing market. Financial markets and the dollar respond strongly to Fed decisions, and because the dollar is the world's main reserve currency, Fed policy affects interest rates and capital flows around the world.
The Taylor rule
How should a central bank choose its policy rate? A widely used guide is the Taylor rule, proposed by John Taylor in 1993. It sets the nominal policy rate equal to the neutral real rate plus current inflation, plus half the gap between inflation and the target, plus half the output gap. The rule captures a key principle: when inflation rises, the nominal rate should rise by more than one for one, so that the real interest rate rises and restrains demand. Central banks do not follow any rule mechanically, but they consult rules like this as benchmarks.
Worked problem
Applying the Taylor rule (illustrative)
Suppose the neutral real rate is 1.0 %, core PCE inflation is 3.0 %, the target is 2 % and the output gap is +0.5 %. What policy rate does the Taylor rule suggest? How does it change if inflation is 3.5 %?
Show solution
- With 3.0 % inflation: i = 1.0 + 3.0 + 0.5 × 1.0 + 0.5 × 0.5 = 4.75 %.
- With 3.5 % inflation: i = 1.0 + 3.5 + 0.5 × 1.5 + 0.25 = 5.50 %.
Answer: The rule suggests a rate of roughly 4.75 to 5.5 %, above the Fed's 3.75–4.00 % range in autumn 2026. Different assumptions about the neutral rate and output gap, which cannot be observed, change the answer substantially, and policymakers also weigh risks such as a weakening labor market.
# Taylor-rule policy rates under different assumptions
def taylor(r_star, infl, target, gap, a=0.5, b=0.5):
    return r_star + infl + a * (infl - target) + b * gap

cases = [
    ("core inflation, small negative gap", 0.75, 2.2, 2.0, -1.0),
    ("headline inflation after oil shock", 0.75, 3.1, 2.0, -1.0),
    ("higher neutral rate", 1.50, 2.2, 2.0, -1.0),
    ("inflation 3.5 %, positive gap", 1.00, 3.5, 2.0, 0.5),
]
for label, r, pi, tgt, gap in cases:
print(f"{label:36s} -> policy rate {taylor(r, pi, tgt, gap):.2f} %")core inflation, small negative gap -> policy rate 2.55 % headline inflation after oil shock -> policy rate 3.90 % higher neutral rate -> policy rate 3.30 % inflation 3.5 %, positive gap -> policy rate 5.50 %
Monetary policy in practice: 2020 to 2026
The past few years illustrate how hard monetary policy can be. In March 2020 both central banks cut rates to near zero and launched QE to cushion the pandemic shock. As the economy recovered in 2021, inflation rose; both central banks initially judged the rise to be transitory, caused by supply disruptions that would fade. By early 2022 it was clear that inflation was broader and more persistent, and both began raising rates rapidly. Critics argue they waited too long, allowing expectations to drift up; defenders note that the supply shocks were unprecedented and that the subsequent disinflation occurred without a recession. Both central banks have since published reviews of what they learned, including the need to consider supply shocks and risk scenarios more seriously.
After holding its range at 5.25–5.50 % from July 2023, the Fed cut by a full point in late 2024 and by another three quarters of a point in late 2025, to 3.50–3.75 %. In 2026, as the oil shock pushed headline CPI inflation above 3.5 % and core PCE inflation stayed above 3 %, the FOMC grew concerned that inflation expectations could rise; it raised the range to 3.75–4.00 % on 16 September 2026. With payroll growth slowing sharply and unemployment edging up to 4.2 %, the decision illustrated the dual mandate's trade-off: some argued the Fed should look through a temporary energy shock, while others argued that inflation had been above target for more than five years and that credibility required action.
A central lesson of this period is that central banks must distinguish between shocks they should look through and shocks that threaten to unanchor expectations. A one-time rise in oil prices raises the price level but need not cause persistent inflation if expectations stay anchored; responding aggressively could cause an unnecessary recession. But after a long period of above-target inflation, people may begin to expect more of it, and the central bank may need to act to protect its credibility. Lesson 9 analyses supply shocks with the aggregate demand and aggregate supply model, and lesson 12 returns to the debate.
Common mistakes
MistakeThe central bank sets mortgage rates directly.
InsteadIt sets a short-term policy rate; mortgage and bond rates respond through markets and expectations.
MistakeMonetary policy works within weeks.
InsteadEffects on output peak after about a year and on inflation after one to two years.
MistakeRaising rates one for one with inflation is enough.
InsteadThe Taylor principle says nominal rates should rise more than inflation so real rates rise.
MistakeIndependence means the central bank answers to no one.
InsteadIt operates under a legal mandate with transparency and accountability to parliament or Congress.
MistakeQE is the same as printing money to pay for government spending.
InsteadQE buys existing bonds from markets to lower long-term rates and can be reversed through QT; it is not direct financing of deficits.
Summary and key terms
- The Fed has a dual mandate of maximum employment and stable prices, defined as 2 % PCE inflation; its 2025 review dropped average inflation targeting.
- Central bank independence improves the credibility of low-inflation commitments, balanced by mandates and accountability.
- The main tool is a short-term policy interest rate, implemented with administered rates on reserves.
- At the lower bound, central banks use quantitative easing and forward guidance; quantitative tightening reverses QE.
- Policy works through interest rates, asset prices, the exchange rate, credit and expectations, with long and variable lags.
- The Taylor rule is a benchmark: nominal rates should rise more than inflation, adjusted for the output gap.
- Central banks must decide whether to look through supply shocks or act to keep expectations anchored.
- Central bank
- The institution that manages a country's currency, money and monetary policy.
- Inflation targeting
- A framework in which the central bank commits to a numerical inflation target.
- Policy interest rate
- The FOMC's target range for the federal funds rate.
- Effective lower bound
- The level near zero below which the policy rate cannot usefully be cut.
- Quantitative easing (QE)
- Large-scale central bank purchases of bonds to lower long-term interest rates.
- Quantitative tightening (QT)
- Shrinking the central bank balance sheet by not replacing maturing bonds.
- Forward guidance
- Communication about the likely future path of policy rates.
- Transmission mechanism
- The channels through which monetary policy affects spending and inflation.
- Taylor rule
- A formula linking the policy rate to inflation and the output gap.
- Anchored expectations
- Inflation expectations that stay close to the target despite shocks.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Why are central banks made independent?
Show answer
To make low-inflation commitments credible and avoid political pressure for short-term stimulus.
How does the Fed define price stability?
Show answer
2 % inflation in the PCE price index.
Name four channels of monetary transmission.
Show answer
Interest rates, asset prices, exchange rate, credit, expectations.
Neutral real rate 1 %, inflation 4 %, target 2 %, gap 0. Taylor rule rate?
Show answer
1 + 4 + 1 + 0 = 6 %.
Why must central banks act on forecasts?
Show answer
Policy affects inflation with lags of one to two years.
What is QE meant to achieve?
Show answer
Lower longer-term interest rates when the policy rate is at its lower bound.
Why might a central bank look through an oil price shock?
Show answer
It raises the price level once; if expectations stay anchored, inflation returns to target without tightening.
Why might it not look through?
Show answer
After prolonged high inflation, expectations may rise and credibility may require action.
How do mortgage terms affect transmission?
Show answer
Short renewal periods pass rate changes to borrowers faster; long fixed rates delay the effect.
Portfolio task: read the latest policy rate announcement and summarize the reasons given for the decision in three sentences.
Show answer
Answers vary; should identify the inflation and growth assessment.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.