
ACCT-311 · Lesson 4 of 12 · 26 min
Consolidation at the date of acquisition
Lesson 3 measured Larkspur's acquisition of 80 percent of Blue Heron: consideration of $4,200,000, identifiable net assets at fair value of $3,800,000, NCI of $950,000 and goodwill of $1,350,000. Larkspur records the acquisition in its own books as a single asset, Investment in Blue Heron, of $4,200,000. Blue Heron's books are unchanged: it simply has a new shareholder. Neither set of records shows the group. This lesson prepares the consolidated statement of financial position at the acquisition date, the first step in every consolidation.
What consolidation does
Consolidated financial statements present the assets, liabilities, equity, income, expenses and cash flows of a parent and its subsidiaries as those of a single economic entity. Consolidation does not change any entity's legal records. It is performed on a worksheet, outside the general ledgers, every time consolidated statements are prepared. The worksheet starts with the separate statements of each entity and applies adjustments and eliminations so that the result shows only the group's dealings with outsiders.
ASC 810 sets out the procedures. The financial statements of the parent and subsidiaries are combined line by line. The parent's investment is eliminated against the subsidiary's equity, and intercompany balances and transactions are eliminated in full. Unlike IFRS, US GAAP does not explicitly require uniform accounting policies within a group if a subsidiary's policies are appropriate in its industry, although conformity is common. A subsidiary with a different fiscal year end may be consolidated using its own statements if the difference is not more than about three months, with disclosure or recognition of intervening events that materially affect the group.
Three views of the group
Different theories of consolidation answer one question differently: whose statements are these? Under the proprietary view, the statements serve the parent's shareholders, and only the parent's percentage of the subsidiary's assets and liabilities would be included, as in proportionate consolidation. Under the parent company view, the statements still serve the parent's shareholders but include 100 percent of the subsidiary's carrying amounts, with fair value increments and goodwill recognized only for the parent's share; NCI is measured at its share of carrying amounts or identifiable net assets. Under the entity view, the statements serve all the owners of the group, so 100 percent of fair values and goodwill are recognized, and NCI is equity measured at fair value.
Current US GAAP follows the entity view: 100 percent of the subsidiary's identifiable net assets and goodwill are recognized at fair value, and noncontrolling interest is presented within equity at fair value. IFRS reaches the same result if NCI is measured at fair value, but its proportionate share option is a remnant of the parent company view applied to goodwill.
| View | Subsidiary's net assets included | Goodwill recognized | NCI |
|---|---|---|---|
| Proprietary | Parent's percentage only | Parent's share only | Not shown |
| Parent company | 100% of carrying amounts plus parent's share of fair value increments | Parent's share only | Share of carrying amounts, outside equity in older practice |
| Parent company extension | 100% of fair values | Parent's share only | Share of identifiable net assets at fair value, in equity |
| Entity | 100% of fair values | 100% (parent and NCI) | Fair value, in equity |
The worksheet approach
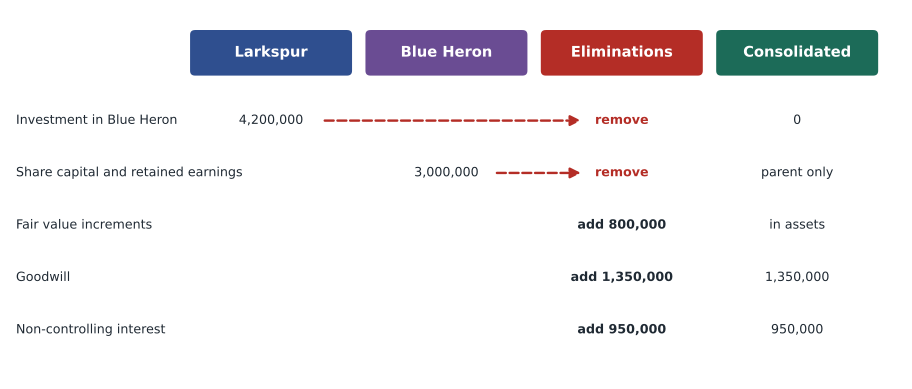
Most consolidations use a worksheet with columns for the parent, each subsidiary, elimination debits and credits, and the consolidated amounts. At the acquisition date, two kinds of entries are needed. First, the parent's investment account is eliminated against the subsidiary's equity accounts, and NCI is established. Second, the acquisition differential, the excess of consideration plus NCI over the carrying amount of the subsidiary's net assets, is allocated to the fair value increments on identifiable assets and liabilities and to goodwill. Many textbooks combine the two into one elimination entry; others use an intermediate 'acquisition differential' account to make the allocation visible.
Worked problem
Computing and allocating the acquisition differential
Using the lesson 3 figures with NCI at fair value, compute the acquisition differential and allocate it.
Show solution
- Consideration plus NCI: $4,200,000 + $950,000 = $5,150,000.
- Carrying amount of Blue Heron's net assets: $3,000,000.
- Acquisition differential: $5,150,000 − $3,000,000 = $2,150,000.
- Allocated to inventory $100,000, equipment $400,000 and patent $300,000, a total of $800,000.
- Remainder to goodwill: $2,150,000 − $800,000 = $1,350,000, as computed in lesson 3.
Answer: Acquisition differential $2,150,000: fair value increments $800,000 and goodwill $1,350,000.
The elimination entries on the worksheet at 1 January 2026 are then as follows. Entry (a) eliminates the investment and Blue Heron's equity and sets up NCI and the acquisition differential: debit share capital $1,000,000 and retained earnings $2,000,000 (Blue Heron's), debit acquisition differential $2,150,000; credit Investment in Blue Heron $4,200,000 and NCI $950,000. Entry (b) allocates the differential: debit inventory $100,000, equipment $400,000, patent $300,000 and goodwill $1,350,000; credit acquisition differential $2,150,000.
| Account | Larkspur | Blue Heron | Debit | Credit | Consolidated |
|---|---|---|---|---|---|
| Cash | 1,300,000 | 300,000 | 1,600,000 | ||
| Receivables | 1,800,000 | 700,000 | 2,500,000 | ||
| Inventory | 2,400,000 | 900,000 | (b) 100,000 | 3,400,000 | |
| Investment in Blue Heron | 4,200,000 | (a) 4,200,000 | 0 | ||
| Equipment, net | 6,500,000 | 2,600,000 | (b) 400,000 | 9,500,000 | |
| Patent | (b) 300,000 | 300,000 | |||
| Goodwill | (b) 1,350,000 | 1,350,000 | |||
| Acquisition differential | (a) 2,150,000 | (b) 2,150,000 | 0 | ||
| Payables | 1,600,000 | 500,000 | 2,100,000 | ||
| Contingent consideration | 200,000 | 200,000 | |||
| Long-term debt | 4,400,000 | 1,000,000 | 5,400,000 | ||
| Share capital | 5,000,000 | 1,000,000 | (a) 1,000,000 | 5,000,000 | |
| Retained earnings | 5,000,000 | 2,000,000 | (a) 2,000,000 | 5,000,000 | |
| Non-controlling interest | (a) 950,000 | 950,000 |
# Consolidated balance sheet at the acquisition date, 1 January 2026 (illustrative)
P = {"Cash": 1_300_000, "Receivables": 1_800_000, "Inventory": 2_400_000,
     "Investment in Blue Heron": 4_200_000, "Equipment, net": 6_500_000}
S = {"Cash": 300_000, "Receivables": 700_000, "Inventory": 900_000, "Equipment, net": 2_600_000}
PL = {"Payables": 1_600_000, "Contingent consideration": 200_000, "Long-term debt": 4_400_000,
      "Share capital": 5_000_000, "Retained earnings": 5_000_000}
SL = {"Payables": 500_000, "Long-term debt": 1_000_000, "Share capital": 1_000_000,
      "Retained earnings": 2_000_000}
fv_inc = {"Inventory": 100_000, "Equipment, net": 400_000, "Patent": 300_000}
nci, goodwill = 950_000, 1_350_000
assets = {}
for k in list(P) + list(S) + list(fv_inc) + ["Goodwill"]:
    assets[k] = P.get(k, 0) + S.get(k, 0) + fv_inc.get(k, 0)
assets["Goodwill"] = goodwill
assets.pop("Investment in Blue Heron")          # eliminated against the subsidiary's equity
claims = {k: PL.get(k, 0) + (SL.get(k, 0) if k not in ("Share capital", "Retained earnings") else 0)
          for k in PL}
claims["Non-controlling interest"] = nci
print(f"{'Assets':<28}{'Amount':>12}")
for k, v in assets.items():
    print(f"{k:<28}{v:>12,.0f}")
print(f"{'Total assets':<28}{sum(assets.values()):>12,.0f}")
print(f"{'Liabilities and equity':<28}")
for k, v in claims.items():
    print(f"{k:<28}{v:>12,.0f}")
print(f"{'Total':<28}{sum(claims.values()):>12,.0f}")Assets Amount Cash 1,600,000 Receivables 2,500,000 Inventory 3,400,000 Equipment, net 9,500,000 Patent 300,000 Goodwill 1,350,000 Total assets 18,650,000 Liabilities and equity Payables 2,100,000 Contingent consideration 200,000 Long-term debt 5,400,000 Share capital 5,000,000 Retained earnings 5,000,000 Non-controlling interest 950,000 Total 18,650,000
Both sides total $18,650,000. Look at what disappears and what appears. Larkspur's investment account and Blue Heron's share capital and retained earnings are gone: the group's equity is the parent's share capital and retained earnings plus NCI. Blue Heron's identifiable assets appear at fair value, including the patent it never recorded, and goodwill appears even though neither company has it in its own books.
Consolidated equity at acquisition
At the acquisition date, consolidated retained earnings equal the parent's retained earnings. The subsidiary's retained earnings at acquisition are pre-acquisition earnings: they were bought, not earned by the group, and were paid for as part of the consideration. Only the subsidiary's profits after acquisition, adjusted for the amortization of the acquisition differential, become part of consolidated retained earnings, as lesson 5 shows. Similarly, the subsidiary's share capital never appears in consolidated equity; consolidated share capital is the parent's.
Noncontrolling interest is presented within equity, separately from the parent's equity, and net income and comprehensive income are attributed to the parent and to the noncontrolling interest on the face of the statements, under ASC 810-10-45.
The direct approach
For simple consolidations, a direct approach can be quicker than a worksheet: add the parent's and subsidiary's carrying amounts for each asset and liability, add the unamortized fair value increments and goodwill, exclude the investment account and the subsidiary's equity, and add NCI. The result is the same. The worksheet remains useful for complex groups, intercompany eliminations and audit trails, and most consolidation software follows its logic.
Worked problem
Proportionate NCI instead
For comparison: if Larkspur reported under IFRS and elected to measure NCI at its proportionate share of identifiable net assets, what would change in the consolidated balance sheet at acquisition?
Show solution
- NCI: 20% × $3,800,000 = $760,000 instead of $950,000.
- Goodwill: $1,160,000 instead of $1,350,000, the parent's share only.
- All identifiable assets and liabilities are unchanged at fair value.
- Total assets fall by $190,000 to $18,460,000, and total equity falls by the same amount.
Answer: Goodwill and NCI both fall by $190,000; everything else is the same.
Wholly owned subsidiaries and net asset purchases
If Larkspur had bought 100 percent of Blue Heron, there would be no NCI, and goodwill would be consideration less the fair value of identifiable net assets. If instead Larkspur had bought Blue Heron's assets and assumed its liabilities directly, paying cash to Blue Heron rather than to its shareholders, there would be no subsidiary. Larkspur would record each identifiable asset and liability at fair value, and goodwill, directly in its own ledger, and no consolidation would be needed. Buyers choose between share and asset purchases for tax, legal and practical reasons: an asset purchase usually gives the buyer a stepped-up tax basis and avoids taking on unknown liabilities, while a share purchase keeps contracts, permits and licenses in place without having to transfer them.
Consolidation under IFRS and ASPE
IFRS consolidation procedures are close to US GAAP, but IFRS explicitly requires uniform accounting policies and permits the proportionate share basis for NCI. Canadian private enterprises applying ASPE may choose not to consolidate at all; if they do consolidate, NCI is measured at its proportionate share of identifiable net assets.
Presenting non-controlling interest
Non-controlling interest is presented within equity, separately from the equity attributable to owners of the parent, because NCI holders own shares in a group entity rather than having a claim to be repaid. Before the current standards, many companies showed NCI between liabilities and equity, a presentation that obscured whether it was debt or equity. Readers comparing consolidated ratios should remember that total equity includes NCI, so return on equity is usually calculated on the parent's share of profit and equity, and that the consolidated statements include 100 percent of the subsidiary's assets and liabilities even though the parent owns only 80 percent of Blue Heron.
Common mistakes
MistakeAdding the subsidiary's retained earnings at acquisition to consolidated retained earnings.
InsteadPre-acquisition earnings were bought; consolidated retained earnings at acquisition equal the parent's.
MistakeLeaving the investment account in the consolidated statements.
InsteadIt is eliminated against the subsidiary's equity; the underlying assets and liabilities replace it.
MistakeCombining only the parent's percentage of the subsidiary's assets.
InsteadConsolidation combines 100 percent of the subsidiary's assets and liabilities; NCI shows the outside owners' share.
MistakeUsing the subsidiary's carrying amounts for its assets.
InsteadUse acquisition-date fair values, including unrecorded intangibles.
MistakePresenting NCI as a liability.
InsteadNCI is equity, presented separately from the parent's equity.
Summary and key terms
- Consolidation is done on a worksheet; no entity's legal records change.
- At acquisition the parent's investment is eliminated against the subsidiary's equity, and NCI is recognized.
- The acquisition differential, consideration plus NCI less the subsidiary's carrying amounts, is allocated to fair value increments and goodwill.
- Consolidated share capital and retained earnings at acquisition equal the parent's.
- US GAAP follows the entity view: 100 percent fair values and goodwill, NCI at fair value.
- A net asset purchase is recorded directly in the acquirer's books, with no consolidation.
- IFRS requires uniform policies and allows proportionate NCI; ASPE allows private enterprises not to consolidate.
- Controlling financial interest
- The ASC 810 basis for consolidation, usually a majority voting interest or primary beneficiary status.
- Consolidation worksheet
- A working paper that combines the separate statements of group entities and applies eliminations.
- Elimination entry
- A worksheet adjustment that removes intragroup items or the investment account.
- Pre-acquisition retained earnings
- A subsidiary's retained earnings at the acquisition date, eliminated on consolidation.
- Entity theory
- The view that consolidated statements serve all group owners, recognizing 100 percent of fair values and goodwill, with NCI at fair value.
- Parent company theory
- The view that consolidated statements serve the parent's shareholders, recognizing fair value increments only for the parent's share.
- Proprietary theory
- The view that only the parent's share of the subsidiary's assets and liabilities should be included.
- Direct approach
- Preparing consolidated amounts by adding balances and adjustments directly, without a full worksheet.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A parent pays $900,000 for 90 percent of a subsidiary with carrying amount $700,000 and identifiable net assets at fair value $820,000. NCI fair value $95,000. Acquisition differential?
Show answer
$295,000 ($900,000 + $95,000 − $700,000).
Allocate that differential.
Show answer
Fair value increments $120,000; goodwill $175,000.
What are consolidated retained earnings at acquisition if the parent has $3,000,000 and the subsidiary $400,000?
Show answer
$3,000,000.
Rerun the worksheet program with goodwill of $1,160,000 and NCI of $760,000. Total assets?
Show answer
$18,460,000.
Why is the subsidiary's share capital eliminated?
Show answer
It is internal to the group; consolidated share capital is the parent's.
A subsidiary uses FIFO and the parent weighted average. What must happen on consolidation under IFRS?
Show answer
Adjust the subsidiary's figures to the group's policy; IFRS requires uniform policies.
A subsidiary's year end is two months before the parent's. Can it be used?
Show answer
Yes, with adjustments for significant intervening transactions, since the gap does not exceed three months.
A buyer pays $2,000,000 for all the assets of a business, assuming $500,000 of its liabilities. Is consolidation needed?
Show answer
No; it is a net asset purchase recorded directly in the buyer's books.
Under the entity view, what does NCI represent?
Show answer
The fair value of the outside owners' interest in the subsidiary, including their share of goodwill.
Name one reason a buyer might prefer a share purchase.
Show answer
Contracts, permits and licenses stay in place without transfer (or simpler legal process, or seller tax preferences).
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.