
ARCH-520 · Lesson 5 of 12 · 22 min
Financial management
In Professional Practice Hannah Moss showed the students the arithmetic of utilization, multipliers and overhead, and the danger that a profitable firm can run out of cash. In the fifth week of the graduate seminar she goes further. Each student will build the financial statements of their imagined firm and a month-by-month cash-flow forecast for its first eighteen months, and then defend them to a banker. The banker is Elena Sokolova, who manages loans to professional firms and small businesses and has lent to several architecture practices. She tells the class that she has seen more good design firms fail for lack of cash than for lack of talent, and that she judges founders less by their portfolios than by whether they understand their own numbers.
Three financial statements
Moss introduces the three statements every firm prepares, usually with an accountant, at least once a year and preferably every month.
- The income statement, or profit and loss, shows revenue and expenses over a period and the profit or loss that results. For an architecture firm, revenue is the fees earned; the largest expenses are salaries and benefits, followed by consultants, rent, software, insurance and marketing.
- The balance sheet shows what the firm owns and owes at a moment in time. Its assets include cash, accounts receivable (fees invoiced but not yet paid), work in progress (fees earned but not yet invoiced) and equipment. Its liabilities include accounts payable to consultants and suppliers, loans and amounts owed to employees and tax authorities. The difference is the owners' equity.
- The cash-flow statement shows how cash moved in and out: from operations, from investment in equipment and from financing such as loans and owners' contributions.
Sokolova says that she reads them in the reverse of the order most founders expect. She looks at the cash-flow statement first, because cash is what keeps the firm alive; then the balance sheet, especially receivables and work in progress, because they show how quickly the firm turns work into cash; and only then the income statement.
Where the money goes
Moss shows the income statement of a typical small firm as a single bar, with each dollar of gross fees divided by where it goes. About 30 cents is passed straight through to consultants and reimbursable expenses, which leaves 70 cents of net revenue. Salaries for project work, salaries for time that is not billable and benefits take most of the rest. Rent, software and hardware, insurance and marketing take smaller shares, and what remains is profit, here 9 cents of each dollar of gross fees, or about 13 cents of each dollar of net revenue.
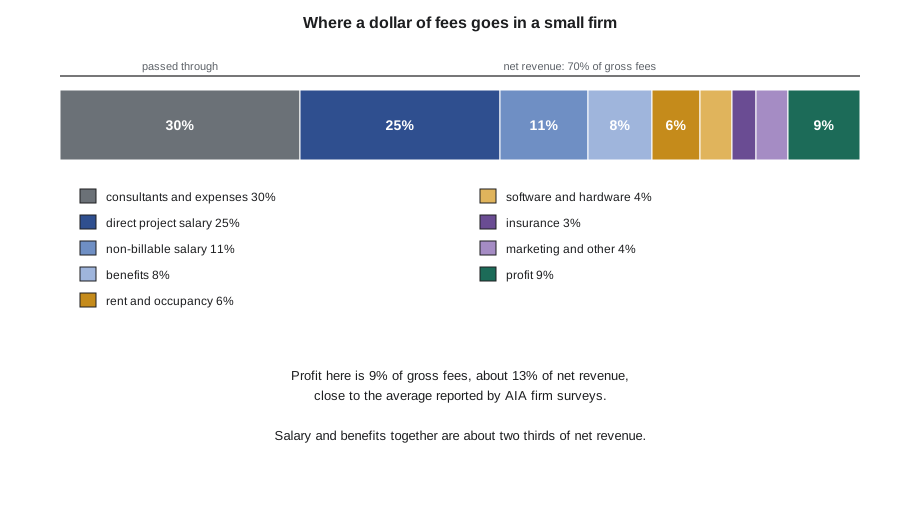
The profit share is close to what the AIA's 2024 firm survey reported for American firms, about 13% of net revenue on average, with wide variation between firms. Moss stresses that profit is not a luxury. It pays for the partners' risk, for new computers and software, for the training of staff, for bonuses that keep good people, and for the reserve that carries the firm through a slow year. A firm that aims for no profit will eventually find that it has none when it needs it.
Work in progress and receivables
The greatest difference between an architecture firm and many other businesses is the delay between doing the work and receiving the money. A designer works in March. The firm invoices at the end of March for the work completed. The client reviews the invoice in April, approves it in May and pays in late May. The firm has paid the designer's salary twice before it receives the fee for her March work. Work in progress, the work done but not yet invoiced, and receivables, the invoices not yet paid, together represent cash the firm has earned but cannot use.
Sokolova says that the number she watches most closely is days sales outstanding: the average number of days between doing the work and receiving payment. For many architecture firms it is between sixty and ninety days. Every day it can be reduced frees cash. Moss lists the methods, some of which the students met in Professional Practice: invoice promptly at the end of each month, describe the work clearly so that the client approves the invoice without questions, follow up on every invoice after thirty days, ask for retainers on new projects, and include interest and suspension provisions in contracts. She adds one more for small firms: know the client's approval process and the name of the person who approves invoices.
A cash-flow forecast
Moss asks Wren to forecast the cash of Common Room Architects for its first eighteen months. The firm opens with three founders, each paid a modest salary, and adds an employee after six months and another after a year. Its billings grow slowly as it wins its first projects. Clients pay about two months after each invoice. The founders put 75,000 dollars of their savings into the firm, and the firm arranges a line of credit with a limit of 150,000 dollars that it can draw when cash runs short and repay when cash returns.
# Cash flow for a new firm in its first 18 months (Canadian dollars).
payroll = [21_000] * 6 + [31_000] * 6 + [46_000] * 6   # salaries and benefits: 3, then 4, then 5 people
fixed = 8_000                 # rent, software, insurance, accounting each month
start_cash = 75_000           # founders' savings put into the firm
credit_limit = 150_000          # bank line of credit
rate = 0.0745 / 12             # monthly interest on the line
billings = [0, 10, 20, 30, 35, 40, 45, 50, 55, 60, 60, 65, 65, 70, 70, 75, 75, 75]  # thousands invoiced
DELAY = 2                     # clients pay about two months after the invoice
cash, line, peak, peak_month = start_cash, 0.0, 0.0, 0
for m in range(18):
    received = billings[m - DELAY] * 1000 if m >= DELAY else 0
    cash += received - payroll[m] - fixed - line * rate
    if cash < 0:                          # draw on the line of credit
        line += -cash; cash = 0
    elif line > 0:                        # repay the line first
        repay = min(line, cash); line -= repay; cash -= repay
    if line > peak: peak, peak_month = line, m + 1
    if (m + 1) % 3 == 0:
        print(f"month {m + 1:>2}: billed {billings[m]:>3}k  received {received / 1000:>3.0f}k  cash {cash:>8,.0f}  line {line:>8,.0f}")
billed, paid = sum(billings) * 1000, sum(billings[:-DELAY]) * 1000
print(f"invoiced {billed:,.0f}; collected {paid:,.0f}; still owed by clients {billed - paid:,.0f}")
print(f"peak use of the line {peak:,.0f} in month {peak_month} against a limit of {credit_limit:,.0f}")month 3: billed 20k received 0k cash 0 line 12,000 month 6: billed 40k received 30k cash 0 line 39,517 month 9: billed 55k received 45k cash 0 line 37,302 month 12: billed 65k received 60k cash 10,236 line 0 month 15: billed 70k received 65k cash 38,236 line 0 month 18: billed 75k received 75k cash 91,236 line 0 invoiced 900,000; collected 750,000; still owed by clients 150,000 peak use of the line 43,763 in month 7 against a limit of 150,000
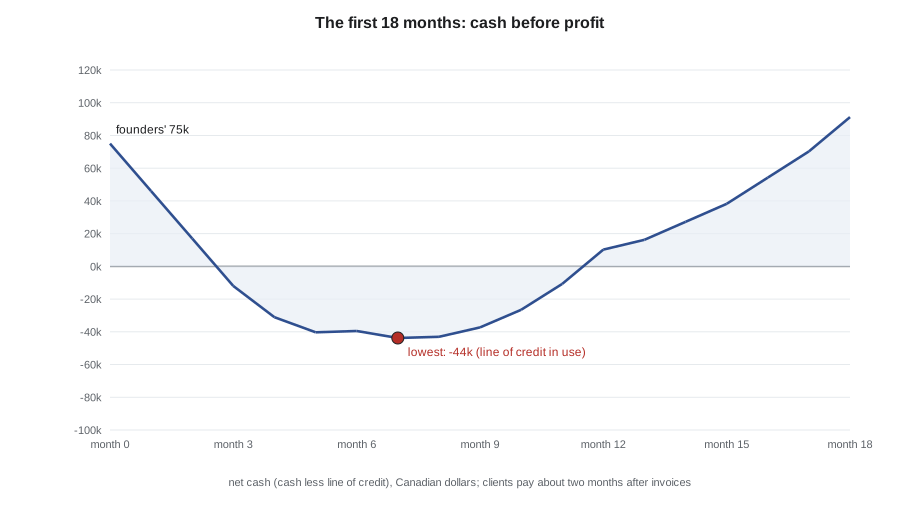
The forecast shows the shape Sokolova calls the J-curve. The founders' cash is gone within three months, because salaries and costs are paid every month while the first invoices take two months to be paid. The firm draws on its line of credit until about month 7, when it owes about 44,000 dollars, and then repays the line as payments catch up with costs. By the end of the eighteen months the firm has invoiced 900,000 dollars, collected 750,000 and has 150,000 still owed by clients, two months of billings that are its working capital. Moss points out that the firm is profitable from early in its first year, yet without the line of credit it could not have paid its people in the spring.
Sokolova asks Wren two questions a banker always asks. What happens if clients pay a month later than you assume? And what happens if your second project starts three months late? Wren reruns the model with each change. If clients pay three months after each invoice instead of two, the peak use of the line nearly doubles, to about 84,000 dollars. If a late second project costs the firm 15,000 dollars of billings a month for three months, the peak rises to about 88,000 dollars. Both stay within the limit, but with far less room to spare, and the two together would take the line to about 128,000 dollars, close to its limit. Sokolova says that a founder who has already asked these questions, and knows the answers, is someone she would lend to.
Budgets and monthly reports
A firm should have an annual budget, prepared before the year begins, that forecasts revenue from signed and likely work, salaries, other costs and profit. Moss recommends building it from the bottom up: list the projects and the fees expected from each month by month, then the staff and their costs, then the other expenses. The budget becomes the yardstick for the monthly report. Each month the principals should see, on one page, the month's and year's revenue against budget, the main expenses, the profit, the cash balance and line of credit, receivables by age, work in progress, backlog and the firm's utilization. Moss says the one-page report takes an hour to prepare once the accounting system is set up, and it is the most important hour of the month.
| Indicator | What it shows | A healthy small firm |
|---|---|---|
| Net revenue against budget | Whether the firm is earning what it planned | Within about 5% of budget |
| Profit, year to date | Whether costs are under control | On track for the planned margin |
| Cash and line of credit | Whether the firm can meet payroll | Line repaid at least once a year |
| Days sales outstanding | How quickly work becomes cash | Under 75 days and falling |
| Backlog | Signed work not yet done | Six months or more of revenue |
| Utilization | Billable share of paid hours | Near the firm's target |
Paying the founders
New founders often ask how much to pay themselves. Moss suggests three layers. The first is a salary for the work each founder does, set at a level the firm could afford to pay someone else to do the same work; this keeps the firm's costs honest. The second is a distribution of profit in proportion to ownership, paid only when the firm has the cash and has met its reserve. The third is the value of the firm itself, which grows if the firm builds a reputation and a team that can continue without the founders. In the first year Wren's founders take salaries well below what they earned as employees, and Moss tells them to record the difference: it is part of their investment in the firm.
Taxes affect how founders are paid and how a firm is structured. In Canada, a professional corporation that qualifies as a Canadian-controlled private corporation pays a reduced federal rate of tax on its first 500,000 dollars of active business income, and owners can take income as salary or dividends, each taxed differently. These choices depend on the province and the founders' circumstances, and Moss tells the students to set them with an accountant before the firm opens, not at the end of its first year.
The banker's view
Sokolova closes the session by describing what she looks for when a new firm applies for a line of credit or a term loan. She wants to see a business plan with a realistic cash-flow forecast, evidence of signed or nearly signed work, the founders' own money in the firm, personal guarantees from the founders for the first few years, and a clear understanding of receivables. She warns that the line of credit is for timing differences, not for losses: a firm that draws on its line every month and never repays it is not short of cash, it is losing money, and the bank will notice. She also tells the students to talk to their bank before they need money, not after, because a banker who has been kept informed through good months is far more helpful in a bad one.
Worked problem
Testing a cash-flow forecast
A new firm's forecast shows a peak use of its line of credit of about 44,000 dollars, against a limit of 150,000. What tests should the founders run before presenting it to a bank?
Show solution
- Delay all client payments by one more month and see how the peak changes.
- Delay the second project by three months and see whether the line limit is reached.
- Reduce billings by 20% for the first year and see whether the firm can still meet payroll.
- For each test, identify the response: lower founders' pay, a later hire, a larger line or more founders' cash.
- Present the base case and the tests together, with the responses.
Answer: Stress the forecast with late payments, late projects and lower billings, and show the bank how the firm would respond.
Exercise 5: your firm's finances
- Prepare a budgeted income statement for your firm's first year.
- Build an eighteen-month cash-flow forecast with a two-month payment delay, and find the peak use of a line of credit.
- Run two stress tests and describe your response to each.
- Design the one-page monthly report you would review with your partners.
Self-check
- Can I read an income statement, a balance sheet and a cash-flow statement?
- Do I understand why work in progress and receivables tie up cash?
- Have I tested my forecast against late payments and late projects?
- Do I know what a banker will ask before lending to my firm?
Common mistakes
MistakeTreating profit as cash.
InsteadForecast cash month by month, including the delay before clients pay.
MistakeInvoicing late or with unclear descriptions.
InsteadInvoice promptly at month end with clear descriptions of the work done.
MistakeUsing the line of credit to cover continuing losses.
InsteadUse the line only for timing differences and fix the cause of losses.
MistakePaying the founders whatever cash is left.
InsteadPay salaries for the work, distribute profit only after the reserve is met.
MistakeTalking to the bank only when money is needed.
InsteadKeep the bank informed through good months as well as bad.
Summary and key terms
- The income statement, balance sheet and cash-flow statement together show a firm's financial health.
- About a third of gross fees usually passes through to consultants and expenses; salaries are the largest cost of net revenue.
- Work in progress and receivables tie up cash for two to three months in many firms.
- A new firm's cash follows a J-curve and usually needs a line of credit for its first year.
- Monthly reports, budgets and stress tests let principals and bankers manage the firm with confidence.
- Income statement
- A report of revenue, expenses and profit over a period.
- Balance sheet
- A report of what a firm owns and owes at a moment in time.
- Work in progress
- Fees earned but not yet invoiced.
- Days sales outstanding
- The average number of days between doing work and being paid for it.
- Line of credit
- A loan facility a firm can draw on and repay as its cash needs change.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A firm's gross fees are 1,000,000 dollars and consultants and expenses take 300,000. What is its net revenue?
Show answer
700,000 dollars.
Why is a profitable new firm often short of cash?
Show answer
Because it pays salaries and costs every month while clients pay invoices two or three months later.
What does it suggest if a firm draws on its line of credit every month and never repays it?
Show answer
The firm is losing money, not just waiting for payments.
Name three ways to reduce days sales outstanding.
Show answer
Any three of: invoice promptly, describe work clearly, follow up after thirty days, ask for retainers, charge interest on late payments, know the client's approval process.
Why should founders record the difference between their salaries and their previous pay?
Show answer
It is part of their investment in the firm and should be considered when profits and ownership are shared.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.