
APT-330 · Lesson 2 of 12 · 25 min
Pricing, margins and discounts
▶ Video coming soon A video version of this lesson is on the way.
Imani's comment from the first session, that Corinne's tickets were bigger but Gordon's made more money, became the opening of the second. Rolf put two invoices side by side on the desk. One was a set of front brake pads sold to Gordon Achterhof at the retail price. The other was the same part number sold to Corinne Ferraby at Bramhall Auto Service, list less 25. "Same part, same cost to us," Rolf said. "Tell me what each one earned." By the end of the afternoon Imani could answer that question for any sale in the department, and explain why the prices were set the way they were.
Cost, price, margin and markup
Every pricing decision starts with four numbers:
- Cost: what the department pays for the part, after the supplier's discounts, as recorded in the parts system.
- Selling price: what the customer pays, before sales tax.
- Gross profit: selling price minus cost.
- List price: the supplier's suggested retail price, which the department may follow, raise or discount.
Two different percentages describe the gap between cost and price, and confusing them is one of the most expensive mistakes in the trade.
- Gross margin (or gross profit percentage) is gross profit divided by the selling price. It is the measure on the financial statement.
- Markup is gross profit divided by the cost. It is how many pricing systems are set.
The two can be converted. A margin of 30 percent is a markup of 30 ÷ 70 = 42.9 percent. A markup of 50 percent is a margin of 50 ÷ 150 = 33.3 percent. Markup is always the larger number for the same sale, which is why a counter person who says "we mark it up 40 percent" and a manager who reads "40 percent margin" on the statement are not talking about the same thing.
Worked problem
The two brake pad invoices
The pads cost the department 70.00 dollars and list at 100.00 dollars. Gordon paid list. Bramhall paid list less 25. What did each sale earn, as gross profit and as margin?
Show solution
- Gordon's price: 100.00 dollars. Gross profit = 100.00 − 70.00 = 30.00 dollars. Margin = 30.00 ÷ 100.00 = 30 percent.
- Bramhall's price: 100.00 × 0.75 = 75.00 dollars. Gross profit = 75.00 − 70.00 = 5.00 dollars. Margin = 5.00 ÷ 75.00 = 6.7 percent.
- Compare: the retail sale earned six times as much gross profit on the same part.
Answer: 30.00 dollars (30 percent) on the retail sale, 5.00 dollars (6.7 percent) on the wholesale sale. Wholesale earns its keep through volume and the maker's wholesale programs, not through the margin on each line.
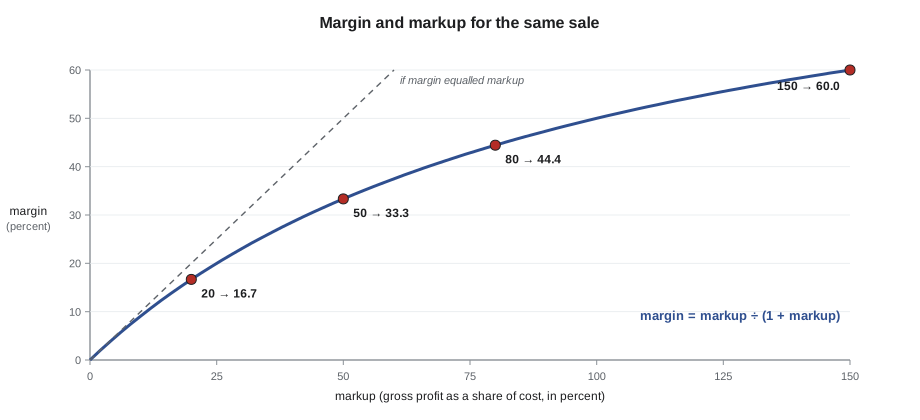
The price matrix
Most parts in the department are sold at the maker's list price. For parts without a useful list price, such as many aftermarket lines, shop supplies and some special orders, the system uses a price matrix: a table of multipliers applied to cost, by cost band. Rolf's matrix, set two years earlier, has five bands:
| Cost band (dollars) | Multiplier on cost | Markup | Margin |
|---|---|---|---|
| Up to 5.00 | 2.50 | 150 percent | 60.0 percent |
| 5.01 to 25.00 | 1.80 | 80 percent | 44.4 percent |
| 25.01 to 100.00 | 1.55 | 55 percent | 35.5 percent |
| 100.01 to 500.00 | 1.35 | 35 percent | 25.9 percent |
| Over 500.00 | 1.20 | 20 percent | 16.7 percent |
The matrix slopes downward for good reasons. A small part, a clip, a bulb, a hose clamp, costs the department as much time to look up, pick and sell as a large one, so it needs a higher markup to pay for that time. Customers rarely notice the price of a two-dollar clip, but they compare the price of a 600-dollar module with other sellers. A steep markup on expensive parts would lose sales; a thin markup on cheap parts would lose money on every transaction.
Worked problem
Pricing a part from the matrix
A Corvane cabin air filter costs 18.40 dollars and has no list price in the system. What is the retail price, and what does the sale earn?
Show solution
- 18.40 dollars falls in the 5.01 to 25.00 band, multiplier 1.80.
- Price = 18.40 × 1.80 = 33.12 dollars.
- Gross profit = 33.12 − 18.40 = 14.72 dollars. Margin = 14.72 ÷ 33.12 = 44.4 percent.
Answer: 33.12 dollars, earning 14.72 dollars at a 44.4 percent margin.
Rolf reviews the matrix once a year, and sooner if supplier costs change sharply. He checks three things: whether the bands still match the department's cost mix, whether any band's prices are losing sales to competitors (lost-sales records and wholesale complaints show this), and whether the break points create odd results, such as a part that costs 25.10 dollars selling for less than one that costs 24.90. With these multipliers, 24.90 × 1.80 = 44.82 dollars, while 25.10 × 1.55 = 38.91 dollars. Some systems smooth the bands to avoid such jumps; Rolf accepts them and watches for complaints.
Price levels and discounts
The department doesn't charge everyone the same price. Each customer account carries a price level, set when the account is opened and reviewed each year:
- Retail (list): walk-in and phone customers, and online orders.
- Fleet: list less 15 for fleets that buy steadily but do their own repairs, such as Orland Courier's 34 vans.
- Wholesale: list less 25 for repair businesses that resell the parts to their own customers, such as Bramhall Auto Service.
- Internal: set by department policy for each type of repair order (lesson 7).
- Special pricing: contract prices for a few large accounts on named part numbers, approved by Rolf and reviewed every quarter.
A discount looks small on the invoice and large on the financial statement. Rolf showed Imani how much extra volume a discount has to bring in just to stand still.
Worked problem
What a discount costs
A part sells for 100.00 dollars and costs 70.00 dollars, a 30.00 dollar gross profit. A customer asks for 5 percent off. How many more parts must the department sell at 95.00 dollars to earn the same total gross profit?
Show solution
- New gross profit per part = 95.00 − 70.00 = 25.00 dollars.
- To earn the same gross profit: 30.00 ÷ 25.00 = 1.2 times as many parts.
- That is 20 percent more volume.
Answer: The 5 percent discount needs 20 percent more sales just to break even on gross profit. A discount is worth giving only when it wins or keeps business the department would otherwise lose.
The same arithmetic explains why Rolf guards the wholesale level so closely. On a part listing at 100.00 and costing 70.00, the fleet price of 85.00 earns 15.00 dollars, a margin of 17.6 percent, and the wholesale price of 75.00 earns only 5.00. On some genuine parts the gap between dealer cost and list is wider, and wholesale earns more; on others it is narrower, and a list-less-25 price would be a loss. The system flags any sale below cost, and Rolf reviews those every Thursday.
Wholesale programs and the maker's support
If wholesale margins are so thin, why does the department sell 147,000 dollars a month of it? Rolf gave three reasons. First, wholesale volume spreads the department's fixed costs, the building, the system, the stock and the staff, over more sales. Second, the maker wants its genuine parts in independent garages and supports dealers who sell them there. Tessaro, like many makers, runs wholesale parts programs: extra discounts on chosen part lines sold to repair businesses, competitive prices on parts where the aftermarket is strong, and quarterly payments for growth. The details change every year and are set out in the program bulletins, which Rolf files with the dealer agreement. Third, a garage that buys its brake parts from Linmore is more likely to send its customers to Linmore's service shop for the jobs it can't do, such as programming and warranty work.
Wholesale also brings risks a manager must control. The department carries the customer's credit, often for 30 days or more. Delivery costs money for every stop. Returns run higher than in retail. And a large account can push for prices the department can't afford. Rolf reviews every wholesale account each year: its purchases, gross profit, returns, delivery stops and payment record. Accounts that cost more to serve than they earn are moved to a different price level or a different delivery schedule, or let go.
Pricing rules and the law
Prices are a commercial decision, but some rules apply.
In Canada, the federal Competition Act no longer treats charging different customers different prices as an offence in itself; the old price discrimination section was repealed in 2009. Pricing can still break the Act if it is part of an abuse of a dominant position or an agreement with competitors to fix prices, which is a crime. The Act's deceptive marketing rules apply to every price a department advertises: the price shown must be one the customer can actually pay, and since 2022 the Act names drip pricing, adding unavoidable fees on top of an advertised price, as deceptive.
For a parts department, the practical rules are simple. Set price levels by objective criteria, such as type of business, volume and services used, and apply them consistently. Keep records of why an account is on its level. Never discuss prices with competing dealers or stores. Advertise prices that customers can actually pay, with any mandatory fees included, and charge the advertised price. When in doubt about a contract price for a large account, the dealership asks its lawyer.
Special orders, cores and price overrides
Three kinds of sale need their own pricing rules.
- Special orders. A part not in stock is ordered for one customer. Rolf's policy prices it by the normal level, takes a deposit of half the price on retail special orders, and explains the return policy before ordering (APT-130). A special-order part costing 212.00 dollars, in the 100.01 to 500.00 band, sells for 212.00 × 1.35 = 286.20 dollars, with a deposit of 143.10 dollars.
- Cores. A core charge, such as 25 dollars on a battery or 75 dollars on an alternator, is not profit. It is a deposit returned when the old part comes back. Core charges are recorded separately so they don't distort the department's sales and margin.
- Price overrides. Counter staff can change a price in the system, for example to match a competitor or settle a complaint. Every override is logged with a reason and the employee's name. Rolf allows overrides up to a set limit per line; larger ones need his approval. Lesson 10 shows what the override log revealed in October.
Imani asked why Rolf didn't simply forbid overrides. "Because sometimes they're right," he said. "If a garage can buy a water pump down the road for 20 dollars less, I'd rather keep the sale and the customer. What I won't accept is overrides nobody can explain."
Pricing and the department's margin
Rolf ended the session by connecting pricing to the number Walter watches: the department's gross margin of 22.3 percent. That figure is a blend of all the markets. Retail sales earn the most per dollar, wholesale the least, and internal and warranty sales fall in between. A department can raise its blended margin without changing a single price, simply by selling more to its higher-margin markets. It can also lose margin without anyone noticing, through unreviewed account levels, careless overrides, sales below cost and matrix bands that haven't kept up with cost increases.
Imani's homework was to price ten recent invoices by hand from the matrix and the account levels, and to compare her answers with the system's. Nine matched. The tenth was a wholesale sale of a module below cost, made because the account's special price had never been updated after a Tessaro price increase. Rolf corrected it the next morning and added the account to his quarterly review list.
Reviewing prices after a supplier increase
Makers and suppliers raise their prices, usually once or twice a year. When Tessaro's price file changes, list prices and dealer costs move together and most retail prices follow automatically. The risk is in everything that doesn't update itself: special contract prices, matrix-priced lines whose cost rose more than the band allows for, and quotes already given to customers. Rolf's routine after each price file is to run a report of sales below cost and below target margin for the following two weeks, update any contract prices that have fallen behind, and tell the counter how long existing quotes will be kept. It takes an afternoon, and it stops a price increase from quietly eating the margin.
Common mistakes
MistakeCalling a markup a margin, or the other way round.
InsteadMargin divides gross profit by the price; markup divides it by the cost. Say which one you mean.
MistakeGiving a discount without working out the extra volume it needs.
InsteadCalculate the gross profit lost per sale and how many more sales would replace it.
MistakeLetting special prices run for years without review.
InsteadReview contract and account prices at least every quarter, especially after supplier price increases.
MistakeCounting core charges as sales.
InsteadRecord cores separately; they are deposits, not profit.
MistakeAllowing price overrides without a reason.
InsteadLog every override with a reason and employee, and approve large ones.
Summary and key terms
- Margin is gross profit divided by price; markup is gross profit divided by cost; margin = markup ÷ (1 + markup).
- A price matrix sets higher markups on low-cost parts and lower markups on expensive parts.
- Price levels (retail, fleet, wholesale, internal, special) give each account a consistent discount from list.
- A small discount needs a large increase in volume to earn the same gross profit.
- Pricing must follow competition and advertising law: no price-fixing, no deceptive or drip pricing, and consistent, documented price levels.
- Gross margin
- Gross profit divided by selling price, as a percentage.
- Markup
- Gross profit divided by cost, as a percentage.
- Price matrix
- A table of multipliers on cost, by cost band, used to set selling prices.
- Price level
- The discount from list assigned to a customer account.
- Price override
- A change to the system price made at the counter, which should be logged with a reason.
- Core charge
- A refundable deposit charged on a part whose old unit can be rebuilt.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A part costs 40.00 dollars and sells for 60.00 dollars. What are the margin and the markup?
Show answer
Gross profit 20.00 dollars. Margin 20 ÷ 60 = 33.3 percent; markup 20 ÷ 40 = 50 percent.
Convert a 25 percent margin into a markup.
Show answer
25 ÷ 75 = 33.3 percent markup.
Using the matrix, price a part costing 3.20 dollars.
Show answer
Band up to 5.00, multiplier 2.50: 3.20 × 2.50 = 8.00 dollars.
A part sells for 50.00 dollars and costs 35.00 dollars. A 10 percent discount is offered. How much more volume is needed to keep the same gross profit?
Show answer
Gross profit falls from 15.00 to 10.00 dollars. 15 ÷ 10 = 1.5, so 50 percent more volume.
Why does the matrix use a lower multiplier for expensive parts?
Show answer
Customers compare prices on expensive parts, and the handling cost is a smaller share of the price, so a lower markup still pays for the sale.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.