
ACCT-499 · Lesson 9 of 12 · 28 min
Performance and strategy: KPIs, the balanced scorecard and investment decisions
The earlier workstreams diagnosed problems. Sofia's workstream looks forward: how should Bluestem measure performance so that its managers pursue profitable, cash-generating growth, and which investments would help it get there? ACCT-421 taught strategy maps, the balanced scorecard, incentive design and capital investment analysis. This lesson applies them to Bluestem. The aim is not to redesign the company's strategy, which is the board's job, but to make sure its measures, incentives and investments support the strategy it has chosen.
What Bluestem measures today
Bluestem's monthly board pack contains revenue against budget, gross margin, adjusted EBITDA, order intake and headcount. Executive bonuses depend on revenue growth (60 percent weight) and adjusted EBITDA (40 percent). There is no measure of cash flow, working capital, customer retention or product quality in either the board pack or the bonus plan. The sales team is paid commission on invoiced revenue, with an accelerator for the fourth quarter.
The measurement system explains a great deal of what the team found. Sales staff are rewarded for invoicing revenue, especially late in the year, but not for collecting it, so they extend payment terms to close deals and push bill-and-hold arrangements in December. Executives are rewarded for revenue and adjusted EBITDA, so there is little pressure to fix working capital, and some incentive to label recurring costs as one-time. No one is rewarded for warranty quality, so a firmware problem that drove 400 site visits did not show up in anyone's measures until the team counted the claims. In the language of ACCT-421, the measures are not goal-congruent: what managers are paid to do diverges from what creates value for shareholders.
The strategy map
A strategy map links objectives in four perspectives, financial, customer, internal process, and learning and growth, into a chain of cause and effect. Bluestem's stated strategy is to become the monitoring platform for water. Working from that, the team drafts a strategy map with management. The financial objective is profitable, cash-generating growth: higher margins, more recurring revenue and positive free cash flow. Customers must be retained and must adopt more subscription services, which requires reliable products, fast installation and clear compliance reporting. Internal processes must deliver quality hardware, timely billing and collection, efficient inventory and a fast close. Learning and growth requires data skills across the company and the retention of key engineers, including those from Merrow Lane.
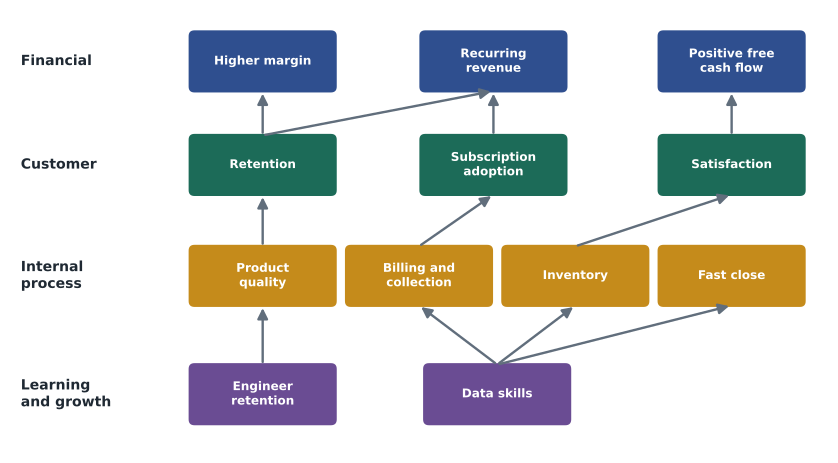
A balanced scorecard
For each objective, the team proposes one or two measures, the 2026 value and a 2028 target agreed provisionally with management. The program sets out the scorecard and flags gaps.
# Bluestem Water Instruments Inc. (invented), in thousands of dollars, years ended December 31.
YEARS = [2024, 2025, 2026]
IS = {'Hardware revenue': [138000, 149500, 161200], 'Subscription revenue': [44000, 55600, 69800],
      'Hardware cost of sales': [82800, 92700, 104800], 'Subscription cost of sales': [11000, 13300, 16100],
      'Selling, general and admin': [42000, 48500, 56900], 'Research and development': [18200, 21000, 23600],
      'Depreciation': [6200, 6900, 7600], 'Amortization of intangibles': [3000, 4800, 4800],
      'Interest expense': [2100, 3900, 4600], 'Income tax expense': [3300, 2500, 2500]}
BS = {  # balances at December 31, 2023 to 2026
      'Cash': [18000, 24200, 25500, 23400], 'Receivables': [26000, 30000, 39800, 52100],
      'Inventories': [22000, 26000, 31500, 41900], 'Other current assets': [2800, 3000, 3600, 4100],
      'Property, plant and equipment': [45000, 48000, 51000, 53500], 'Right-of-use assets': [13000, 12000, 15500, 14800],
      'Intangible assets': [9000, 6000, 19200, 14400], 'Goodwill': [8000, 8000, 24000, 24000],
      'Payables': [15000, 17000, 19500, 22700], 'Accrued liabilities': [8000, 9000, 10500, 11200],
      'Deferred revenue': [11000, 14000, 18500, 21000], 'Warranty provision': [2300, 2500, 2700, 2600],
      'Income taxes payable': [1200, 1300, 900, 700], 'Lease liabilities': [13500, 13000, 16800, 16300],
      'Borrowings': [28000, 25000, 57000, 60000], 'Deferred tax liabilities': [1800, 2000, 2300, 2700],
      'Share capital': [40000, 40000, 40000, 42000], 'Retained earnings': [23000, 33400, 41900, 49000]}
CF = {'Cash from operations': [20900, 15900, 5800], 'Capital expenditure': [-8000, -8400, -8400],
      'Acquisition of Merrow Lane': [0, -34000, 0], 'Dividends paid': [-3000, -3000, -3000]}
def rev(i): return IS['Hardware revenue'][i] + IS['Subscription revenue'][i]
def cogs(i): return IS['Hardware cost of sales'][i] + IS['Subscription cost of sales'][i]
def ebit(i): return rev(i) - cogs(i) - sum(IS[k][i] for k in ('Selling, general and admin', 'Research and development', 'Depreciation', 'Amortization of intangibles'))
def ni(i): return ebit(i) - IS['Interest expense'][i] - IS['Income tax expense'][i]
ASSETS = ['Cash', 'Receivables', 'Inventories', 'Other current assets', 'Property, plant and equipment', 'Right-of-use assets', 'Intangible assets', 'Goodwill']
CUR_A = ASSETS[:4]
CUR_L = ['Payables', 'Accrued liabilities', 'Deferred revenue', 'Warranty provision', 'Income taxes payable']
LIABS = CUR_L + ['Lease liabilities', 'Borrowings', 'Deferred tax liabilities']
def tot(keys, t): return sum(BS[k][t] for k in keys)

# Lesson 9: balanced scorecard KPIs for Bluestem, 2026 actual against the team's proposed 2028 targets.
k = {  # perspective, measure, 2026 actual, 2028 target, higher is better?
    'Financial': [('Operating margin', ebit(2) / rev(2), 0.105, True),
                  ('Subscription share of revenue', IS['Subscription revenue'][2] / rev(2), 0.38, True),
                  ('Free cash flow (thousands)', CF['Cash from operations'][2] + CF['Capital expenditure'][2], 12000, True)],
    'Customer':  [('Net revenue retention, subscriptions', 1.07, 1.12, True),
                  ('Days sales outstanding', BS['Receivables'][3] / rev(2) * 365, 62, False),
                  ('Customer satisfaction score (of 10)', 7.6, 8.4, True)],
    'Internal':  [('Days inventory on hand', BS['Inventories'][3] / cogs(2) * 365, 100, False),
                  ('Warranty claims per 100 units', 6.2, 4.5, False),
                  ('Month-end close (working days)', 11, 6, False)],
    'Learning':  [('Staff completing data-skills training', 0.35, 0.80, True),
                  ('Voluntary turnover, engineering', 0.17, 0.10, False)],
}
def fmt(v): return f"{v:.1%}" if isinstance(v, float) and abs(v) < 2 else f"{v:,.0f}" if abs(v) >= 100 else f"{v:,.1f}"
for p, rows in k.items():
    print(p)
    for name, a, t, up in rows:
        gap = (t - a) if up else (a - t)
        status = 'on target' if gap <= 0 else 'gap to close'
print(f" {name:40} actual {fmt(a):>8} target {fmt(t):>8} {status}")Financial Operating margin actual 7.4% target 10.5% gap to close Subscription share of revenue actual 30.2% target 38.0% gap to close Free cash flow (thousands) actual -2,600 target 12,000 gap to close Customer Net revenue retention, subscriptions actual 107.0% target 112.0% gap to close Days sales outstanding actual 82.3 target 62.0 gap to close Customer satisfaction score (of 10) actual 7.6 target 8.4 gap to close Internal Days inventory on hand actual 126 target 100 gap to close Warranty claims per 100 units actual 6.2 target 4.5 gap to close Month-end close (working days) actual 11.0 target 6.0 gap to close Learning Staff completing data-skills training actual 35.0% target 80.0% gap to close Voluntary turnover, engineering actual 17.0% target 10.0% gap to close
Every measure shows a gap to close, which is not surprising in a company whose results have been deteriorating. What matters is that the measures are linked. If Bluestem fixes warranty quality (an internal measure), customer satisfaction and retention should improve, which supports subscription growth and margin (financial measures). If billing and collection improve, days sales outstanding falls and free cash flow rises. A scorecard of unrelated measures is a dashboard; a scorecard of linked measures is a management system.
The targets need care. Some are within management's control and can be set firmly, such as month-end close days. Others depend on customers and markets, such as net revenue retention, and should be set as ranges and reviewed annually. The team recommends no more than about a dozen measures for the board, with more detailed measures for each function. It also recommends that the board pack show each measure's trend over at least eight quarters, because a single number hides direction.
Redesigning incentives
Measures change behavior only if people care about them, and incentives are what make them care. The team recommends three changes to the bonus plan for the board's compensation committee to consider. First, replace part of the revenue weighting with a cash-based measure such as free cash flow or a working capital target, so that executives are rewarded for collecting revenue, not just booking it. Second, base the profit component on a profit measure that does not exclude recurring costs, or define the adjusted measure tightly and have the audit committee review the adjustments. Third, add a quality or customer measure, such as warranty claims per hundred units or net revenue retention, with a modest weight.
For the sales commission plan, the team recommends paying commission when cash is collected rather than when the invoice is issued, removing the fourth-quarter accelerator or replacing it with an annual target, and requiring finance approval of any payment terms beyond the standard. Each change has costs: sales staff may resist being paid later, and the company may lose some deals that depended on long payment terms. The team presents these trade-offs openly. A recommendation that hides its costs is unlikely to be adopted, and if adopted, likely to disappoint.
| Behavior observed | Measure or incentive behind it | Proposed change |
|---|---|---|
| Extended payment terms to close deals | Commission on invoiced revenue | Commission on cash collected; finance approval of terms |
| Year-end bill-and-hold arrangements | Fourth-quarter accelerator; revenue-weighted bonus | Annual targets; cash measure in bonus |
| Recurring costs labeled one-time | Bonus on adjusted EBITDA | Tighter definition reviewed by audit committee |
| Firmware problem not escalated | No quality measure | Warranty claims per 100 units on scorecard and in bonus |
Cost reduction without damage
Management's first instinct when margins fall is often to cut costs. Bluestem cut its collections staff in 2025, which saved about 300,000 dollars a year and, by the team's estimate in Lesson 4, contributed to receivables that now tie up an extra 14 million. Cost reduction must distinguish costs that create value from costs that do not. The team suggests three targets that do not damage the strategy: rationalizing the hardware product range, which has grown to 140 stock-keeping units, many with tiny volumes; renegotiating component contracts using the purchase volumes the company now has; and automating the manual finance processes found in Lesson 6, which would also improve control. It warns against further cuts in collections, quality engineering or customer support, each of which drives a measure on the scorecard.
Evaluating an investment: the cloud data platform
Management is considering a major investment: rebuilding Bluestem Cloud on a modern data platform that would integrate Merrow Lane's analytics, allow new subscription tiers and reduce hosting costs. The proposal estimates a build cost of 6.5 million in year 0 and 2.5 million in year 1, and added subscription contribution rising from 1.8 million in year 1 to 5.3 million in year 6. The team evaluates the proposal with net present value, internal rate of return and payback, using a discount rate of 10.5 percent reflecting the risk of a software project, and tests sensitivity to the benefits.
# Bluestem Water Instruments Inc. (invented), in thousands of dollars, years ended December 31.
YEARS = [2024, 2025, 2026]
IS = {'Hardware revenue': [138000, 149500, 161200], 'Subscription revenue': [44000, 55600, 69800],
      'Hardware cost of sales': [82800, 92700, 104800], 'Subscription cost of sales': [11000, 13300, 16100],
      'Selling, general and admin': [42000, 48500, 56900], 'Research and development': [18200, 21000, 23600],
      'Depreciation': [6200, 6900, 7600], 'Amortization of intangibles': [3000, 4800, 4800],
      'Interest expense': [2100, 3900, 4600], 'Income tax expense': [3300, 2500, 2500]}
BS = {  # balances at December 31, 2023 to 2026
      'Cash': [18000, 24200, 25500, 23400], 'Receivables': [26000, 30000, 39800, 52100],
      'Inventories': [22000, 26000, 31500, 41900], 'Other current assets': [2800, 3000, 3600, 4100],
      'Property, plant and equipment': [45000, 48000, 51000, 53500], 'Right-of-use assets': [13000, 12000, 15500, 14800],
      'Intangible assets': [9000, 6000, 19200, 14400], 'Goodwill': [8000, 8000, 24000, 24000],
      'Payables': [15000, 17000, 19500, 22700], 'Accrued liabilities': [8000, 9000, 10500, 11200],
      'Deferred revenue': [11000, 14000, 18500, 21000], 'Warranty provision': [2300, 2500, 2700, 2600],
      'Income taxes payable': [1200, 1300, 900, 700], 'Lease liabilities': [13500, 13000, 16800, 16300],
      'Borrowings': [28000, 25000, 57000, 60000], 'Deferred tax liabilities': [1800, 2000, 2300, 2700],
      'Share capital': [40000, 40000, 40000, 42000], 'Retained earnings': [23000, 33400, 41900, 49000]}
CF = {'Cash from operations': [20900, 15900, 5800], 'Capital expenditure': [-8000, -8400, -8400],
      'Acquisition of Merrow Lane': [0, -34000, 0], 'Dividends paid': [-3000, -3000, -3000]}
def rev(i): return IS['Hardware revenue'][i] + IS['Subscription revenue'][i]
def cogs(i): return IS['Hardware cost of sales'][i] + IS['Subscription cost of sales'][i]
def ebit(i): return rev(i) - cogs(i) - sum(IS[k][i] for k in ('Selling, general and admin', 'Research and development', 'Depreciation', 'Amortization of intangibles'))
def ni(i): return ebit(i) - IS['Interest expense'][i] - IS['Income tax expense'][i]
ASSETS = ['Cash', 'Receivables', 'Inventories', 'Other current assets', 'Property, plant and equipment', 'Right-of-use assets', 'Intangible assets', 'Goodwill']
CUR_A = ASSETS[:4]
CUR_L = ['Payables', 'Accrued liabilities', 'Deferred revenue', 'Warranty provision', 'Income taxes payable']
LIABS = CUR_L + ['Lease liabilities', 'Borrowings', 'Deferred tax liabilities']
def tot(keys, t): return sum(BS[k][t] for k in keys)

# Lesson 9: should Bluestem build a cloud data platform for its subscriptions? NPV and payback (illustrative).
invest = [-6500, -2500]                     # build cost in years 0 and 1, thousands
gain = [0, 1800, 3200, 4200, 4800, 5100, 5300]   # added subscription contribution, years 0 to 6
rate = 0.105
cash = [invest[0] + gain[0], invest[1] + gain[1]] + gain[2:]
npv = sum(c / (1 + rate) ** t for t, c in enumerate(cash))
cum, payback = 0, None
for t, c in enumerate(cash):
    prev = cum; cum += c
    if payback is None and cum >= 0: payback = t - 1 + (-prev / c)
lo, hi = 0.0, 1.0
for _ in range(100):
    mid = (lo + hi) / 2
    if sum(c / (1 + mid) ** t for t, c in enumerate(cash)) > 0: lo = mid
    else: hi = mid
print("Net cash flows: " + ", ".join(f"y{t} {c:,}" for t, c in enumerate(cash)))
print(f"NPV at {rate:.1%}: {npv:,.0f}; IRR {lo:.1%}; payback {payback:.1f} years")
for shock in (0.8, 0.9, 1.1):
    s = [cash[0], invest[1] + gain[1] * shock] + [g * shock for g in gain[2:]]
print(f" benefits at {shock:.0%} of plan: NPV {sum(c / (1 + rate) ** t for t, c in enumerate(s)):,.0f}")Net cash flows: y0 -6,500, y1 -700, y2 3,200, y3 4,200, y4 4,800, y5 5,100, y6 5,300 NPV at 10.5%: 7,827; IRR 34.5%; payback 3.0 years benefits at 80% of plan: NPV 4,509 benefits at 90% of plan: NPV 6,168 benefits at 110% of plan: NPV 9,486
At the planned benefits, the project has a net present value of about 7.8 million, an internal rate of return of about 35 percent and a payback of about three years. Even at 80 percent of the planned benefits, the net present value remains positive at about 4.5 million. On these numbers the project is attractive. But the team asks the questions ACCT-421 taught. Are the benefits incremental, or would some subscription growth happen anyway? Does the forecast include the costs of migrating existing customers and running two platforms in parallel? Is the six-year horizon reasonable for software, which may need a further rebuild? And, most importantly given Lesson 8, can Bluestem fund 9 million of spending with interest coverage close to its covenant limit?
The team's conclusion is nuanced. The project fits the strategy and has strong economics, but it should be phased and funded from working capital improvements rather than new debt. If Bluestem returns its collection and inventory performance to 2024 levels, it releases more than 20 million, more than twice the project's cost. The team recommends that the board approve a first phase, with a go or no-go review after the working capital plan has released a defined amount of cash and the first new subscription tier has been piloted with customers.
Capital investment decisions also have tax effects that the team did not model in detail. In the United States, domestic software development costs can again be expensed immediately under section 174A, and equipment may qualify for bonus depreciation, which the 2025 tax law made permanent at 100 percent; development work may also qualify for the research credit. Each would improve the project's after-tax return. The team flags them as items for the finance team's full business case.
Worked problem
Linking a measure to a behavior
Bluestem's customer support team is measured on the number of tickets closed per day. Average resolution time has fallen, but repeat tickets for the same site have doubled. What is happening, and what measure would be better?
Show solution
- Closing tickets quickly is rewarded, so staff close them before the problem is fully fixed.
- Customers reopen tickets or file new ones, increasing total work and frustrating customers.
- A better measure is first-contact resolution or the rate of repeat tickets within 30 days, perhaps balanced with customer satisfaction.
- Link it to the scorecard's customer satisfaction and retention measures.
Answer: The measure rewards speed over resolution; replace or balance it with first-contact resolution and repeat-ticket rate.
Common mistakes
MistakeProposing measures that are not linked to the strategy.
InsteadBuild a strategy map first and choose measures that test each link.
MistakeRecommending more measures than anyone can manage.
InsteadLimit the board scorecard to about a dozen linked measures.
MistakeHiding the costs of incentive changes.
InsteadPresent trade-offs, such as sales resistance or lost deals, openly.
MistakeCutting costs that drive value.
InsteadDistinguish value-creating costs, such as collections and quality, from waste.
MistakeApproving an attractive project without checking funding.
InsteadAssess financing capacity and covenant headroom, and phase if needed.
Summary and key terms
- Bluestem's measures reward revenue and adjusted EBITDA but not cash, quality or retention.
- The measures explain the behaviors found: extended terms, year-end arrangements and unescalated quality problems.
- A strategy map and a linked balanced scorecard turn strategy into measures.
- Incentive changes include cash-based bonus measures and commission on cash collected.
- Cost reduction should target waste, not collections, quality or support.
- The cloud platform has strong economics but should be phased and funded from working capital.
- Goal congruence
- Alignment between what managers are rewarded for and what creates value for the organization.
- Strategy map
- A diagram linking objectives in four perspectives through cause and effect.
- Balanced scorecard
- A set of financial and non-financial measures linked to strategy.
- Net revenue retention
- Recurring revenue from existing customers this year as a percentage of their revenue last year, including expansion and churn.
- Internal rate of return (IRR)
- The discount rate at which a project's net present value is zero.
- Payback period
- The time needed for cumulative cash flows to recover the investment.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Name two behaviors explained by Bluestem's current incentives.
Show answer
Extending payment terms to close deals and pushing year-end bill-and-hold arrangements.
Why is goal congruence lacking at Bluestem?
Show answer
Managers are rewarded for revenue and adjusted EBITDA, not for cash, quality or retention, which also create value.
List the four perspectives of a strategy map.
Show answer
Financial, customer, internal process, and learning and growth.
Why should some scorecard targets be set as ranges?
Show answer
They depend on customers and markets beyond management's control.
What change to sales commission does the team recommend?
Show answer
Pay commission when cash is collected, and require finance approval of non-standard payment terms.
Why was cutting collections staff a false economy?
Show answer
It saved about 300,000 dollars a year but contributed to receivables tying up much more cash.
What is the cloud platform's NPV at planned benefits?
Show answer
About 7.8 million at 10.5 percent.
What is the NPV if benefits are 80 percent of plan?
Show answer
About 4.5 million, still positive.
Why does the team recommend phasing the platform?
Show answer
To fund it from working capital improvements and protect covenant headroom, with a go or no-go review.
Give one question to ask about the platform's benefits.
Show answer
Are they incremental, or would some subscription growth happen anyway?
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.