
ACCT-499 · Lesson 2 of 12 · 28 min
Understanding the organization: industry, strategy, governance and filings
An analysis is only as good as the team's understanding of the business it analyses. A falling margin means one thing in a company deliberately investing for growth and another in a company losing pricing power; a rise in receivables means one thing when customers are governments that pay slowly but surely and another when they are small firms under strain. Before calculating a single ratio, the team spends its first three weeks learning how Bluestem makes money, what threatens it, who runs it and how it reports. This lesson covers that work and shows how to find and read the public documents that, in a real capstone, provide most of the evidence.
Finding and reading public filings
In the United States, public companies file with the SEC through EDGAR. A company search returns the annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K for material events, the proxy statement (DEF 14A) for the annual meeting, registration statements and insider filings. The documents are free to view, and the full-text search tool finds a phrase across all filings. For a real capstone, start with the most recent Form 10-K: read Item 1 (business) and Item 1A (risk factors), then Item 7 (MD&A), then the financial statements and notes in Item 8 and the controls disclosures in Item 9A, and finally the proxy statement for governance and executive pay.
| Document | What it tells you | Where to look first |
|---|---|---|
| Form 10-K financial statements and auditor's report | Results, position, cash flows, accounting policies, judgments, auditor's key or critical audit matters | Significant accounting policies and judgments note; segment note; subsequent events |
| MD&A | Management's explanation of results, liquidity, risks and outlook, and its non-GAAP measures | Results of operations; liquidity and capital resources; critical estimates |
| Form 10-K Items 1 and 1A | Business description, competition, customers, risk factors | Risk factors; description of the business |
| Proxy statement (DEF 14A) | Board composition, committees, executive compensation and incentive targets | Compensation discussion and analysis; director independence |
| Form 8-K | Acquisitions, financing, executive changes, restatements | Anything in the last twelve months |
Reading filings well is a skill. Read with questions, not from front to back. Compare what management says in the MD&A with what the numbers show: if MD&A celebrates "record revenue" but says little about cash flow, that silence is information. Read the notes on judgments and estimates, which tell you where the statements are most uncertain. Read the auditor's report for key audit matters (Canada) or critical audit matters (United States), which point to the areas the auditor found hardest. And read last year's documents too: changes in wording between years often reveal more than the words themselves.
Bluestem, being invented, has no real filings; the course provides a client file with the equivalent documents. In your own capstone, remember that public filings are written by management and reviewed by lawyers. They are reliable on facts and cautious on opinions, and they never volunteer a weakness that disclosure rules do not require. Interviews, site visits and internal reports fill the gap.
The industry
Bluestem sells into the water monitoring market. Utilities must test drinking water and wastewater to meet regulations, and environmental agencies, mines and industrial sites must monitor discharges. Demand is driven by regulation, by aging infrastructure, by climate pressures such as floods and droughts, and by the shift from manual sampling to continuous, automated monitoring. Customers are mostly public bodies that buy through formal procurement, pay on government timetables and value reliability over price. Competitors include a few large global instrument makers with broad product ranges and many small specialists. Software platforms are increasingly the point of competition: once a utility's compliance reporting runs on one vendor's cloud service, switching is costly.
A Porter five-forces review, done quickly, helps organize these points. The threat of new entrants is moderate: hardware requires certification and field service, but software start-ups can enter the analytics layer. Buyer power is high, because public procurement forces competitive tenders and large utilities negotiate hard. Supplier power is moderate to high for electronic components, as the supply shocks of recent years showed. Substitutes include manual laboratory testing, which is cheaper per test but slower. Rivalry is intense on hardware price and less intense on integrated software, where Bluestem hopes to compete.
| Force | Assessment | Implication for Bluestem |
|---|---|---|
| New entrants | Moderate | Software start-ups may compete for the analytics layer that Merrow Lane was bought to provide |
| Buyer power | High | Tendered contracts limit hardware pricing; payment terms favor customers |
| Supplier power | Moderate to high | Component costs and lead times affect hardware margins and inventory levels |
| Substitutes | Moderate | Manual sampling remains an option for smaller utilities |
| Rivalry | High in hardware, moderate in software | Margin pressure in hardware pushes the company toward subscriptions |
The business model in numbers
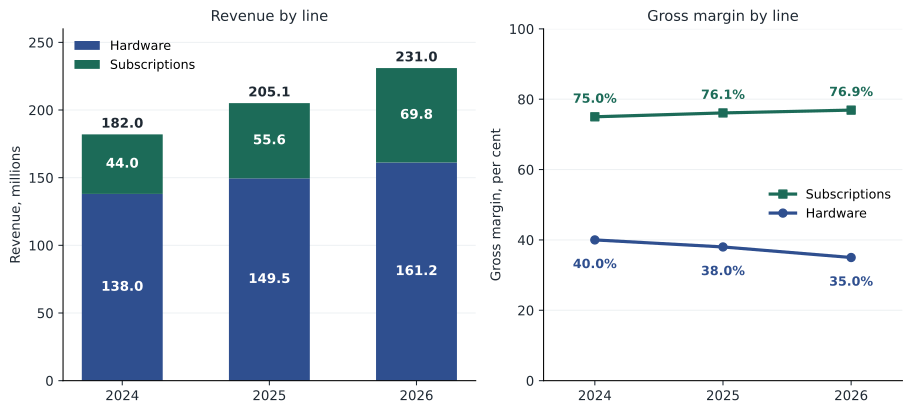
The team next asks how Bluestem's two revenue streams differ. The program below calculates the revenue mix and the gross margin of each line and measures customer concentration using the 2026 customer list.
# Bluestem Water Instruments Inc. (invented), in thousands of dollars, years ended December 31.
YEARS = [2024, 2025, 2026]
IS = {'Hardware revenue': [138000, 149500, 161200], 'Subscription revenue': [44000, 55600, 69800],
      'Hardware cost of sales': [82800, 92700, 104800], 'Subscription cost of sales': [11000, 13300, 16100],
      'Selling, general and admin': [42000, 48500, 56900], 'Research and development': [18200, 21000, 23600],
      'Depreciation': [6200, 6900, 7600], 'Amortization of intangibles': [3000, 4800, 4800],
      'Interest expense': [2100, 3900, 4600], 'Income tax expense': [3300, 2500, 2500]}
BS = {  # balances at December 31, 2023 to 2026
      'Cash': [18000, 24200, 25500, 23400], 'Receivables': [26000, 30000, 39800, 52100],
      'Inventories': [22000, 26000, 31500, 41900], 'Other current assets': [2800, 3000, 3600, 4100],
      'Property, plant and equipment': [45000, 48000, 51000, 53500], 'Right-of-use assets': [13000, 12000, 15500, 14800],
      'Intangible assets': [9000, 6000, 19200, 14400], 'Goodwill': [8000, 8000, 24000, 24000],
      'Payables': [15000, 17000, 19500, 22700], 'Accrued liabilities': [8000, 9000, 10500, 11200],
      'Deferred revenue': [11000, 14000, 18500, 21000], 'Warranty provision': [2300, 2500, 2700, 2600],
      'Income taxes payable': [1200, 1300, 900, 700], 'Lease liabilities': [13500, 13000, 16800, 16300],
      'Borrowings': [28000, 25000, 57000, 60000], 'Deferred tax liabilities': [1800, 2000, 2300, 2700],
      'Share capital': [40000, 40000, 40000, 42000], 'Retained earnings': [23000, 33400, 41900, 49000]}
CF = {'Cash from operations': [20900, 15900, 5800], 'Capital expenditure': [-8000, -8400, -8400],
      'Acquisition of Merrow Lane': [0, -34000, 0], 'Dividends paid': [-3000, -3000, -3000]}
def rev(i): return IS['Hardware revenue'][i] + IS['Subscription revenue'][i]
def cogs(i): return IS['Hardware cost of sales'][i] + IS['Subscription cost of sales'][i]
def ebit(i): return rev(i) - cogs(i) - sum(IS[k][i] for k in ('Selling, general and admin', 'Research and development', 'Depreciation', 'Amortization of intangibles'))
def ni(i): return ebit(i) - IS['Interest expense'][i] - IS['Income tax expense'][i]
ASSETS = ['Cash', 'Receivables', 'Inventories', 'Other current assets', 'Property, plant and equipment', 'Right-of-use assets', 'Intangible assets', 'Goodwill']
CUR_A = ASSETS[:4]
CUR_L = ['Payables', 'Accrued liabilities', 'Deferred revenue', 'Warranty provision', 'Income taxes payable']
LIABS = CUR_L + ['Lease liabilities', 'Borrowings', 'Deferred tax liabilities']
def tot(keys, t): return sum(BS[k][t] for k in keys)

# Lesson 2: revenue mix, gross margin by line and customer concentration (2026 customer list invented).
for i, y in enumerate(YEARS):
    hw, sub = IS['Hardware revenue'][i], IS['Subscription revenue'][i]
    gm_hw = 1 - IS['Hardware cost of sales'][i] / hw
    gm_sub = 1 - IS['Subscription cost of sales'][i] / sub
    print(f"{y}: subscriptions {sub / rev(i):.1%} of revenue; gross margin hardware {gm_hw:.1%}, subscriptions {gm_sub:.1%}")
cust = [('Municipal utility A', 23100), ('Provincial or state agency B', 16200), ('Engineering firm C', 11600),
        ('Municipal utility D', 9200), ('Mining company E', 8100)]
total = rev(2)
top = sum(v for _, v in cust)
print(f"\nTop five customers, 2026: {top:,} of {total:,} ({top / total:.1%})")
for n, v in cust: print(f"  {n:30} {v:>7,} {v / total:6.1%}")
shares = [v / total for _, v in cust] + [(total - top) / total / 200] * 200   # rest spread over about 200 smaller customers
hhi = sum((s * 100) ** 2 for s in shares)
print(f"Herfindahl index of customer shares: {hhi:,.0f} (under 1,000 is usually read as unconcentrated)")2024: subscriptions 24.2% of revenue; gross margin hardware 40.0%, subscriptions 75.0% 2025: subscriptions 27.1% of revenue; gross margin hardware 38.0%, subscriptions 76.1% 2026: subscriptions 30.2% of revenue; gross margin hardware 35.0%, subscriptions 76.9% Top five customers, 2026: 68,200 of 231,000 (29.5%) Municipal utility A 23,100 10.0% Provincial or state agency B 16,200 7.0% Engineering firm C 11,600 5.0% Municipal utility D 9,200 4.0% Mining company E 8,100 3.5% Herfindahl index of customer shares: 227 (under 1,000 is usually read as unconcentrated)
Three facts stand out. Subscriptions grew from 24 to 30 percent of revenue, and their gross margin, near 77 percent, is twice that of hardware. Hardware gross margin fell from 40 to 35 percent, which is the main reason consolidated gross margin is slipping despite the richer mix. And while the five largest customers provide almost 30 percent of revenue, the customer base as a whole is not concentrated; the Herfindahl index is low because hundreds of smaller utilities make up the rest. The largest customer, at 10 percent, still deserves attention: losing a contract of that size would hurt, and governments sometimes re-tender at the end of a term.
Strategy
Bluestem's stated strategy, from its MD&A and the chief executive's interview, is to become "the monitoring platform for water": to use hardware sales to win sites and then earn recurring subscription revenue for years afterwards. The Merrow Lane acquisition added predictive analytics that management expected to raise subscription prices. The strategy is coherent and matches industry trends. The team's job is not to second-guess it but to test whether the company's results, controls and investments support it. A SWOT analysis frames the questions.
| Strengths | Weaknesses |
|---|---|
| Installed base of about 4,000 monitored sites; high subscription margins; reputation with utilities | Falling hardware margin; slow collections; rising inventory; manual finance processes; integration of Merrow Lane behind plan |
| Opportunities | Threats |
| Stricter monitoring rules; infrastructure funding programs; predictive analytics; mining and industrial customers | Large competitors bundling software; component costs; procurement delays; cyber attacks on utility systems |
A PESTEL scan adds the wider environment: political and legal factors such as drinking water regulations and government infrastructure funding; economic factors such as interest rates, which raise Bluestem's borrowing costs and slow municipal capital spending; social expectations about clean water after well-publicized contamination events; technological change in sensors and artificial intelligence; and environmental pressures from climate change. Each factor matters to the engagement only if it affects the questions in scope. Infrastructure funding, for example, matters because it affects the timing of orders and therefore the year-end revenue cut-off issues the team will find in Lesson 5.
Governance and the control environment
Governance tells the team who is accountable and how decisions are made. Bluestem's board has seven directors, five independent. The audit committee has three independent members, one of whom, Martin Ruel, is a CPA and the committee chair. The chief executive founded the company and owns 11 percent of the shares. Executive bonuses depend on revenue growth and adjusted EBITDA, with no cash flow measure. The internal audit function is one person who reports to the chief financial officer.
Each of these facts shapes the risk assessment. A founder with a large shareholding brings commitment but also influence over the board. Bonuses tied to revenue and adjusted EBITDA, with no cash measure, create an incentive to book revenue early and to stretch payment terms to win sales: exactly the pressures that could explain rising receivables. An internal audit function reporting to the chief financial officer lacks independence and capacity. None of this proves a problem; it tells the team where to look. The fraud triangle from ACCT-460 is useful here: incentive (bonus targets), opportunity (manual processes and weak segregation) and rationalization ("everyone in the industry ships ahead of quarter-end").
As a listed company, Bluestem provides management's report on internal control over financial reporting and the auditor's attestation under section 404 of the Sarbanes-Oxley Act, depending on its filer status. Management assesses internal control over financial reporting against a framework, usually COSO 2013, and reports its conclusion in Item 9A; if Bluestem is an accelerated filer, its auditor also attests to internal control. The team's controls review in Lesson 6 is narrower than either, but it looks at the processes behind the issues the financial analysis raises.
The risk profile
The team closes its first phase with a short risk profile: the five or six risks most likely to matter to the questions in scope, each linked to evidence and to the workstream that will investigate it. This document becomes the backbone of the interim meeting in week 6.
| Risk | Evidence so far | Workstream |
|---|---|---|
| Revenue recorded before control passes at year end | Receivables up 74 percent in two years; bonus tied to revenue; bill-and-hold arrangements mentioned in interviews | Reporting issues, controls |
| Hardware margin erosion continues | Gross margin down 5 points; component costs; tendered pricing | Financial analysis, strategy |
| Working capital absorbs cash | Cash from operations 5.8 million against net income 10.1 million | Financial analysis |
| Merrow Lane does not deliver expected returns | Integration behind plan; intangible amortization; goodwill of 16 million from the deal | Reporting issues, strategy |
| Weak access and journal controls | Small finance team; manual close; internal audit reports to the CFO | Controls, analytics |
| Financing pressure if cash flow stays weak | Borrowings up from 25 to 60 million; interest coverage falling | Tax and finance |
Worked problem
Reading a disclosure change
Last year Bluestem's revenue recognition note said hardware revenue is recognized "on delivery." This year it says "when control transfers to the customer, generally on delivery, or earlier where the customer has requested that we hold goods on its behalf." What should the team do?
Show solution
- Recognize the new wording as a signal: it describes bill-and-hold arrangements, which carry specific criteria under ASC 606.
- Ask management how many arrangements there were in 2026, their value, and why customers requested them.
- Obtain the contracts and customer requests for the year-end arrangements and test them against the criteria in Lesson 5.
- Link the issue to the revenue cut-off control in Lesson 6 and to the incentive created by revenue-based bonuses.
Answer: Treat the wording change as a lead: quantify the arrangements, test them against the bill-and-hold criteria, and link them to controls and incentives.
Common mistakes
MistakeReading filings from front to back without questions.
InsteadRead with specific questions: compare MD&A claims with the numbers, and read judgments, auditor's matters and year-to-year wording changes.
MistakeTreating a five-forces or SWOT table as the analysis.
InsteadUse the frameworks to organize evidence and to decide where to look, then test with numbers.
MistakeAssuming customer concentration from the top customer alone.
InsteadMeasure the whole distribution, but still assess the effect of losing the largest customers.
MistakeIgnoring incentive structures.
InsteadLink bonus targets to the risks they could create, such as early revenue recognition.
MistakeMaking claims about a real company based on a quick read of its filings.
InsteadConfine conclusions to what the evidence supports and, in a course setting, use invented or anonymized data.
Summary and key terms
- US public companies file on EDGAR; read Items 1, 1A, 7, 8 and 9A of the Form 10-K and the proxy statement with specific questions.
- Industry frameworks such as five forces, SWOT and PESTEL organize evidence and point to risks.
- Bluestem's subscriptions earn twice the gross margin of hardware, but hardware margins are falling.
- Governance facts, especially incentives, shape where the team looks for problems.
- A short risk profile links each key risk to evidence and to the workstream that will test it.
- Form 10-K
- The annual report a US public company files with the SEC.
- Proxy statement
- The document sent to shareholders before a meeting, including governance and compensation.
- Five forces
- Porter's framework of new entrants, buyer power, supplier power, substitutes and rivalry.
- SWOT
- Strengths, weaknesses, opportunities and threats.
- PESTEL
- Political, economic, social, technological, environmental and legal factors.
- Herfindahl index
- The sum of squared market or customer shares, a measure of concentration.
- Risk profile
- A short list of the most important risks, each linked to evidence and a response.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Where would you find a US public company's proxy statement?
Show answer
On EDGAR, filed as form type DEF 14A.
Why compare this year's notes with last year's?
Show answer
Changes in wording often signal new arrangements, judgments or problems.
Which Bluestem revenue line has the higher gross margin, and by how much in 2026?
Show answer
Subscriptions, about 76.9 percent against 35.0 percent for hardware.
Why is buyer power high in Bluestem's market?
Show answer
Public customers buy through competitive tenders and negotiate prices and terms.
How could Bluestem's bonus design affect the engagement?
Show answer
Revenue and adjusted EBITDA targets with no cash measure create incentives to recognize revenue early and extend payment terms.
Why does the internal audit reporting line matter?
Show answer
Reporting to the CFO reduces independence; internal audit should report functionally to the audit committee.
What does a Herfindahl index of about 230 suggest?
Show answer
The customer base as a whole is not concentrated.
Name two PESTEL factors that affect the timing of Bluestem's orders.
Show answer
Infrastructure funding programs and interest rates affecting municipal capital spending.
What is the purpose of the week-3 risk profile?
Show answer
To focus fieldwork on the risks most likely to matter and to structure the interim meeting.
Why should a course avoid analyzing a named real company?
Show answer
Its findings could be mistaken for genuine conclusions about that company.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.