
ACCT-102 · Lesson 9 of 12 · 32 min
Relevant costs for decision making
Managers make decisions every day that are not about the whole budget but about a single choice between alternatives. Should we accept a discounted order? Make a part ourselves or buy it? Keep a product line that appears to lose money? Which product should get the limited time on our busiest machine? Should we sell a product as it is or process it further? Replace an old machine? Each of these decisions has the same structure: compare the future costs and revenues that differ between the alternatives, and ignore everything else. This lesson develops that discipline, called relevant costing or differential analysis, and applies it to six common decisions at Cedar Ridge. Decisions whose effects span many years, such as buying major equipment, also need the time value of money, covered in FIN-201 lessons 7 to 9; here the focus is on short-term choices.
What makes a cost or revenue relevant
A cost or revenue is relevant to a decision if it meets two tests: it is a future amount, and it differs between the alternatives being considered. Costs already incurred (sunk costs) fail the first test; no decision can change them. Future costs that will be the same whatever is chosen fail the second; including them does no harm if they are included for every alternative, but leaving them out keeps the analysis focused. Opportunity costs, the benefits given up by choosing one alternative, are relevant even though they never appear in the ledger.
| Item | Relevant? | Why |
|---|---|---|
| Variable cost of making extra chairs | Yes | Future and differs with the decision |
| Fixed factory lease when capacity is idle | No | Same whether or not the order is accepted |
| Price paid last year for a machine | No | Sunk |
| Book value and depreciation of an old machine | No | Based on sunk cost |
| Salvage value of the old machine if replaced | Yes | Future cash that differs between keeping and replacing |
| Contribution lost on displaced regular sales | Yes | Opportunity cost |
| Allocated head-office costs that will not change | No | Same under both alternatives |
| Supervisor salary that ends if a line is dropped | Yes | Avoidable fixed cost |
Two cautions follow. First, fixed costs are not automatically irrelevant: a fixed cost that would be avoided, such as a supervisor laid off if a line closes or a rental that ends, is relevant. Second, unit costs are dangerous. A unit cost that includes allocated fixed overhead looks like a variable cost but is not; multiplying it by extra units overstates the cost of additional output, as lesson 2 warned. Work with total costs and total revenues for each alternative whenever possible.
Decision 1: a special order
A hotel chain offers to buy 500 Classic chairs at $130 each, branded with its logo. The regular price is $180 and the absorption cost is $132, so at first glance the order loses money. But the plant can make 8,500 chairs a year and expects to make 7,200, so there is idle capacity. The hotel will collect the chairs itself, so there is no freight or commission. A logo stencil and set-up will cost $2,000.
# Special order: 500 branded chairs at $130 (illustrative)
qty, offer = 500, 130
variable_mfg = 102          # DM 60 + DL 30 + variable overhead 12
variable_selling = 0        # customer collects; no commission
one_time = 2_000            # logo stencil and set-up

revenue = qty * offer
relevant_cost = qty * (variable_mfg + variable_selling) + one_time
print(f"Incremental revenue  ${revenue:,}")
print(f"Incremental cost     ${relevant_cost:,}")
print(f"Effect on income     ${revenue - relevant_cost:+,}")
print(f"Lowest acceptable price per chair: ${(relevant_cost) / qty:.2f}")Incremental revenue $65,000 Incremental cost $53,000 Effect on income $+12,000 Lowest acceptable price per chair: $106.00
Accepting the order raises operating income by $12,000. Fixed overhead of $216,000 will be incurred anyway, so the $30 per chair of fixed overhead in the absorption cost is irrelevant. The minimum price that covers the incremental cost is $106 per chair. The analysis changes if the plant were at full capacity: accepting would then displace regular sales, and the contribution margin lost on those sales ($72 per chair) becomes an opportunity cost that the special price must also cover.
Worked problem
A special order at full capacity
Suppose the plant is fully booked, so accepting the 500-chair order means giving up 500 regular sales. Should Cedar Ridge accept at $130?
Show solution
- Incremental revenue = 500 × $130 = $65,000.
- Incremental costs = 500 × $102 + $2,000 = $53,000.
- Opportunity cost = lost contribution on regular sales = 500 × $72 = $36,000.
- Net effect = $65,000 − $53,000 − $36,000 = −$24,000.
- The break-even price is ($53,000 + $36,000) ÷ 500 = $178 per chair.
Answer: Reject at $130; at full capacity the order would need a price of at least $178.
Qualitative factors matter too. Will regular customers learn of the discount and demand the same price? Do competition laws restrict price discrimination between competing buyers? Will the hotel become a repeat customer? Will the order strain staff or quality? A positive number is the start of the decision, not the end.
In the United States, the Robinson-Patman Act can prohibit price discrimination between competing purchasers of goods of like grade and quality where the effect may be to lessen competition, subject to defenses such as cost justification and meeting competition. A branded order for a hotel chain that does not compete with Cedar Ridge's furniture retailers is unlikely to raise an issue, but firms should take advice when discounting to some resellers and not others.
Decision 2: make or buy
Cedar Ridge makes the upholstered seat cushions for its chairs. A supplier offers to provide them for $13.50 each. The cost accountant's unit cost for making a cushion is $16, made up of direct materials $7, direct labor $4, variable overhead $1.50 and fixed overhead $3.50 allocated per cushion at 7,000 cushions a year. Of the fixed overhead, $9,800 a year is the salary of a part-time upholstery supervisor who would be let go if cushions were bought; the rest is allocated plant overhead that would continue. If cushions are bought, the upholstery area could be rented to a neighboring business for $6,000 a year.
# Make or buy seat cushions, 7,000 a year (illustrative)
units = 7_000
make_variable = 7 + 4 + 1.50          # DM, DL, variable overhead per cushion
avoidable_fixed = 9_800               # supervisor salary avoided if we buy
rent_forgone = 6_000                  # opportunity cost of making
buy_price = 13.50

make = units * make_variable + avoidable_fixed + rent_forgone
buy = units * buy_price
print(f"Relevant cost to make: ${make:,.0f}")
print(f"Relevant cost to buy:  ${buy:,.0f}")
print(("Buy" if buy < make else "Make") + f" saves ${abs(make - buy):,.0f} a year")Relevant cost to make: $103,300 Relevant cost to buy: $94,500 Buy saves $8,800 a year
The full unit cost of $16 is misleading: $2.10 of the $3.50 of fixed overhead per cushion would continue after outsourcing, so it is irrelevant. The relevant cost of making is the variable cost ($87,500), the avoidable supervisor salary ($9,800) and the rent forgone by using the space ($6,000), a total of $103,300, against $94,500 to buy. Buying saves $8,800 a year. Without the rental opportunity, buying would still save $2,800. Before deciding, managers should consider the supplier's quality and reliability, the risk of price increases once in-house capability is lost, the effect on employees, and whether cushions are a source of competitive advantage. Make-or-buy decisions are a form of outsourcing decision, and the same logic applies to services such as payroll, cleaning and IT.
Decision 3: keeping or dropping a product line
After its first year, the trestle bench appears to lose money on a segment report that allocates common fixed costs to products. The question is whether dropping it would raise Cedar Ridge's income. The answer depends on which costs would disappear with the bench: its contribution margin would be lost, its traceable fixed costs would be avoided, but the common fixed costs allocated to it would remain and be shifted onto the other products.
| Trestle bench line | Amount |
|---|---|
| Sales (1,400 × $300) | $420,000 |
| Variable costs (1,400 × $195) | $273,000 |
| Contribution margin | $147,000 |
| Traceable fixed costs (jig, part-time finisher, catalog space) | $89,400 |
| Segment margin | $57,600 |
| Allocated common fixed costs (share of plant manager, building, administration) | $70,000 |
| Reported "loss" | ($12,400) |
Worked problem
Should the bench be dropped?
Using the segment report, determine the effect on Cedar Ridge's operating income of dropping the bench line, assuming the allocated common costs would not change.
Show solution
- Contribution margin lost: $147,000.
- Traceable fixed costs avoided: $89,400.
- Common fixed costs avoided: $0; the $70,000 would be reallocated to chairs and custom work.
- Change in income = −$147,000 + $89,400 = −$57,600.
Answer: Keep the bench. Dropping it would reduce operating income by its segment margin of $57,600; the reported loss is caused by allocated costs that would remain.
The conclusion could change if the space and equipment used for benches could earn more in another use, for example by expanding custom work, or if bench sales help sell chairs (complementary demand), in which case dropping benches would also cost some chair sales. A careful analysis includes those effects.
Decision 4: using a constrained resource
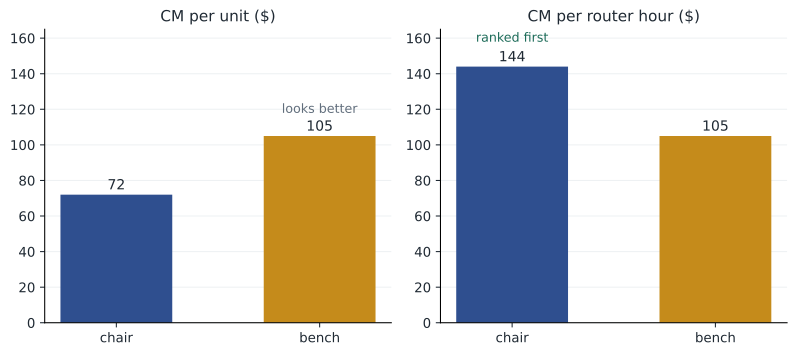
When a resource limits output, the product with the highest contribution margin per unit is not necessarily the most profitable to make. What matters is the contribution margin per unit of the constrained resource. Cedar Ridge's CNC router has 5,000 hours available next year. A chair needs 0.5 router hours and earns $72 of contribution margin; a bench needs 1.0 router hour and earns $105. Market demand is at most 8,000 chairs and 2,000 benches.
# Allocating 5,000 router hours between chairs and benches (illustrative)
hours_available = 5_000
products = {  # name: (CM per unit, router hours per unit, max demand)
    "chair": (72, 0.5, 8_000),
    "bench": (105, 1.0, 2_000),
}
ranked = sorted(products.items(), key=lambda kv: kv[1][0] / kv[1][1], reverse=True)
for name, (cm, hrs, demand) in ranked:
    print(f"{name}: CM per router hour ${cm / hrs:.0f}")

left, total_cm = hours_available, 0
for name, (cm, hrs, demand) in ranked:
    make = min(demand, left / hrs)
    left -= make * hrs
    total_cm += make * cm
    plural = {"chair": "chairs", "bench": "benches"}[name]
    print(f"Make {make:,.0f} {plural} using {make * hrs:,.0f} hours")
print(f"Total contribution margin ${total_cm:,.0f}")chair: CM per router hour $144 bench: CM per router hour $105 Make 8,000 chairs using 4,000 hours Make 1,000 benches using 1,000 hours Total contribution margin $681,000
Per router hour, a chair earns $144 and a bench $105, so chairs get priority despite their lower margin per unit. Making 8,000 chairs uses 4,000 hours; the remaining 1,000 hours make 1,000 benches. Total contribution margin is $681,000. Giving benches priority instead (2,000 benches, then 6,000 chairs) would earn $642,000. With several constraints at once, the problem becomes a linear program, which spreadsheet solvers handle; ACCT-341 introduces optimization. In the longer run, managers can also relax the constraint (elevate it, in theory-of-constraints language) by adding a shift, buying a second router or outsourcing some machining, if the extra contribution exceeds the cost.
Decision 5: sell now or process further
Some products can be sold at an intermediate stage or processed further. Cedar Ridge could sell assembled but unfinished ready-to-paint chairs to a do-it-yourself retailer for $150, or finish them and sell them for $180. Finishing costs $22 per chair in incremental materials, labor and variable overhead; the finishing department has spare capacity. The costs incurred up to the split (Assembly costs) are the same either way and are irrelevant.
Worked problem
Process further?
Should Cedar Ridge finish the chairs or sell them unfinished?
Show solution
- Incremental revenue from finishing = $180 − $150 = $30 per chair.
- Incremental cost of finishing = $22 per chair.
- Incremental profit = $30 − $22 = $8 per chair.
- The $108 of Assembly cost per chair is incurred either way and is irrelevant.
Answer: Finish the chairs, which adds $8 per chair, unless finishing capacity has a more valuable use.
The same rule, compare incremental revenue with incremental cost beyond the split-off point, applies to joint products, such as the lumber and wood chips that come from a single log. How joint costs are allocated for inventory valuation is covered in ACCT-222, but joint costs are irrelevant to the decision to process further.
Decision 6: replacing equipment and the sunk cost trap
Cedar Ridge's old spray booth cost $80,000 four years ago and has a book value of $30,000. A new, more efficient booth costs $60,000 and would cut operating costs (energy, filters, rework) by $18,000 a year for four years. The old booth could be sold today for $5,000; in four years both booths would be worthless. The book value of the old booth is sunk: it reflects money spent four years ago and will be written off one way or another, through depreciation if kept or as a loss on disposal if sold.
# Replace the spray booth? Four-year totals, ignoring the time value of money (illustrative)
new_cost, salvage_old = 60_000, 5_000
annual_saving, years = 18_000, 4
book_value_old = 30_000   # sunk: shown only to prove it cancels out

keep = 0                                             # baseline
replace = -new_cost + salvage_old + annual_saving * years
print(f"Net advantage of replacing over {years} years: ${replace - keep:,}")

# Including book value in both alternatives changes nothing
keep_bv = -book_value_old                            # depreciated over 4 years
replace_bv = -book_value_old + replace               # written off as a loss now
print(f"With book value in both: ${replace_bv - keep_bv:,}")Net advantage of replacing over 4 years: $17,000 With book value in both: $17,000
Replacing yields a net advantage of $17,000 over four years before considering the time value of money: $72,000 of savings plus $5,000 of salvage, less $60,000. The old booth's $30,000 book value affects both alternatives equally and cancels. Managers sometimes resist replacing an asset because they do not want to record a loss on disposal, which is exactly the sunk cost trap; the loss is an accounting entry, not a future cash flow. A complete analysis would discount the cash flows, include tax effects of depreciation and the disposal (CCA or MACRS), and test the estimate of savings, as FIN-201 shows.
Pricing decisions and target costing
Relevant costing also informs pricing. For short-term or one-off pricing with idle capacity, the floor is the incremental cost. For long-term pricing, prices must cover full costs and a return on investment, which is why many companies use cost-plus pricing based on absorption or full cost (lesson 5 priced custom jobs at cost plus 40 percent). Target costing reverses the logic: start with the price the market will bear, subtract the desired profit, and design the product and process so that its cost does not exceed the target. If Cedar Ridge believes a new armchair will sell for $240 and wants a 25 percent margin on price, the target cost is $180, and designers must find a way to build it for that.
Common mistakes
MistakeIncluding sunk costs, such as book value, in a decision.
InsteadSunk costs cannot be changed by any decision; ignore them.
MistakeTreating all fixed costs as irrelevant.
InsteadAvoidable fixed costs, such as a supervisor laid off, are relevant.
MistakeUsing full unit costs with allocated fixed overhead to evaluate extra output.
InsteadUse incremental total costs; allocated fixed overhead usually does not change.
MistakeRanking products by contribution margin per unit when a resource is constrained.
InsteadRank by contribution margin per unit of the constrained resource.
MistakeDropping a segment because it shows a loss after allocated common costs.
InsteadCompare the segment margin lost with any avoidable costs and alternative uses of capacity.
Summary and key terms
- Relevant costs and revenues are future amounts that differ between alternatives.
- Sunk costs are irrelevant; avoidable fixed costs and opportunity costs are relevant.
- Special orders with idle capacity need only cover incremental costs; at full capacity they must also cover lost contribution.
- Make-or-buy compares the purchase price with avoidable costs of making plus any opportunity cost of the space or capacity.
- Keep a segment if its segment margin is positive, unless its capacity has a better use.
- With a constraint, rank products by contribution margin per unit of the constrained resource.
- Process further if incremental revenue exceeds incremental cost; costs before split-off are irrelevant.
- Relevant cost
- A future cost that differs between alternatives.
- Differential analysis
- Comparing the revenues and costs that differ between alternatives.
- Sunk cost
- A cost already incurred that no decision can change.
- Avoidable cost
- A cost that can be eliminated by choosing one alternative over another.
- Opportunity cost
- The benefit forgone by choosing one alternative over the next best.
- Special order
- A one-time order, usually at a price below the regular price.
- Make-or-buy decision
- A decision whether to produce an item internally or purchase it.
- Constrained resource
- A resource whose limited capacity restricts output.
- Split-off point
- The stage at which a product can be sold or processed further, or joint products become separable.
- Target costing
- Setting the allowable cost of a product as the market price less the desired profit.
Practice problems
Work each problem on paper first, then reveal the answer to check.
With idle capacity, what is the minimum price for a special order with variable cost $40 per unit and a one-time cost of $3,000 for 1,000 units?
Show answer
$43 per unit.
If the plant were full and each regular unit had a $25 contribution margin, what would the minimum price be?
Show answer
$43 + $25 = $68 per unit.
A part costs $20 to make ($12 variable, $8 allocated fixed, of which $2 is avoidable). A supplier offers $15. Make or buy?
Show answer
Relevant make cost $14 < $15: make, unless the space has another use worth more than $1 per part.
A segment has a contribution margin of $80,000, traceable fixed costs of $95,000 and allocated common costs of $30,000. Should it be dropped?
Show answer
Its segment margin is −$15,000, so dropping it raises income by $15,000 (if no other effects).
Product X earns $30 CM using 2 machine hours; Y earns $24 using 1 hour. Which has priority when machine hours are scarce?
Show answer
Y: $24 per hour against $15.
A product sells for $50 at split-off or $70 after further processing costing $15. Process further?
Show answer
Yes: +$5 per unit.
Why is the old spray booth's book value irrelevant?
Show answer
It reflects a sunk cost; it is written off whether the booth is kept or sold.
Name two qualitative factors in a make-or-buy decision.
Show answer
Quality, supplier reliability, loss of capability, employee effects, confidentiality.
What is the target cost of a product expected to sell for $500 with a desired margin of 30 percent of price?
Show answer
$350.
Change the router program to 4,500 hours. What is the best mix and total CM?
Show answer
8,000 chairs (4,000 h) and 500 benches; CM = 576,000 + 52,500 = $628,500.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.