
ECON-102 · Lesson 6 of 12 · 29 min
Saving, investment and the financial system
Lesson 5 showed that capital accumulation raises output per worker. But capital has to be paid for. Factories, machines, software, roads and houses are financed out of saving, either by the people and firms who build them or by savers who lend to them. The financial system, made up of banks, bond and stock markets, pension funds, insurance companies and other institutions, channels saving from those who have it to those who can use it productively. This lesson explains the accounting link between saving and investment, the market for loanable funds that determines real interest rates, how government deficits affect that market, and the main financial institutions. The details of valuing financial assets and managing portfolios are left to FIN-201 and FIN-301.
Saving equals investment
Start with the expenditure identity from lesson 2 for a closed economy, one with no trade: \( Y = C + I + G \). Rearranging gives \( Y - C - G = I \). The left side is national saving, \( S \): the income of the economy left over after paying for consumption and government purchases. So in a closed economy, saving must equal investment. National saving can be split into private saving, the income households have left after taxes and consumption, and public saving, the government's tax revenue minus its spending (including transfers). If \( T \) is taxes net of transfers, private saving is \( Y - T - C \) and public saving is \( T - G \).
Public saving is the government budget balance. When the government runs a surplus, public saving is positive and adds to national saving; when it runs a deficit, public saving is negative and reduces national saving. In an open economy, investment can also be financed by borrowing from abroad, so \( S = I + NX \), where net exports measure the net flow of saving to the rest of the world. Lesson 11 develops this link between saving, investment and the trade balance.
Worked problem
National saving
GDP is 3,000, consumption 1,700, government purchases 650, taxes net of transfers 600 (billions). Calculate private saving, public saving, national saving and investment in a closed economy.
Show solution
- Private saving = Y − T − C = 3,000 − 600 − 1,700 = 700.
- Public saving = T − G = 600 − 650 = −50 (a deficit).
- National saving = 700 − 50 = 650.
- Investment = Y − C − G = 3,000 − 1,700 − 650 = 650.
Answer: Saving and investment both equal 650. The government deficit absorbs 50 of private saving.
The market for loanable funds
The loanable funds model treats saving and investment as supply and demand in a single market where the price is the real interest rate. Savers supply loanable funds: at a higher real interest rate, saving is more rewarding, so the quantity supplied rises, at least modestly. Borrowers, mainly firms planning investment projects and households buying homes, demand loanable funds: at a higher real interest rate, fewer projects are profitable, so the quantity demanded falls. The equilibrium real interest rate balances the two. The model simplifies a complex financial system into one market, but it captures how changes in saving, investment demand and government borrowing affect interest rates in the long run.
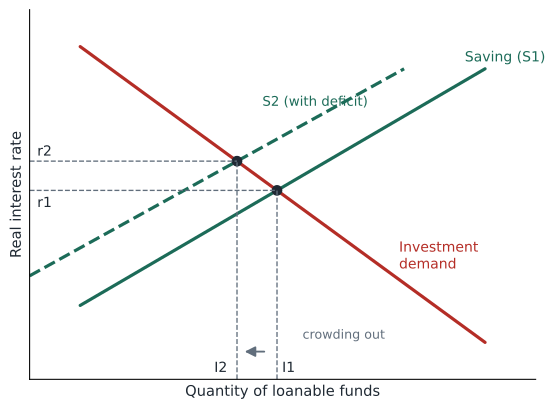
Several policies and events shift the curves. An investment tax credit or a wave of optimism about new technology shifts investment demand to the right, raising both the interest rate and the amount saved and invested. A tax incentive that encourages households to save more shifts the supply of saving to the right, lowering the interest rate and raising investment. A government deficit shifts national saving to the left, because public saving falls, raising the interest rate and reducing private investment. This last effect is called crowding out.
Worked problem
Crowding out in the loanable funds market
Saving is \( S = 400 + 50r \) and investment demand is \( I = 900 - 50r \), with r the real interest rate in per cent and amounts in billions. The government then runs a deficit of 100, which reduces national saving at every interest rate. Find the equilibrium before and after.
Show solution
- Before: 400 + 50r = 900 − 50r, so 100r = 500 and r = 5 %. Investment = 650.
- After: national saving = 300 + 50r.
- 300 + 50r = 900 − 50r gives r = 6 %.
- Investment = 900 − 300 = 600; private saving = 400 + 300 = 700, of which 100 finances the deficit.
Answer: The real interest rate rises one point and private investment falls by 50. Half the deficit is financed by extra private saving and half by crowding out investment.
# Loanable funds equilibrium and crowding out (linear curves, r in %)
def equilibrium(s0, s1, i0, i1, deficit=0.0):
    # national saving = s0 - deficit + s1*r ; investment = i0 - i1*r
    r = (i0 - s0 + deficit) / (s1 + i1)
    return r, i0 - i1 * r

for d in (0, 100, 200):
    r, inv = equilibrium(400, 50, 900, 50, deficit=d)
print(f"deficit {d:3d}: real rate {r:4.1f} % investment {inv:5.0f} crowded out {650 - inv:4.0f}")deficit 0: real rate 5.0 % investment 650 crowded out 0 deficit 100: real rate 6.0 % investment 600 crowded out 50 deficit 200: real rate 7.0 % investment 550 crowded out 100
How large is crowding out in practice? It depends on how responsive saving and investment are to interest rates, on whether the economy is at full employment, and on whether foreign capital flows in. In a deep recession with idle resources and low interest rates, government borrowing may crowd out little private spending, and may even crowd it in by raising incomes. In a small open economy such as Canada's, interest rates are strongly influenced by global rates, so government borrowing may be financed partly by foreign lenders, which shows up as a larger trade deficit rather than less domestic investment. Lesson 10 returns to these debates.
Nominal and real interest rates
The interest rates quoted by banks are nominal interest rates. What matters for savers and borrowers is the real interest rate, which adjusts for inflation. The relationship, named after the economist Irving Fisher, is approximately: real interest rate equals nominal interest rate minus expected inflation. If a bank pays 4 % on a deposit and inflation is 3 %, the saver's purchasing power grows only about 1 %. Because inflation is not known in advance, borrowers and lenders base decisions on expected inflation; the realized real rate can differ from the expected one if inflation turns out higher or lower.
Worked problem
The Fisher equation
A five-year loan carries a nominal interest rate of 6 %. Expected inflation is 2.5 %. What is the expected real interest rate? If inflation turns out to be 4 %, what is the realized real rate, and who gains?
Show solution
- Expected real rate ≈ 6 − 2.5 = 3.5 % (exactly 1.06 ÷ 1.025 − 1 = 3.41 %).
- Realized real rate ≈ 6 − 4 = 2 % (exactly 1.92 %).
- The borrower repays in dollars worth less than expected.
Answer: The borrower gains and the lender loses from the unexpected inflation, illustrating the redistribution described in lesson 3.
The nominal interest rate cannot easily fall much below zero, because people could hold cash instead. Real interest rates, however, can be negative when inflation exceeds nominal rates, as they were in 2021–2022, when nominal policy rates were near zero and inflation was high. Negative real rates encourage borrowing and spending but penalize savers.
The neutral interest rate
Economists use the term neutral real interest rate (sometimes called r-star) for the real rate that is consistent with output at potential and stable inflation, neither stimulating nor restraining the economy. It is determined by long-run forces in the global loanable funds market: saving behaviour, population ageing, productivity growth, the demand for safe assets and government borrowing. Estimates of the neutral real rate in advanced economies fell from around 2 to 3 % in the 1990s to well under 1 % in the 2010s, a decline often attributed to ageing populations saving more for retirement, slower productivity growth and strong demand for safe assets. Since 2020 some estimates have edged up, as government debt has risen and investment in clean energy and AI has increased. The Bank of Canada estimates the neutral nominal policy rate at 2.25 to 3.25 %, and the median long-run projection of Federal Reserve policymakers has been around 3 %. Lesson 8 shows how central banks use these estimates.
The financial system
Financial markets allow savers to lend directly to borrowers. In the bond market, governments and corporations borrow by issuing bonds, promises to pay interest and repay the principal at a fixed date. Bond yields depend on the term (longer bonds usually pay more), credit risk (riskier borrowers pay more) and tax treatment. In the stock market, firms raise funds by selling shares of ownership, and shareholders receive dividends and capital gains if the firm prospers. Financial intermediaries stand between savers and borrowers. Banks accept deposits and make loans, using their expertise to assess and monitor borrowers. Pension funds, insurance companies and mutual funds pool savings and invest them in diversified portfolios.
Intermediaries perform several valuable functions. They reduce transaction costs and information problems, because evaluating borrowers is expensive. They allow diversification, spreading risk across many investments. They transform maturity, turning short-term deposits that savers can withdraw at any time into long-term loans such as mortgages. And they provide liquidity. These functions also create fragility, as lesson 7 explains: when depositors or investors lose confidence, intermediaries can face runs.
| Institution | Role in Canada |
|---|---|
| Chartered banks | Six large banks hold most deposits and mortgages; regulated by OSFI |
| Credit unions and caisses populaires | Member-owned; Desjardins is the largest in Quebec |
| Pension funds | Large public plans such as the Canada Pension Plan Investment Board, Caisse de dépôt et placement and Ontario Teachers' invest globally |
| Securities markets | Toronto Stock Exchange; regulated by provincial securities commissions |
| Crown financial corporations | Canada Mortgage and Housing Corporation insures mortgages; Business Development Bank of Canada lends to small firms |
Policies to encourage saving
Canadian governments encourage saving through tax-advantaged accounts. Contributions to a Registered Retirement Savings Plan (RRSP) are deductible from taxable income and taxed on withdrawal; income in a Tax-Free Savings Account (TFSA) grows tax free and withdrawals are not taxed; the First Home Savings Account (FHSA), introduced in 2023, combines a deduction on contribution with tax-free withdrawal for a first home. Mandatory contributions to the Canada Pension Plan, which were increased by the CPP enhancement phased in from 2019 to 2025, also add to national saving. Canadian households nonetheless carry high debt: household credit market debt has been roughly 175 % of disposable income in recent years, mostly mortgages, which makes the economy sensitive to interest rate changes.
Economists debate how much such incentives raise total saving rather than shifting existing savings into tax-favoured accounts. The evidence suggests that automatic enrolment and default options have large effects on saving behaviour, while pure tax incentives mostly benefit higher-income households who would have saved anyway. From a macroeconomic perspective, the most reliable way for a government to raise national saving is to reduce its own deficit, because public saving is part of national saving.
Common mistakes
MistakeBuying shares is investment in the GDP sense.
InsteadIt is saving; investment means spending on new capital goods.
MistakeA government deficit has no effect on private investment.
InsteadAt full employment it tends to raise real interest rates and crowd out some investment.
MistakeA 5 % interest rate always means savers gain 5 %.
InsteadThe real return is the nominal rate minus inflation.
MistakeNegative interest rates are impossible.
InsteadReal rates are often negative; even nominal rates were slightly negative in some countries in the 2010s.
MistakeFinancial intermediaries just add costs.
InsteadThey reduce information costs, diversify risk and transform maturities, though this also creates fragility.
Summary and key terms
- In a closed economy, national saving equals investment; national saving is private plus public saving.
- The loanable funds model treats the real interest rate as the price that balances saving and investment.
- Government deficits reduce national saving and tend to raise interest rates and crowd out investment, especially at full employment.
- The Fisher equation links nominal and real interest rates through expected inflation.
- The neutral real interest rate depends on global saving, investment, demographics and productivity, and fell sharply before 2020.
- Banks, bond and stock markets, pension funds and insurers channel saving to productive uses.
- Tax-advantaged accounts and automatic enrolment encourage household saving; reducing deficits raises national saving most directly.
- National saving
- Income not spent on consumption or government purchases; private plus public saving.
- Public saving
- Government tax revenue minus spending; the budget balance.
- Loanable funds
- Saving available to finance investment and other borrowing.
- Real interest rate
- The nominal interest rate adjusted for expected inflation.
- Crowding out
- The reduction in private investment caused by government borrowing.
- Fisher equation
- Real rate ≈ nominal rate minus expected inflation.
- Neutral interest rate
- The rate consistent with output at potential and stable inflation.
- Bond
- A debt security promising interest and repayment of principal.
- Financial intermediary
- An institution that channels funds from savers to borrowers.
- Maturity transformation
- Funding long-term loans with short-term deposits.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Y = 2,000, C = 1,300, G = 400, T = 350. Find private, public and national saving.
Show answer
Private 350, public −50, national 300.
In the same economy (closed), what is investment?
Show answer
300.
What happens in the loanable funds market when firms become more optimistic?
Show answer
Investment demand rises; the real interest rate and saving rise.
Saving S = 200 + 40r, investment I = 600 − 40r. Find r and investment.
Show answer
r = 5 %, I = 400.
A deficit of 80 is added to the previous question. New r?
Show answer
120 + 40r = 600 − 40r gives r = 6 %.
A bond pays 5 % and inflation is 3.5 %. What is the real return?
Show answer
About 1.5 %.
Why might crowding out be small in a recession?
Show answer
Idle resources and low interest rates; higher incomes may raise saving.
Name three functions of financial intermediaries.
Show answer
Reducing information costs, diversification, maturity transformation, liquidity.
Why did the neutral real rate fall before 2020?
Show answer
Ageing, slower productivity growth and strong demand for safe assets.
Portfolio task: find the current yield on your government's 10-year bond and the latest inflation rate; estimate the real yield.
Show answer
Answers vary; should subtract expected or current inflation.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.