
CON-350 · Lesson 9 of 12 · 25 min
Surety bonds
Insurance protects against accidents. A surety bond protects against a different risk: that the contractor will not do what it promised. If a contractor abandons a job, becomes insolvent or fails to pay its subcontractors and suppliers, a surety bond puts a financially strong third party, the surety, behind the contractor's promise. Public owners in both countries require bonds on most construction contracts, and many private owners do too. CON-320 lesson 11 explains how sureties assess a contractor's finances and set bonding capacity. This lesson explains what the bonds are, what they guarantee, how they are priced and how standard forms differ between Canada and the United States. Lesson 10 covers subcontractor default, subcontractor default insurance and how claims on bonds work.
How suretyship differs from insurance
A surety bond involves three parties. The principal is the contractor whose performance is guaranteed. The obligee is the party protected, usually the owner. The surety is the insurer or bonding company that guarantees the principal's obligations up to the penal sum of the bond.
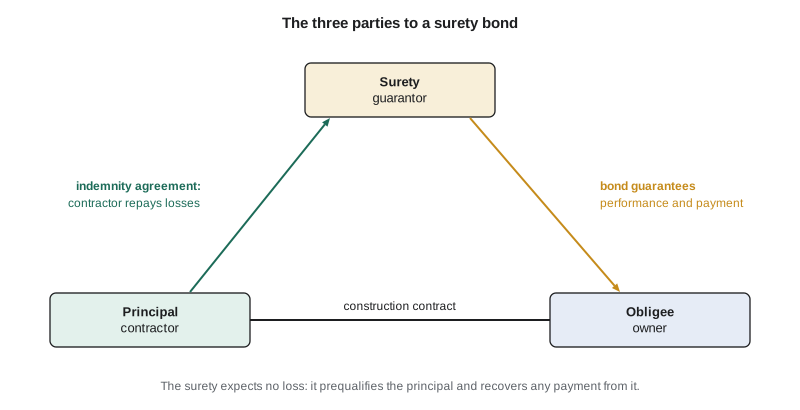
Although sureties are usually insurance companies or their subsidiaries, a bond is not insurance in the ordinary sense. An insurer expects some losses and prices premiums to pay for them across many policyholders. A surety expects no losses: it bonds only contractors it believes can perform, and if it does pay, it expects to recover from the contractor and its owners under a general indemnity agreement, often backed by personal guarantees. The premium is therefore closer to a fee for lending the surety's credit and for its prequalification work than to a payment for expected losses.
| Feature | Insurance | Surety bond |
|---|---|---|
| Parties | Two: insurer and insured | Three: surety, principal and obligee |
| Who is protected | The insured | The obligee (owner) and, for payment bonds, claimants |
| Expected losses | Priced into premiums | Underwritten to expect none |
| Recovery after a loss | Usually none from the insured | Full recovery sought from the principal under the indemnity agreement |
| Premium basis | Expected losses plus expenses | Fee for credit and prequalification |
| Cancellation | Usually possible with notice | Not cancellable once issued for a contract |
Types of bonds
| Bond | What it guarantees | Typical amount |
|---|---|---|
| Bid bond | That the bidder will enter the contract and provide the required bonds if its bid is accepted; otherwise the surety pays the owner's loss up to the penal sum | Canada: commonly 10 % of the bid; US: commonly 5 to 10 %, with 20 % (capped) on federal work |
| Performance bond | That the contractor will perform the contract; if it defaults, the surety remedies the default up to the penal sum | Canada: commonly 50 % of the contract price; US public work: commonly 100 % |
| Labour and material payment bond | That the contractor will pay subcontractors, workers and suppliers for work on the project | Canada: commonly 50 %; US public work: commonly 100 % |
| Maintenance or warranty bond | That the contractor will correct defects during the warranty period | Often a small percentage, such as 10 % |
| Supply bond | That a supplier will deliver specified materials | Value of the supply |
| Lien bond | Replaces the security of a registered lien so that it can be removed from title | Amount of the lien plus an allowance for costs |
The bid bond is often accompanied in Canada by a consent of surety or agreement to bond, in which the surety confirms it will issue the performance and payment bonds if the bidder wins. A contractor that cannot obtain a consent of surety cannot bid on bonded work, which is why bonding capacity limits how much public work a contractor can take on (CON-320 lesson 11).
Canadian practice
In Canada, performance and labour and material payment bonds are commonly set at 50 % of the contract price each, a practice that grew from the public sector and the industry's standard forms. The Canadian Construction Documents Committee publishes CCDC 220 (bid bond), CCDC 221 (performance bond) and CCDC 222 (labour and material payment bond), and most public owners use these or similar forms. The Surety Association of Canada represents the industry. Ontario's Construction Act made bonds mandatory on public contracts. Under section 85.1, a contractor on a public contract with a price of $500,000 or more must provide a performance bond and a labour and material payment bond, each covering at least 50 % of the contract price, in the forms prescribed by regulation; on P3 and alternative financing and procurement projects the required amount is capped at $50 million. The requirement applies to procurements that began on or after 1 July 2018. Other provinces rely mainly on owner policy, and federal departments set contract security requirements in their tender documents, often offering a choice between bonds and a security deposit.
Because the Canadian labour and material payment bond benefits subcontractors and suppliers who are not parties to it, the bond names the owner as obligee in trust for claimants, and claimants must give written notice within strict time limits, typically 120 days after their last work or supply, and sue within a further period, often one year. Lesson 10 covers the claims process.
Standard bond forms
| Purpose | Canada | United States |
|---|---|---|
| Bid bond | CCDC 220 | AIA A310-2010; SF 24 (federal) |
| Performance bond | CCDC 221 | AIA A312-2010 Performance Bond; ConsensusDocs 260; SF 25 (federal) |
| Payment bond | CCDC 222 labour and material payment bond | AIA A312-2010 Payment Bond; ConsensusDocs 261; SF 25-A (federal) |
| Statutory forms | Ontario prescribed forms under the Construction Act for public contracts | State statutory forms on some public work |
The wording of the performance bond matters a great deal when a contractor defaults. Some forms require the owner to declare the contractor in default and terminate the contract before the surety must act, and they give the surety a list of options. Others are more demanding of the surety. Owners who write their own bond forms often impose short response times and waive defences, which can make sureties reluctant to bond the project or raise the price. Lesson 10 discusses the surety's options on default.
Pricing bonds
Bond premiums are usually charged on a sliding scale based on the contract price, with a lower rate for larger amounts. Rates depend on the contractor's financial strength, experience and record, and on the type of work. For strong contractors, performance and payment bonds together often cost somewhere around 0.5 to 1.5 % of the contract price, less on very large contracts; weaker or newer contractors pay more. In Canada, where bonds are 50 % rather than 100 %, the premium is still usually calculated on the contract price, not the penal sum. Bid bonds are often provided at no charge to established clients as part of the bonding relationship.
# Bond premium on a sliding scale (illustrative rates, on the contract price)
def premium(price, scale):
    total, lower = 0.0, 0
    for upper, rate in scale:
        band = min(price, upper) - lower
        if band <= 0:
            break
        total += band * rate
        lower = upper
    return total

scale = [(500_000, 0.0150), (2_500_000, 0.0100), (5_000_000, 0.0075),
         (7_500_000, 0.0070), (float("inf"), 0.0060)]
for price in (1_000_000, 10_000_000, 48_000_000):
    p = premium(price, scale)
print(f"Contract {price:>12,.0f}: premium {p:>9,.0f} ({p / price:.2%})")Contract 1,000,000: premium 12,500 (1.25%) Contract 10,000,000: premium 78,750 (0.79%) Contract 48,000,000: premium 306,750 (0.64%)
The effective rate falls as the contract grows: the illustrative scale gives about 1.25 % on a $1 million contract and about 0.65 % on the $48 million Kingfisher Wharf contract. Contractors include the bond cost in their bid, usually as a general requirement or as part of markup (CON-300). Change orders that increase the contract price also increase the penal sum and the premium, so the cost of bonds should be included in change order pricing.
Worked problem
Bond amounts and premium for Kingfisher Wharf
The City of Larkspur requires a performance bond and a labour and material payment bond, each for 50 % of the $48 million contract price, in CCDC forms. Tallgrass pays an effective premium of 0.65 % of the contract price. What are the penal sums and the premium? What happens if approved changes add $1.6 million?
Show solution
- Performance bond penal sum: 0.50 × 48,000,000 = $24,000,000.
- Labour and material payment bond: $24,000,000.
- Premium: 0.0065 × 48,000,000 = $312,000.
- After changes: price $49.6 million; each bond rises to $24.8 million and the premium by about 0.0065 × 1,600,000 = $10,400.
Answer: The premium of about $312,000 is about two-thirds of 1 % of the price. Bond increases for changes should be priced in each change order.
What bonds do and do not cover
A performance bond guarantees completion of the contract, up to the penal sum, if the contractor defaults. It does not guarantee that the project will be on time if the contractor is merely slow, does not cover the owner's own breaches, and usually does not cover delays or defects that the owner could have avoided by acting promptly. A payment bond protects those who supplied labour and materials to the project, within the claimant definitions of the bond: usually subcontractors and suppliers to the contractor, and often sub-subcontractors, but not remote suppliers further down the chain. Neither bond protects against a contractor's poor workmanship that falls short of default, which is addressed through the contract and warranty.
For owners, bonds have value beyond the money. The surety's prequalification of the contractor screens out firms that are overextended or financially weak, which is one reason public owners require bonds even on contracts where they could recover losses in other ways. For subcontractors and suppliers, especially on public work where liens may be unavailable against public land in some jurisdictions, the payment bond is often the only reliable security for payment.
Alternatives to bonds
Bonds are not the only way to secure a contractor's performance. Owners sometimes accept an irrevocable standby letter of credit from the contractor's bank, a cash security deposit, a parent company guarantee or, on private work, increased holdback or retainage. Each has different strengths. A letter of credit pays on demand without the investigation a surety carries out, which owners like, but it uses the contractor's bank credit line and reduces its working capital, which contractors dislike. A parent company guarantee is only as good as the parent's balance sheet. Holdback or retainage protects the owner and the payment chain but ties up the contractor's cash (CON-310 lesson 11 and CON-320 lesson 10).
| Security | How the owner collects | Effect on the contractor |
|---|---|---|
| Performance and payment bonds | Claim on the surety after default, following the bond conditions | Uses bonding capacity; premium in the price |
| Standby letter of credit | Demand on the bank, often without proving default in detail | Uses bank credit; reduces working capital |
| Cash security deposit | Owner keeps the deposit | Ties up cash for the project term |
| Parent company guarantee | Claim against the parent company | Depends on the parent's strength |
| Increased holdback or retainage | Owner withholds payment | Slows cash flow throughout the job |
Federal contracts in both countries allow some of these alternatives, and private owners choose among them according to the size of the project and the contractor's financial strength. For a contractor, the cost of each option should be compared not only in fees but in the working capital and borrowing capacity it consumes, because the same capacity is needed to pursue the next project.
Common mistakes
MistakeTreating a bond as insurance that the contractor can claim on.
InsteadRemember that the surety will seek full recovery from the contractor under the indemnity agreement.
MistakeAssuming Canadian and American bonds are the same size.
InsteadCanadian bonds are commonly 50 %; US public work commonly requires 100 %.
MistakeWriting owner-drafted bond forms with harsh terms.
InsteadUse standard forms where possible; harsh terms raise prices and reduce surety appetite.
MistakeForgetting to price bond increases in change orders.
InsteadInclude the premium on the change value in each change order.
MistakeMissing payment bond notice deadlines.
InsteadTrack the bond's notice and suit periods from the date of last work or supply.
Summary and key terms
- A surety bond involves a principal (contractor), an obligee (owner) and a surety that guarantees the principal's obligations.
- Sureties underwrite to expect no losses and recover any payments from the contractor under an indemnity agreement.
- Bid, performance, labour and material payment, maintenance, supply and lien bonds serve different purposes.
- Canadian practice commonly uses 50 % performance and payment bonds; Ontario requires them on public contracts of $500,000 or more.
- US federal work under the Miller Act requires 100 % performance and payment bonds above $150,000; states have Little Miller Acts.
- Premiums are charged on a sliding scale of the contract price, usually around 0.5 to 1.5 % for strong contractors.
- Bonds guarantee completion and payment up to the penal sum; they do not cover owner breaches or minor deficiencies.
- Surety bond
- A three-party guarantee by a surety of a principal's obligations to an obligee.
- Principal
- The party whose performance is guaranteed, usually the contractor.
- Obligee
- The party protected by the bond, usually the owner.
- Penal sum
- The maximum amount the surety can be required to pay under a bond.
- Bid bond
- A bond guaranteeing that a successful bidder will sign the contract and provide the required bonds.
- Performance bond
- A bond guaranteeing that the contractor will perform the contract.
- Payment bond
- A bond guaranteeing payment of subcontractors, workers and suppliers.
- General indemnity agreement
- The contractor's promise to repay the surety for any loss on its bonds.
- Consent of surety
- A surety's confirmation that it will issue final bonds if the bidder wins.
- Miller Act
- The US federal law requiring performance and payment bonds on federal construction contracts.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Name the three parties to a surety bond.
Show answer
Principal, obligee and surety.
Why does a surety expect no losses?
Show answer
It bonds only contractors it believes can perform and recovers any losses from them under the indemnity agreement.
What bond percentages are common on Canadian public work?
Show answer
50 % performance and 50 % labour and material payment.
What does a bid bond guarantee?
Show answer
That the bidder will sign the contract and provide the bonds if its bid is accepted.
A contract of $20 million has an effective bond rate of 0.75 %. What is the premium?
Show answer
$150,000.
Why do bond premiums fall as a percentage on larger contracts?
Show answer
They are charged on a sliding scale with lower rates for higher bands.
What is a consent of surety?
Show answer
A surety's confirmation that it will issue final bonds if the bidder wins.
Give one thing a performance bond does not cover.
Show answer
Owner breaches, minor deficiencies, delays the owner could have avoided.
Why are payment bonds especially important on public work?
Show answer
Liens may be unavailable against public land in some jurisdictions.
What happens to the bond penal sum when a change order adds to the price?
Show answer
It increases, and so does the premium.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.