
ACCT-460 · Lesson 6 of 12 · 27 min
Financial statement fraud
Financial statement fraud is the deliberate misstatement or omission of amounts or disclosures in financial statements in order to deceive users. It is the least common category of occupational fraud and by far the most costly per case, because it distorts the decisions of investors, lenders, suppliers and employees on a large scale and is usually committed by people at the top of the organization who can override controls. This lesson explains why and how financial statements are manipulated, the analytical signals that point to manipulation, and what several well-known cases teach. ACCT-331 covered the auditor's responsibilities for fraud risk in an audit; here the perspective is that of the investigator called in when manipulation is suspected.
Why statements are manipulated
The motives are usually about meeting expectations. Public companies face pressure to meet analysts' forecasts and guidance, because missing them can cut the share price sharply. Private companies face pressure from lenders' covenants, which may require minimum earnings or maximum leverage, and from owners who plan to sell or raise capital. Managers face pressure from bonuses and share-based compensation tied to revenue, earnings or share price. Some manipulation aims to understate results instead, to smooth earnings by building reserves in good years, to reduce taxes, or to depress the value of a business before a management buyout or a divorce settlement. Whatever the motive, financial statement fraud almost always involves senior people, because it requires authority over journal entries, estimates and disclosures, and often the cooperation or silence of others.
Common methods
| Method | How it works | Typical signals |
|---|---|---|
| Fictitious revenue | Recording sales that did not occur, often to fake or related customers | Receivables growing faster than sales; customers that cannot be confirmed; reversals after year-end |
| Timing of revenue | Recording real sales too early: channel stuffing, bill-and-hold, side letters with return rights, holding the books open | Spikes at quarter-end; high returns or credits after period-end; unusual terms |
| Round-tripping | Sending money out and back through related parties so it appears as revenue | Circular cash flows; customers that are also vendors or investors |
| Improper capitalization | Recording expenses as assets to defer their effect on earnings | Assets growing without matching operations; falling expense ratios |
| Concealed liabilities | Omitting liabilities, warranties, returns or contingencies | Low reserves relative to history; off-balance-sheet arrangements |
| Improper valuation | Overstating inventory, receivables, goodwill or investments; understating allowances | Falling allowance ratios; inventory growth; delayed impairments |
| Misleading disclosure | Omitting related parties, going concern doubts or material events | Undisclosed relationships found in registries or news |
Revenue is the most frequently manipulated area in enforcement cases in both countries, because it is the largest number in most income statements and because the judgments involved, about when control or risks and rewards pass to the customer, create room for abuse. Timing schemes are especially common: the sale is real, but it is recorded in the wrong period, often by shipping goods early, giving customers terms that make the sale reversible, or recording goods that the customer has not taken. Side letters, which are agreements outside the main contract that change its terms, are a classic device because the accounting department and the auditors never see them.
The revenue allegation at Saltmarsh Industrial Supply Ltd.
The first hotline report said that fourth-quarter shipments to two distributors were made with side letters allowing returns. Corbett Lane Forensic LLP obtains the shipping records, invoices and contracts for the last three weeks of 2025, interviews warehouse staff and, with counsel's authorization, searches the email accounts of the sales team. It finds that between December 15 and December 31, 2025, Saltmarsh Industrial Supply Ltd. shipped 2.4 million dollars of goods to two distributors, Ridgeback Industrial Distributors and Cormorant Supply Partners, about four times the normal volume for those customers. Signed letters from C. Varga, the vice-president of sales, gave each distributor the unconditional right to return any unsold goods within 120 days and deferred payment until the goods were resold. In February and March 2026, the distributors returned 1.9 million dollars of the goods.
Saltmarsh Industrial Supply Ltd. reports under Accounting Standards for Private Enterprises (ASPE). Section 3400 recognizes revenue from the sale of goods when the seller has transferred the significant risks and rewards of ownership, the amount can be measured reliably and collection is reasonably assured. With an unconditional right of return and payment due only on resale, the distributors had not taken on the risks of ownership; the arrangements were in substance consignments, and revenue should not have been recognized at shipment. The letters were not given to the accounting department or to the auditors.
The effect is significant: removing the 2.4 million dollars from fiscal 2025 reduces reported revenue from 91.2 million to 88.8 million and pre-tax income by about 610 thousand, the gross margin on the goods. The investigators also find a motive. Varga's annual bonus plan paid a large award if revenue exceeded 90 million, and the company's bank covenant required a minimum ratio of earnings before interest, taxes, depreciation and amortization to debt service. The analysis does not, by itself, show that Varga intended to deceive; that will depend on the documents, the interviews and, ultimately, the trier of fact. But the side letters, their concealment and the incentive together form the kind of pattern that boards, auditors and regulators treat seriously.
Analytical signals and the Beneish M-score
Long before an investigator sees a side letter, the financial statements themselves may show signs of manipulation. Horizontal analysis (changes over time) and vertical analysis (proportions within a year) show unusual movements. Ratios such as days sales outstanding, gross margin, inventory turnover and the relationship between net income and operating cash flow are sensitive to common schemes. Fictitious or premature revenue tends to raise receivables relative to sales; capitalizing expenses tends to raise assets and lower expense ratios; and most manipulations push accrual-based earnings away from cash flow.
Researchers have combined such signals into scoring models. The best known is the M-score developed by Messod Beneish and published in 1999, which uses eight indexes calculated from two years of financial statements, weighted by coefficients estimated from companies that were later found to have manipulated earnings. A score above about −1.78 (some users apply −2.22 with a five-variable version) suggests a higher likelihood of manipulation. The F-score of Patricia Dechow and colleagues, published in 2011, uses a different set of accrual, performance and market variables. Lesson 10 discusses Benford's law and other tests on transaction data, building on ACCT-341. The program below calculates the M-score for Saltmarsh Industrial Supply Ltd. from its fiscal 2024 and 2025 statements as originally reported.
# Beneish M-score for Saltmarsh Industrial Supply, FY2025 against FY2024 (invented statements, thousands).
# The eight-variable model of Beneish (1999); scores above about -1.78 suggest a higher likelihood of
# earnings manipulation. It is a screening tool: a high score calls for inquiry, not a conclusion.
y0 = dict(rev=84600, cogs=61760, rec=10150, ca=31400, ppe=14200, ta=52800, dep=1420,
          sga=15230, cl=13900, ltd=9600, ni=3180, cfo=3600)
y1 = dict(rev=91200, cogs=67950, rec=15480, ca=37900, ppe=14050, ta=59700, dep=1350,
          sga=15950, cl=16800, ltd=10400, ni=4420, cfo=1050)

def gm(y): return (y["rev"] - y["cogs"]) / y["rev"]
def aq(y): return 1 - (y["ca"] + y["ppe"]) / y["ta"]
def deprate(y): return y["dep"] / (y["dep"] + y["ppe"])
def lev(y): return (y["cl"] + y["ltd"]) / y["ta"]

idx = {
    "DSRI": (y1["rec"] / y1["rev"]) / (y0["rec"] / y0["rev"]),
    "GMI":  gm(y0) / gm(y1),
    "AQI":  aq(y1) / aq(y0),
    "SGI":  y1["rev"] / y0["rev"],
    "DEPI": deprate(y0) / deprate(y1),
    "SGAI": (y1["sga"] / y1["rev"]) / (y0["sga"] / y0["rev"]),
    "LVGI": lev(y1) / lev(y0),
    "TATA": (y1["ni"] - y1["cfo"]) / y1["ta"],
}
coef = {"DSRI": 0.920, "GMI": 0.528, "AQI": 0.404, "SGI": 0.892, "DEPI": 0.115,
        "SGAI": -0.172, "LVGI": -0.327, "TATA": 4.679}
m = -4.84 + sum(coef[k] * v for k, v in idx.items())
for k, v in idx.items():
    print(f"{k:<5}{v:>8.3f}   contribution {coef[k] * v:>7.3f}")
print(f"\nM-score: {m:.2f}   (screening threshold about -1.78)")
print(f"Days sales outstanding: {y0['rec'] / y0['rev'] * 365:.0f} days in FY2024, {y1['rec'] / y1['rev'] * 365:.0f} days in FY2025")
print(f"Net income {y1['ni']:,} vs operating cash flow {y1['cfo']:,}: accruals of {y1['ni'] - y1['cfo']:,}")DSRI 1.415 contribution 1.302 GMI 1.059 contribution 0.559 AQI 0.952 contribution 0.385 SGI 1.078 contribution 0.962 DEPI 1.037 contribution 0.119 SGAI 0.971 contribution -0.167 LVGI 1.024 contribution -0.335 TATA 0.056 contribution 0.264 M-score: -1.75 (screening threshold about -1.78) Days sales outstanding: 44 days in FY2024, 62 days in FY2025 Net income 4,420 vs operating cash flow 1,050: accruals of 3,370
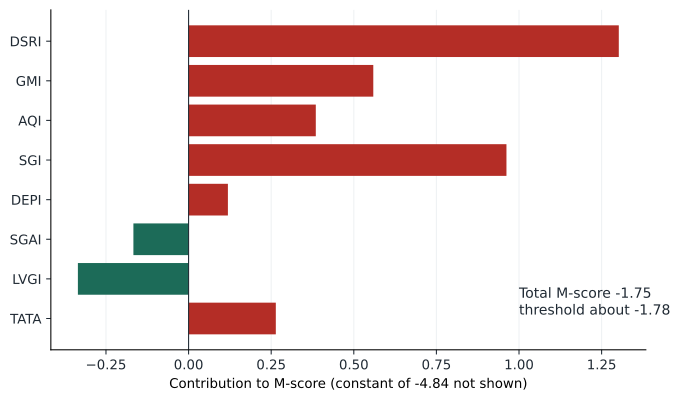
Saltmarsh Industrial Supply Ltd.'s score of −1.75 sits just above the −1.78 threshold. The largest single driver is the days sales in receivables index of 1.415: receivables grew much faster than sales, from 44 days of sales to 62, which is what the 2.4 million dollars of unpaid year-end shipments would produce. The other strong signal is the gap between net income of 4.42 million and operating cash flow of 1.05 million. Neither proves manipulation; receivables can rise because of a new large customer or slower collections, and the M-score is a screening tool with many false positives. But a lender, auditor or board seeing these numbers would have had good reason to ask questions, and the investigator uses them to confirm where to look.
Lessons from well-known cases
Famous cases are useful because they have been documented by courts, regulators and investigators. They should be described carefully, using the findings of those bodies and the dates on which they were made.
| Case | What happened, as found or reported | Lesson |
|---|---|---|
| Enron (United States, 2001) | Used special purpose entities to keep debt off the balance sheet and record gains; filed for bankruptcy in December 2001; several executives were convicted, and its auditor collapsed | Complex structures and related parties can hide liabilities; independence matters |
| WorldCom (United States, 2002) | Capitalized billions of dollars of line costs that should have been expenses; discovered by its internal audit team; the chief executive was convicted | Simple schemes can be huge; internal audit's persistence matters |
| Nortel Networks (Canada, 2004) | Restated results after reserve releases timed to meet targets and trigger bonuses; three former executives were acquitted of fraud by an Ontario court in January 2013 | Aggressive accounting is not always proved to be criminal fraud; standards of proof matter |
| Sino-Forest (Canada, 2011) | A Toronto-listed forestry company whose assets were questioned by a short seller in 2011; the Ontario Securities Commission found in 2017 that former executives had committed fraud | Verifying the existence of assets in distant jurisdictions is critical |
| Wirecard (Germany, 2020) | Disclosed in June 2020 that about 1.9 billion euros of cash it had reported likely did not exist, and filed for insolvency; criminal proceedings followed | Third-party confirmations must be obtained directly and tested |
| FTX (United States, 2022) | A cryptocurrency exchange that collapsed in November 2022; its founder was convicted of fraud and conspiracy in November 2023 and sentenced to 25 years in March 2024 | Commingled customer assets and weak governance enable large losses |
Worked problem
Reading the signals
A distributor's revenue rose 12 per cent, its receivables rose 45 per cent, its allowance for doubtful accounts fell from 3 per cent to 1.5 per cent of receivables, and fourth-quarter sales were 40 per cent of the year. Operating cash flow fell. What do these signals suggest, and what should an investigator examine?
Show solution
- Receivables growing much faster than sales, with a heavy fourth quarter, suggest premature or fictitious revenue.
- A falling allowance on rising receivables suggests understated bad debts, which boosts earnings.
- Falling operating cash flow while earnings rise points to accruals rather than cash.
- Examine large year-end sales and their contracts, shipping documents and any side agreements; credits and returns after year-end; the ageing of receivables; and who approved the allowance change.
Answer: The pattern is consistent with premature revenue and an understated allowance; the investigator tests year-end sales, post-period returns and the allowance judgment.
Common mistakes
MistakeTreating an M-score above the threshold as proof of manipulation.
InsteadUse the score to screen and direct inquiry; investigate the drivers and their explanations.
MistakeLooking only at the general ledger for revenue schemes.
InsteadExamine contracts, side letters, emails, shipping records and post-period returns and credits.
MistakeAssuming financial statement fraud is committed by junior staff.
InsteadExpect senior involvement and management override; plan the investigation independently of management.
MistakeDescribing famous cases from memory or rumour.
InsteadUse the findings of courts and regulators, with dates.
MistakeIgnoring understatement schemes.
InsteadConsider cookie-jar reserves, tax motives and valuation disputes that reward understatement.
MistakeCalling aggressive accounting fraud without evidence of intent.
InsteadDistinguish errors and aggressive judgments from deliberate deception, and leave the legal finding to the forum.
Summary and key terms
- Financial statement fraud is rare but costly and usually involves senior people who can override controls.
- Motives include analyst expectations, covenants, bonuses, sales of the business and, for understatement, taxes or buyouts.
- Revenue is the most common target; timing schemes and side letters are classic devices.
- At Saltmarsh, 2.4 million of year-end shipments with side letters should not have been recognized, reducing pre-tax income by about 610 thousand.
- Ratios such as days sales outstanding and the gap between earnings and operating cash flow are early signals.
- The Beneish M-score screens for manipulation; Saltmarsh's −1.75 was driven by receivables growth.
- Well-known cases should be described from court and regulator findings with dates.
- Financial statement fraud
- Deliberate misstatement or omission in financial statements to deceive users.
- Channel stuffing
- Shipping more goods to distributors than they need, often with incentives, to record revenue early.
- Bill-and-hold
- Recording a sale while the seller keeps the goods; acceptable only under strict conditions.
- Side letter
- An agreement outside the main contract that changes its terms, often hidden from accountants and auditors.
- Round-tripping
- Moving money out and back through related parties so that it appears as revenue.
- Days sales outstanding
- Receivables divided by sales, times 365; a measure of how long customers take to pay.
- Beneish M-score
- A model that combines eight financial statement indexes to screen for earnings manipulation.
- Management override
- Senior management's ability to bypass controls that would otherwise prevent or detect misstatement.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Why is revenue the most common target of financial statement fraud?
Show answer
It is usually the largest number and involves judgments about timing that can be abused.
Explain why the Saltmarsh shipments should not have been recognized as revenue.
Show answer
Unconditional return rights and payment only on resale meant the distributors had not taken on the risks or control of ownership; the arrangements were in substance consignments.
What was the effect on fiscal 2025 revenue and pre-tax income?
Show answer
Revenue falls from 91.2 million to 88.8 million and pre-tax income by about 610 thousand.
Which index contributes most to Saltmarsh's M-score, and why?
Show answer
The days sales in receivables index (1.415), because receivables rose from 44 to 62 days of sales.
Change fiscal 2025 receivables in the program from 15,480 to 10,950 and rerun. What happens to the M-score?
Show answer
It falls to about −2.13, below the threshold, showing how strongly the receivables signal drives the score.
Name three signals that point to premature revenue.
Show answer
Receivables growing faster than sales, quarter-end spikes, high returns or credits after period-end, falling operating cash flow.
Why did the investigators look at Varga's bonus plan?
Show answer
To understand incentives; the plan paid a large award if revenue exceeded 90 million.
What does the Nortel outcome teach forensic accountants?
Show answer
Aggressive or improper accounting is not always proved to be criminal fraud; the forum's standard of proof and intent matter.
Why are side letters effective in concealing revenue schemes?
Show answer
They change the terms outside the main contract, so accountants and auditors who see only the contract miss them.
Give two reasons a company might understate its results.
Show answer
To build reserves that smooth future earnings, reduce taxes, or depress value before a buyout or settlement.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.