
ACCT-431 · Lesson 9 of 12 · 26 min
Review engagements under CSRE 2400
Most private companies do not need an audit. Their owners know the business, their shareholders are few, and the cost of an audit would be hard to justify. But lenders, landlords, franchisors and minority investors often want more than statements the company prepared itself. A review engagement fills the gap. It provides limited assurance, a lower level than an audit's reasonable assurance, at a fraction of the cost, by relying mainly on inquiry and analytical procedures. This lesson follows Hollis Ward's review of Kestrel Landscaping, a private landscaping and snow-removal company whose bank requires reviewed annual financial statements under its loan agreement.
Kestrel Landscaping Ltd. operates 23 crews from a yard outside Calgary, with revenue of 6.24 million dollars for the year ended October 31, 2026. It prepares its financial statements under Accounting Standards for Private Enterprises (ASPE). The owner-manager, Dana Kowalczyk, keeps the books with a part-time bookkeeper.
The standard and the nature of limited assurance
Review engagements on historical financial statements in Canada are performed under Canadian Standard on Review Engagements (CSRE) 2400, Engagements to Review Historical Financial Statements, effective for periods ending on or after December 14, 2017. It replaced the older review standards that relied on a checklist of inquiries with a more judgment-based approach modelled on the IAASB's ISRE 2400. Firms performing reviews must comply with CSQM 1, and practitioners must be independent of the entity.
The level of assurance is the essential difference from an audit. In an audit, the auditor reduces engagement risk to an acceptably low level and expresses a positive opinion: the statements present fairly, in all material respects. In a review, the practitioner reduces engagement risk to a level that is acceptable in the circumstances but higher than in an audit, and expresses a negative conclusion: nothing has come to the practitioner's attention that causes the practitioner to believe the statements are not presented fairly. The procedures are not designed to obtain evidence about the operating effectiveness of controls, to inspect assets, to confirm balances with third parties or to identify fraud.
| Audit | Review | |
|---|---|---|
| Assurance | Reasonable (high but not absolute) | Limited (meaningful but lower) |
| Form of conclusion | Positive opinion | Negative conclusion |
| Main procedures | Risk assessment, tests of controls, substantive tests including external confirmation, inspection, observation | Inquiry and analytical procedures, plus additional procedures when needed |
| Understanding of internal control | Required to assess risks; controls tested when relied on | General understanding of the entity and its accounting systems only |
| Independence | Required | Required |
| Typical cost for Kestrel | About 38,000 dollars | About 14,000 dollars |
Acceptance and preconditions
Before accepting the engagement, the practitioner confirms that the preconditions for a review are present: the financial reporting framework is acceptable; management acknowledges its responsibility for the statements, for internal control necessary to prepare them, and for providing all relevant information and access; and the practitioner has no reason to believe that relevant ethical requirements, including independence, will not be met. The practitioner should also consider whether a review meets the user's needs. If Kestrel's bank had required an audit under the loan agreement, a review would not satisfy it, however much cheaper. Terms are agreed in an engagement letter that states the objective, the limited assurance nature of the review and the expected form of report.
Hollis Ward's independence for Kestrel must be checked as carefully as for an audit client. The firm prepares Kestrel's corporate tax return and gives occasional bookkeeping advice; both are permissible non-assurance services if the firm does not assume management responsibilities, such as approving entries or making decisions for the owner, and safeguards are applied.
Understanding the entity and planning procedures
The practitioner obtains an understanding of the entity and its environment, and of the applicable financial reporting framework, sufficient to identify areas in the financial statements where material misstatements are likely to arise, and to design procedures to address those areas. Materiality is determined as in an audit, though it does not drive sampling. For Kestrel, Hollis Ward sets materiality at 5 per cent of a normalized pre-tax income of about 520,000 dollars, or 26,000 dollars, considering that the bank focuses on profitability and debt service.
Areas where misstatements are likely at Kestrel include: revenue recognition on multi-season maintenance contracts paid in advance; completeness of payroll accruals and source deductions at year end; the classification and amortization of trucks and equipment; the snow-removal contracts, where revenue depends on the number of events in a season; the bank loan and its covenants; and related party transactions with the owner. The practitioner designs inquiries and analytical procedures focused on those areas, rather than running through a standard questionnaire.
Inquiry
Inquiry of management and others in the entity is the backbone of a review. Good inquiry is specific, follows up inconsistent or vague answers, and is directed at people with knowledge. For Kestrel, the practitioner asks the owner how contract revenue is recognized when customers prepay for a full season, how the bookkeeper calculates accrued wages at month end, whether any equipment was sold, traded or written off, whether any customer disputes or lawsuits exist, whether the company has complied with its loan covenants, and whether any transactions with the owner or her family occurred. Answers that conflict with other information, such as the owner saying no equipment was sold while the general ledger shows a gain on disposal, require follow-up.
Analytical procedures
Analytical procedures in a review are designed to identify relationships and individual items that appear unusual and might indicate material misstatement. Effective analytics depend on expectations that are precise and based on independent information, not simply comparisons with last year. The program builds expectations for four of Kestrel's accounts: revenue from crew numbers, price increases and fewer billable days; wages from crews, crew size, average wage and hours; fuel from crews and the change in fuel prices; and interest from average debt and the loan rate. It flags differences above the greater of 40,000 dollars or 3 per cent of the expectation, thresholds chosen in relation to materiality.
# Review engagement analytics for a small private client (invented, dollars).
# Expectations are built from independent data, then compared with recorded amounts.
prior = {"Revenue": 5_780_000, "Wages": 2_310_000, "Fuel": 412_000, "Interest": 96_000, "Gross margin %": 0.318}
current = {"Revenue": 6_240_000, "Wages": 2_655_000, "Fuel": 398_000, "Interest": 131_000, "Gross margin %": 0.351}

crews, prior_crews = 23, 21
contracts_price_rise = 0.035
avg_hourly, hours_per_crew_member = 27.40, 1_820 * 1.0
crew_size = 2.0
fuel_price_change = -0.06
avg_debt, rate = 1_780_000, 0.068

expect = {
    "Revenue": prior["Revenue"] * (crews / prior_crews) * (1 + contracts_price_rise) * 0.97,  # 3% fewer billable days
    "Wages": crews * crew_size * avg_hourly * hours_per_crew_member,
    "Fuel": prior["Fuel"] * (crews / prior_crews) * (1 + fuel_price_change),
    "Interest": avg_debt * rate,
}
threshold_pct, threshold_abs = 0.03, 40_000     # practitioner's thresholds for follow-up
print(f"{'Item':<10}{'Expected':>12}{'Recorded':>12}{'Difference':>12}  Follow up?")
for k, e in expect.items():
    d = current[k] - e
    follow = abs(d) > max(threshold_abs, threshold_pct * e)
    print(f"{k:<10}{e:>12,.0f}{current[k]:>12,.0f}{d:>12,.0f}  {'yes - inquire' if follow else 'no'}")
gm_change = current["Gross margin %"] - prior["Gross margin %"]
print(f"Gross margin moved {gm_change*100:+.1f} points: {'inquire' if abs(gm_change) > 0.02 else 'consistent'}")Item Expected Recorded Difference Follow up? Revenue 6,355,482 6,240,000 -115,482 no Wages 2,293,928 2,655,000 361,072 yes - inquire Fuel 424,164 398,000 -26,164 no Interest 121,040 131,000 9,960 no Gross margin moved +3.3 points: inquire
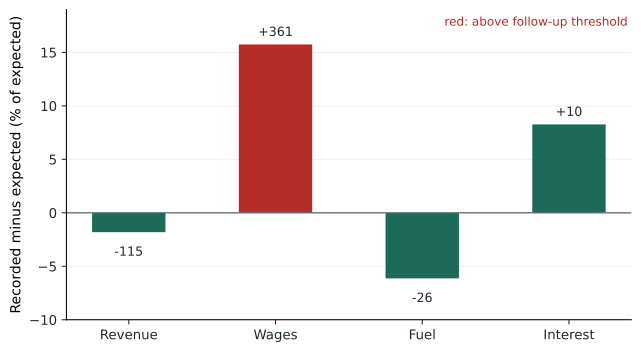
Revenue, fuel and interest are close enough to expectations that no further inquiry is needed. Wages are 361,000 dollars above expectation, and the gross margin rose 3.3 percentage points even though wages, a major cost of sales, rose. The two signals conflict: if wages really rose that much, margin should have fallen. The practitioner asks the owner, who explains that Kestrel began paying its yard staff and mechanics through the same payroll and that their wages, previously treated as overhead, were partly reclassified to cost of sales; the bookkeeper also recorded a year-end bonus twice. The reclassification is consistent with the framework if applied consistently and disclosed; the duplicate bonus is a misstatement of about 96,000 dollars, which the owner corrects. The higher margin, it turns out, reflects price increases on maintenance contracts and a strong snow season, consistent with the practitioner's revenue expectation once the change in mix is considered.
Additional procedures
If the practitioner becomes aware of a matter that causes it to believe the statements may be materially misstated, CSRE 2400 requires additional procedures sufficient to conclude whether the matter is likely to cause the statements to be materially misstated, or that it is not. Additional procedures can include further inquiry, analytics at a more detailed level, or procedures more like those of an audit, such as inspecting documents. For the duplicate bonus, the practitioner inspects the payroll register and the journal entries to confirm the error and the correction. The practitioner must also read the statements, consider going concern and subsequent events, and reconcile the statements to the underlying accounting records.
Some matters are common in small entity reviews. Going concern needs attention where an owner-managed business has thin equity or depends on one customer or the owner's personal guarantees. Related party transactions with the owner, such as a truck used personally or rent paid to the owner's holding company, need to be identified and disclosed. And because the practitioner often helps with the year-end adjustments, the line between assisting management and taking over management's responsibilities must be watched.
Written representations and the report
The practitioner obtains written representations from management covering its responsibilities, the completeness of information provided, and specific matters such as related parties, subsequent events, litigation and uncorrected misstatements. The review report then states the conclusion.
A CSRE 2400 report is titled Independent Practitioner's Review Engagement Report and is addressed to the appropriate party, here the shareholder and board of Kestrel. It includes: a description of the statements reviewed; management's responsibility; the practitioner's responsibility, including that a review is a limited assurance engagement and that the procedures performed are primarily inquiries and analytical procedures; and the conclusion: Based on our review, nothing has come to our attention that causes us to believe that the financial statements do not present fairly, in all material respects, the financial position of Kestrel Landscaping Ltd. as at October 31, 2026, and the results of its operations and its cash flows for the year then ended in accordance with Canadian accounting standards for private enterprises.
If the statements are materially misstated, the practitioner issues a qualified conclusion, where the effects are material but not pervasive, or an adverse conclusion, where they are pervasive. If the practitioner cannot obtain sufficient evidence, for example because management refuses to answer inquiries about a material area, the result is a qualified conclusion or, where pervasive, a denial of conclusion, or the practitioner may withdraw. An emphasis of matter paragraph can draw attention to a matter such as a going concern uncertainty.
Worked problem
Building a precise expectation
Kestrel's fuel expense was 412,000 last year with 21 crews. This year there are 23 crews and fuel prices fell 6 per cent. What expectation does the program build, and why is it better than last year's figure?
Show solution
- Scale last year's fuel by the change in crews: 412,000 × 23 ÷ 21.
- Adjust for the price change: multiply by 0.94.
- The expectation is about 424,000; recorded fuel of 398,000 is within the threshold.
- Using last year's 412,000 as the expectation would ignore known changes in activity and prices and could mask an error.
Answer: About 424,000 dollars; an expectation built from independent drivers is more precise than a prior-year comparison.
Common mistakes
MistakeTreating a review as a small audit.
InsteadA review relies mainly on inquiry and analytics and gives limited assurance; it does not test controls or confirm balances routinely.
MistakeRunning through a standard questionnaire without considering where misstatements are likely.
InsteadDesign inquiries and analytics around the areas where material misstatements are likely.
MistakeComparing current figures only with the prior year.
InsteadBuild expectations from independent drivers such as volumes, rates and prices.
MistakeAccepting vague answers to inquiries.
InsteadFollow up inconsistent or incomplete responses and corroborate where necessary.
MistakeStopping when analytics show an unusual result.
InsteadPerform additional procedures until the matter is resolved or its effect on the conclusion is determined.
MistakeAccepting a review when the user's agreement requires an audit.
InsteadConfirm that a review meets the needs of the intended users before accepting.
Summary and key terms
- CSRE 2400 governs reviews in Canada; practitioners must be independent and firms must comply with CSQM 1.
- A review provides limited assurance and a negative-form conclusion.
- Preconditions include an acceptable framework, management's acknowledgment of responsibilities and independence.
- Procedures focus on areas where material misstatements are likely to arise.
- Inquiry and analytical procedures based on precise, independent expectations are the main procedures.
- Kestrel's wages exceeded expectation by 361,000, revealing a reclassification and a duplicate bonus.
- Additional procedures are required when the practitioner becomes aware of possible material misstatement.
- Modified conclusions can be qualified, adverse or a denial.
- Review engagement
- An engagement to obtain limited assurance on financial statements, mainly through inquiry and analytical procedures.
- Limited assurance
- A meaningful level of assurance, lower than in an audit, expressed in negative form.
- Negative assurance
- A conclusion stating that nothing has come to the practitioner's attention indicating misstatement.
- Expectation
- An independent estimate of an amount used in analytical procedures.
- Threshold
- The difference from expectation above which follow-up is required.
- Additional procedures
- Further work performed when the practitioner becomes aware of a possible material misstatement.
- Denial of conclusion
- A statement that the practitioner does not express a conclusion because of a pervasive inability to obtain evidence.
Practice problems
Work each problem on paper first, then reveal the answer to check.
What form of conclusion does a review report contain?
Show answer
A negative-form conclusion: nothing has come to the practitioner's attention indicating that the statements are not fairly presented.
Is independence required for a review?
Show answer
Yes, in both Canada and the US.
Which Kestrel account exceeded its threshold?
Show answer
Wages, by about 361,000 dollars.
Change the threshold percentage to 0.015 in the program. What else is flagged?
Show answer
Revenue: a difference of about 115,000 exceeds 1.5 per cent of the expectation (about 95,000).
Why was the margin increase suspicious alongside the wage increase?
Show answer
Higher wages, a cost of sales, should reduce margin; the two signals conflicted.
Name two procedures a review typically does not include.
Show answer
Tests of operating effectiveness of controls; external confirmations; inventory observation.
What preconditions must exist before accepting a review?
Show answer
An acceptable framework, management's acknowledgment of responsibilities, and no reason to doubt ethics and independence.
What is Kestrel's review materiality?
Show answer
About 26,000 dollars, 5 per cent of normalized pre-tax income.
When does a review produce a denial of conclusion?
Show answer
When a pervasive inability to obtain evidence prevents a conclusion.
Why might related party transactions need special attention in Kestrel's review?
Show answer
The owner-manager may have personal or family transactions with the company that require identification and disclosure.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.