
ACCT-431 · Lesson 11 of 12 · 25 min
Special reports, other assurance and sustainability assurance
Public accountants report on much more than complete, general purpose financial statements. Landlords want an auditor's report on a single statement of sales to calculate percentage rent. Lenders want assurance that covenants were met. Franchisors want royalty statements audited. Governments and investors increasingly want assurance on greenhouse gas emissions and other sustainability information. This lesson surveys these engagements: audits of special purpose financial statements and single statements, summary financial statements, other assurance engagements on subject matter other than historical financial information, agreed-upon procedures, and assurance on emissions and sustainability reports.
Special purpose frameworks
A special purpose framework is designed to meet the financial information needs of specific users: for example, a cash basis, a tax basis, the provisions of a contract, or a regulator's reporting requirements. CAS 800 deals with audits of financial statements prepared under such frameworks. The auditor must determine whether the framework is acceptable, understand the purpose of the statements and the intended users, and evaluate whether the statements adequately describe the framework. The auditor's report includes an emphasis of matter paragraph, or in US practice an alert, that draws attention to the basis of accounting and states that the statements may not be suitable for another purpose, and may restrict distribution or use to the specified users.
Tamarack's Mexican subsidiary leases its plant under a contract that requires annual financial statements prepared on a contractual basis that excludes certain non-cash items, audited for the landlord. The group team arranges for the component auditor to perform that engagement as well; the report will describe the contractual basis, state that the statements were prepared to help the subsidiary comply with the lease, and warn that they may not be suitable for another purpose.
Single statements, specific elements and summary statements
CAS 805 applies to audits of a single financial statement, such as a balance sheet or a statement of revenue, or of a specific element, account or item, such as a schedule of royalties or a statement of sales for percentage rent. Materiality is set in relation to the single statement or element, which usually makes it much lower than for the complete statements; the auditor must also consider interrelated items, because sales cannot be audited without considering receivables, returns and cut-off. Kestrel Landscaping's largest snow-removal contract, with a property management company, requires an audited statement of contract revenue and direct costs each year; Hollis Ward audits it under CAS 805 with materiality based on the statement's revenue of 840,000 dollars rather than Kestrel's overall figures.
CAS 810 covers engagements to report on summary financial statements derived from audited statements, such as condensed statements in an annual review mailed to members or included in a fundraising brochure. The auditor's opinion states whether the summary statements are consistent, in all material respects, with the audited statements, in accordance with the criteria applied; it is not a new opinion on fair presentation. Summary statements must be clearly identified, refer to the audited statements and say where they can be obtained.
Other assurance engagements
Assurance can be provided on subject matter other than historical financial statements: compliance with a contract or a law, the effectiveness of internal control, the operation of a system, key performance indicators, forecasts, emissions. In Canada, CSAE 3000, Attestation Engagements Other than Audits or Reviews of Historical Financial Information, covers engagements in which the practitioner reports on information prepared by management, such as a statement of compliance with loan covenants. CSAE 3001, Direct Engagements, covers engagements in which the practitioner measures or evaluates the subject matter directly and presents the results, such as some performance audits by legislative auditors. Specific standards build on CSAE 3000: CSAE 3410 for greenhouse gas statements, CSAE 3416 for service organization controls, and CSAE 3530 and 3531 for compliance. Engagements may provide reasonable or limited assurance.
Every assurance engagement involves the same elements: a three-party relationship (practitioner, responsible party and intended users); an appropriate subject matter; suitable criteria that are relevant, complete, reliable, neutral and understandable; sufficient appropriate evidence; and a written report. The criteria are often the hardest element. A practitioner cannot give assurance that a company's operations are sustainable without criteria that say what sustainable means; a statement of greenhouse gas emissions prepared under the Greenhouse Gas Protocol provides such criteria.
Agreed-upon procedures
In an agreed-upon procedures engagement, the practitioner performs specific procedures agreed with the engaging party and reports the factual findings, without expressing an opinion or conclusion. CSRS 4400, Agreed-Upon Procedures Engagements, effective for engagements with terms agreed on or after January 1, 2022, is based on the IAASB's revised ISRS 4400. Independence is not required, but the report must state whether the practitioner is independent. The procedures and findings must be described objectively, avoiding vague terms such as reviewed or examined; for example, Compared the total of the aged payables listing with the general ledger balance at December 31, 2026 and found them in agreement.
Agreed-upon procedures are useful when users want specific facts checked rather than a conclusion, such as a franchisor verifying that sales were reported using the agreed calculation, or a granting agency checking that grant funds were spent on eligible costs. They become problematic when users read the findings as assurance they were never intended to provide, which is why reports describe the procedures and findings precisely and do not summarize them into comfort.
Greenhouse gas emissions
Greenhouse gas statements report emissions in tonnes of carbon dioxide equivalent, usually split into scope 1 (direct emissions from owned or controlled sources, such as natural gas burned in boilers and diesel in trucks), scope 2 (indirect emissions from purchased electricity, heat and steam) and scope 3 (other indirect emissions in the value chain). Assurance on GHG statements raises distinctive risks: activity data such as fuel invoices and meter readings may be incomplete; emission factors may be out of date or wrong for the location; organizational boundaries may be inconsistent with the financial statements; and estimates are common.
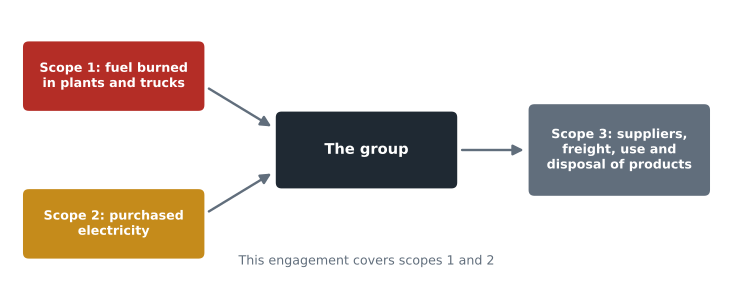
Tamarack's board has decided to obtain limited assurance on its 2026 scope 1 and 2 emissions as a step toward future requirements. Hollis Ward's sustainability team performs the engagement under CSAE 3410. The program recalculates emissions from activity data for each site and compares the totals with the amounts in management's statement, using a threshold of 5 per cent of the recalculated amount for follow-up. The emission factors are illustrative round numbers, not published factors.
# Recalculating the group's 2026 scope 1 and 2 emissions for a limited assurance engagement.
# Emission factors are ILLUSTRATIVE round numbers, not official published factors.
gas_factor = 0.0503          # t CO2e per gigajoule of natural gas (illustrative)
diesel_factor = 0.00268      # t CO2e per L of diesel (illustrative)
grid = {"Alberta": 0.00049, "Ontario": 0.00003, "Nuevo Leon": 0.00042}  # t CO2e per kWh (illustrative)

sites = [  # site, gas GJ, diesel L, kWh, grid region
    ("Calgary plant", 182_000, 96_000, 41_500_000, "Alberta"),
    ("Lethbridge hub", 22_400, 1_410_000, 6_800_000, "Alberta"),
    ("Mississauga snacks", 14_100, 8_200, 3_900_000, "Ontario"),
    ("Monterrey plant", 61_000, 52_000, 17_200_000, "Nuevo Leon"),
]
reported = {"scope1": 17_190, "scope2": 30_610}
s1 = sum(g * gas_factor + d * diesel_factor for _, g, d, _, _ in sites)
s2 = sum(k * grid[r] for *_, k, r in sites)
for label, calc, rep in (("Scope 1", s1, reported["scope1"]), ("Scope 2 (location-based)", s2, reported["scope2"])):
    diff = rep - calc
    flag = "investigate" if abs(diff) > 0.05 * calc else "within 5% threshold"
print(f"{label:<26} recalculated {calc:>8,.0f} t reported {rep:>8,.0f} t difference {diff:>+7,.0f} {flag}")Scope 1 recalculated 18,256 t reported 17,190 t difference -1,066 investigate Scope 2 (location-based) recalculated 31,008 t reported 30,610 t difference -398 within 5% threshold
Scope 2 is within the threshold. Scope 1 is about 1,070 tonnes, or 6 per cent, below the recalculated amount. Follow-up reveals that management's statement omitted diesel used by the distribution hub's leased truck fleet, on the view that leased vehicles were outside its boundary. Under the operational control approach that Tamarack chose, those trucks are within the boundary, because Tamarack directs their use. Management corrects the statement. The team also checks that the emission factors used are appropriate for each site and year, that the boundary matches the entities in the financial statements, and that the Mexican plant's data were included, which required coordination with the component auditor's knowledge of the plant.
Sustainability assurance and the new standard
Assurance on broader sustainability information, such as climate-related disclosures under ISSB-based standards, is developing quickly. The IAASB issued International Standard on Sustainability Assurance (ISSA) 5000, General Requirements for Sustainability Assurance Engagements, in November 2024, effective for periods beginning on or after December 15, 2026. It is designed to be framework-neutral and profession-agnostic, so that both accountants and other assurance providers can use it, and covers both limited and reasonable assurance.
In Canada, the AASB adopted ISSA 5000 as Canadian Standard on Sustainability Assurance (CSSA) 5000 on March 9, 2026, effective for assurance engagements on sustainability information for periods beginning on or after December 15, 2027, a year later than the international standard, with early application permitted. Reporting requirements remain mostly voluntary for now: as of October 2026, the Canadian Sustainability Standards Board's CSDS 1 and CSDS 2, issued in December 2024, are voluntary unless a regulator mandates them; the Canadian Securities Administrators paused their climate disclosure rule in April 2025; and federally regulated financial institutions report under OSFI Guideline B-15. Demand for assurance therefore comes mainly from investors, lenders and companies preparing for future mandates.
Sustainability assurance differs from financial statement assurance in ways that matter. Reporting frameworks are newer and less settled. Information is often non-financial and forward-looking. Data come from many systems outside finance, with weaker controls. And the double materiality concept used in some frameworks asks about the entity's impact on the environment and society as well as financial effects on the entity. Practitioners need specialist knowledge, and firms need quality management responses to these risks, which brings the course back to lesson 1.
Worked problem
Choosing the engagement for a landlord
A landlord wants assurance that Kestrel's reported revenue from its leased yard, used to calculate a percentage rent, is not materially misstated. Which engagement fits?
Show solution
- The landlord wants assurance on one element, revenue under the lease definition, not the complete statements.
- An audit of a specific element under CAS 805 provides reasonable assurance on that element.
- Materiality is set in relation to the revenue element, and interrelated items such as receivables and cut-off are considered.
- An agreed-upon procedures engagement would be an alternative if the landlord preferred specific checks with findings rather than an opinion.
Answer: An audit of the revenue element, or agreed-upon procedures if the landlord wants factual findings only.
Common mistakes
MistakeUsing the materiality for the complete statements in a single-element audit.
InsteadSet materiality in relation to the single statement or element.
MistakeReporting AUP findings in vague terms such as reviewed and found satisfactory.
InsteadDescribe the procedures and factual findings objectively and precisely.
MistakeAccepting an assurance engagement without suitable criteria.
InsteadConfirm that criteria are relevant, complete, reliable, neutral and understandable before accepting.
MistakeAssuming a GHG boundary matches what management included.
InsteadTest the boundary against the chosen consolidation approach, such as operational control.
MistakeTreating a summary financial statement report as a new opinion on fair presentation.
InsteadThe opinion addresses consistency with the audited statements.
MistakeApplying ISSA 5000 dates to Canadian engagements without checking.
InsteadCSSA 5000 applies from periods beginning on or after December 15, 2027 in Canada.
Summary and key terms
- CAS 800 covers audits of special purpose statements, with reports that draw attention to the basis and may restrict use.
- CAS 805 audits single statements or elements with materiality set for that element.
- CAS 810 opinions on summary statements address consistency with the audited statements.
- Other assurance engagements use CSAE 3000 and CSAE 3001 and require suitable criteria.
- Agreed-upon procedures under CSRS 4400 report factual findings, not assurance.
- Tamarack's scope 1 emissions were understated by about 1,070 tonnes because leased trucks were omitted.
- ISSA 5000 was issued in November 2024, effective for periods beginning on or after December 15, 2026.
- CSSA 5000 was adopted in March 2026, effective for periods beginning on or after December 15, 2027.
- Special purpose framework
- A financial reporting framework designed to meet the needs of specific users.
- Single financial statement
- One statement, such as a balance sheet, audited on its own.
- Summary financial statements
- Historical financial information derived from audited statements with less detail.
- Suitable criteria
- Benchmarks used to measure or evaluate the subject matter that are relevant, complete, reliable, neutral and understandable.
- Agreed-upon procedures engagement
- An engagement to perform specified procedures and report factual findings without assurance.
- Scope 1 emissions
- Direct emissions from sources owned or controlled by the entity.
- Scope 2 emissions
- Indirect emissions from purchased electricity, heat or steam.
- Operational control approach
- A GHG boundary approach that includes sources the entity directs.
Practice problems
Work each problem on paper first, then reveal the answer to check.
What does an auditor's report on special purpose statements usually include?
Show answer
A paragraph drawing attention to the basis of accounting and stating that the statements may not be suitable for other purposes, possibly with a restriction on use.
Why is materiality lower in a single-element audit?
Show answer
It is set in relation to the element, which is much smaller than the complete statements.
What does an opinion on summary statements address?
Show answer
Whether they are consistent, in all material respects, with the audited statements.
Name the five elements of an assurance engagement.
Show answer
A three-party relationship, subject matter, suitable criteria, sufficient appropriate evidence and a written report.
Which scope was outside the threshold in the program, and why?
Show answer
Scope 1, because diesel for leased trucks at the distribution hub was omitted.
Raise the threshold in the program to 7 per cent. What changes?
Show answer
Scope 1 falls within the threshold, though the omission should still be corrected once known.
When does CSSA 5000 take effect?
Show answer
For periods beginning on or after December 15, 2027, with early application permitted.
Is independence required in an agreed-upon procedures engagement?
Show answer
Not under CSRS 4400, but the report must state whether the practitioner is independent.
Give two risks distinctive to GHG assurance.
Show answer
Incomplete activity data; inappropriate emission factors; inconsistent boundaries; reliance on estimates.
What is double materiality?
Show answer
Considering both the entity's impacts on the environment and society and the financial effects of sustainability matters on the entity.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.