
ACCT-431 · Lesson 12 of 12 · 27 min
Independence, audit quality and capstone: planning the group engagement
The course closes where it began, with the firm and the profession, and then brings the threads together in a planning memorandum for the 2027 Tamarack group audit. Independence runs through every engagement covered in the course: audits and reviews require it, compilations and some agreed-upon procedures disclose its absence, and component auditors must meet the group's requirements. Audit quality is now measured, inspected and publicly reported in ways that affect firms' reputations and clients' choices. A practitioner moving into a senior role needs to handle both.
The independence framework
Canadian independence rules are set by the provincial CPA bodies in their codes of professional conduct, harmonized through the CPA Canada Public Trust Committee, and for listed entities closely aligned with the IESBA International Code of Ethics. The rules use a conceptual framework: identify threats to independence (self-interest, self-review, advocacy, familiarity and intimidation), evaluate them, and address them by eliminating the circumstances, applying safeguards or declining the engagement. Specific prohibitions apply to listed entities and other public interest entities, including bans on certain non-assurance services such as designing financial information systems and many valuation services, limits on fee dependency, and partner rotation. CPAB and securities regulators also expect audit committees to pre-approve non-audit services.
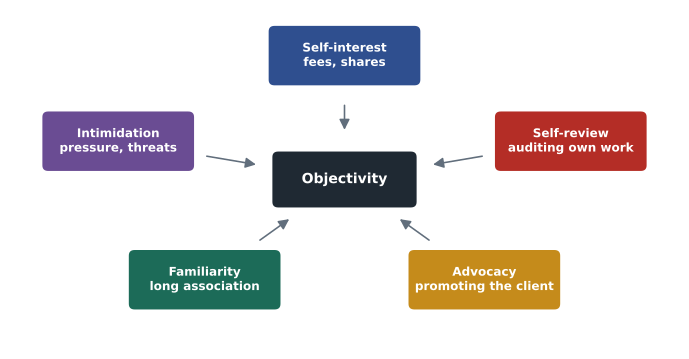
Threats arise in everyday situations. A self-interest threat exists when fees from one client are a large share of the firm's revenue, or when a team member owns shares in the client. A self-review threat exists when the firm audits systems or valuations it designed or prepared. An advocacy threat exists when the firm promotes the client's position, for example in litigation or a share offering. Familiarity threats come from long association with a client's senior management. Intimidation threats come from pressure, such as a client threatening to change auditors over a disagreement about an estimate.
Screening the Tamarack engagement
Each year Hollis Ward screens its independence for Tamarack before accepting the engagement and again before signing the report. The program reviews the fees billed to the group, flags services prohibited for a listed audit client, and checks the rotation status of the engagement partner and quality reviewer.
# Independence screening for the Tamarack engagement team and the firm (invented facts).
firm_revenue = 48_600            # thousands, firm-wide fees for the year
fees = {"Audit of group statements": 1_240, "Review of interim statements": 180,
        "Tax compliance (Mexico)": 95, "Design of new ERP access module": 310, "GHG limited assurance": 140}
assurance = {"Audit of group statements", "Review of interim statements", "GHG limited assurance"}
prohibited_for_listed = {"Design of new ERP access module"}   # designing systems that produce financial information
total = sum(fees.values())
print(f"Fees from the client group: {total:,} = {total/firm_revenue:.1%} of firm revenue")
for svc, f in fees.items():
    if svc in prohibited_for_listed: status = "PROHIBITED for a listed audit client"
    elif svc in assurance: status = "audit or assurance service"
    else: status = "non-audit: permitted with pre-approval and safeguards"
    print(f"  {svc:<36}{f:>6,}  {status}")
non_audit = sum(f for s, f in fees.items() if s not in assurance)
print(f"Non-audit fees as a share of audit fees: {non_audit / fees['Audit of group statements']:.0%}")

team = [("Priya Natarajan", "engagement partner", 6), ("Owen Fraser", "quality reviewer", 3),
        ("Lina Haddad", "senior manager", 9)]
rotation_limit = {"engagement partner": 7, "quality reviewer": 7}
for name, role, years in team:
    lim = rotation_limit.get(role)
    if lim:
        left = lim - years
print(f"{name} ({role}): {years} years served, {'must rotate after this year' if left <= 1 else f'{left} years remaining'}")Fees from the client group: 1,965 = 4.0% of firm revenue Audit of group statements 1,240 audit or assurance service Review of interim statements 180 audit or assurance service Tax compliance (Mexico) 95 non-audit: permitted with pre-approval and safeguards Design of new ERP access module 310 PROHIBITED for a listed audit client GHG limited assurance 140 audit or assurance service Non-audit fees as a share of audit fees: 33% Priya Natarajan (engagement partner): 6 years served, must rotate after this year Owen Fraser (quality reviewer): 3 years served, 4 years remaining
Fees from Tamarack are about 4 per cent of the firm's revenue, well below the levels at which fee dependency rules for public interest entities require action, which under the IESBA Code begin when fees exceed 15 per cent of total fees for two consecutive years. The design of a new ERP access module, proposed by the firm's consulting group, is a prohibited service for a listed audit client because it involves designing systems that generate information for the financial statements on which the firm will report; the firm declines that work. The engagement partner has served six years against a seven-year limit for key audit partners on listed entities, so a successor is assigned to shadow the 2027 engagement and take over in 2028, after which the current partner must observe a cooling-off period, five years for an engagement partner under the IESBA provisions adopted in the provincial codes. The rotation limits in the program reflect the IESBA approach; practitioners should confirm the current provincial rule.
Fees for the GHG limited assurance engagement are assurance fees, but they are not audit fees, and the GHG work must not involve the firm in preparing the emissions statement it assures, which would create a self-review threat. All non-audit services, including the Mexican tax compliance work by the firm's network, are pre-approved by the audit committee and disclosed as required.
Audit quality: inspection, indicators and transparency
Regulators inspect audit firms because audit quality cannot be observed directly by investors. Lesson 1 described the inspection programs of CPAB and the PCAOB and the quality management systems that firms must maintain. Beyond inspections, the profession has experimented with audit quality indicators: measures such as partner and manager hours per engagement, staff turnover, training hours, the proportion of work done by experienced staff, the timing of work and the results of internal and external inspections. Some firms publish transparency reports with these measures, and audit committees increasingly request them when evaluating their auditors.
CPAB began publishing firm-specific inspection results in 2026, and it encourages audit committees to ask their auditors about inspection findings on their own engagements. CPAB's protocol for audit firm communication of inspection findings to audit committees means that Tamarack's audit committee would learn of significant findings on the Tamarack file. Provincial practice inspection results remain confidential.
Audit committees play a central role in quality. They recommend the appointment of the auditor, approve the audit plan and fees, pre-approve non-audit services, review significant findings and evaluate the auditor's performance. A well-informed audit committee asks about the scope of group work, the involvement of component auditors, the use of specialists and technology, the significant risks and how the auditor responded, and the results of quality reviews. The communications described throughout this course, from scoping summaries to deficiency letters, give it the information to do so.
Professional judgment and scepticism
Every lesson in this course has depended on professional judgment exercised with professional scepticism: the group team's decision about where to do work, the evaluation of a component auditor's competence, the severity of a control deficiency, the range for an estimate, the plausibility of a downside scenario, the choice between a review and a compilation. Inspection findings commonly trace back to insufficient scepticism, often described as insufficient challenge of management, which appeared as a recurring root cause in Hollis Ward's own monitoring in lesson 1. Scepticism is an attitude, but it shows up in documentation: in the alternative explanations considered, the contradictory evidence sought, and the reasons recorded for accepting or rejecting management's position.
Technology changes how judgment is exercised but not the need for it. Analytics can test every journal entry, and AI tools can read every contract, but someone must decide which outputs matter, investigate the exceptions, and evaluate whether the evidence is sufficient. A practitioner who accepts a tool's output without understanding it is no more sceptical than one who accepts management's.
Capstone: the 2027 planning memorandum
The capstone draws the course together in a planning memorandum for the 2027 Tamarack group audit. The program summarizes the planned scoping, which the memorandum explains in detail.
# Capstone: scoping summary for the group audit plan (thousands of dollars, invented).
components = {  # name: (revenue, pre-tax income, planned work)
    "Parent operations": (210_000, 14_600, "full audit, group team"),
    "Distribution": (120_000, 7_600, "full audit, group team"),
    "Mexico": (58_000, 4_100, "full audit, component auditor"),
    "Snacks": (24_000, 1_100, "specified procedures: inventory and revenue"),
    "Cold storage investee (30%)": (0, 600, "analytical procedures at group level"),
}
rev = sum(v[0] for v in components.values()); pti = sum(v[1] for v in components.values())
full_rev = sum(v[0] for v in components.values() if v[2].startswith("full"))
full_pti = sum(v[1] for v in components.values() if v[2].startswith("full"))
for name, (r, p, work) in components.items():
    print(f"{name:<29}{r:>9,}{p:>8,}  {work}")
print(f"\nCoverage by full audits: revenue {full_rev/rev:.0%}, pre-tax income {full_pti/pti:.0%}")
print(f"Remaining pre-tax income not covered by full audits: {pti - full_pti:,}")Parent operations 210,000 14,600 full audit, group team Distribution 120,000 7,600 full audit, group team Mexico 58,000 4,100 full audit, component auditor Snacks 24,000 1,100 specified procedures: inventory and revenue Cold storage investee (30%) 0 600 analytical procedures at group level Coverage by full audits: revenue 94%, pre-tax income 94% Remaining pre-tax income not covered by full audits: 1,700
Full audits of parent operations, distribution and Mexico cover 94 per cent of revenue and pre-tax income. The remaining 1.7 million of pre-tax income, from snacks and the equity-method investee, is covered by specified procedures on the snacks subsidiary's inventory and revenue, where the risks lie, and by analytical procedures and the investee's audited statements. The memorandum's main sections, with the lessons they draw on, are summarized below.
| Section | Content for Tamarack 2027 | Lessons |
|---|---|---|
| Quality and resources | Engagement quality review; group audit specialist review of instructions; IT and valuation specialists; approved analytics tools only | 1 |
| Group scoping and materiality | Group materiality about 5% of pre-tax income; component performance materiality by judgment band; clearly trivial threshold communicated to all components | 2, 12 |
| Component auditors | Independence questionnaire and competence evaluation for the Mexican firm; tailored instructions; site visit for the inventory count; remote review of revenue and inventory work | 3 |
| Consolidation | Intercompany reconciliation tests; translation and policy-alignment testing; review of manual consolidation journals | 3 |
| IT environment | Access and change analyses on the cloud ERP and Mexican ERP; follow-up of 2026 access and change exceptions | 4 |
| Service organizations | Type 2 reports for payroll and the ERP vendor; bridge letters; testing of the newly implemented payroll clearing reconciliation | 5 |
| Internal control | Testing of key controls relied on; follow-up of the goodwill review weakness disclosed in the MD&A; communication of deficiencies under CAS 265 | 6 |
| Estimates and going concern | Independent range for inventory provision; specialist review of impairment model; covenant stress test | 7 |
| Completion and reporting | Subsequent events procedures to the report date; representations from group and component management; expected key audit matters | 8 |
| Other engagements | GHG limited assurance; contractual-basis audit of the Mexican lease statements by the component auditor | 11 |
| Independence | Fee and service screening; partner rotation plan; audit committee pre-approval | 12 |
The memorandum ends with a timetable and a communication plan: a planning meeting with the audit committee in October 2027, interim work and component instructions in November, the Mexican inventory count on December 31, year-end fieldwork in January and February 2028, and the auditor's report planned for early March 2028. It also records the matters carried forward from 2026: the goodwill review weakness, the missing payroll reconciliation, the access exceptions and the inventory provision method. Each is assigned to a team member with a planned procedure, so that the 2027 audit responds to what the 2026 audit learned.
Worked problem
An independence threat from a proposed service
Tamarack's CFO asks Hollis Ward's consulting group to design the access module for the new ERP, arguing that the audit team already knows the system's weaknesses. What should the firm do?
Show solution
- Designing a system that generates information for the financial statements the firm audits creates a self-review threat.
- For a listed entity, the IESBA-based provincial codes prohibit designing or implementing such systems for an audit client.
- No safeguard can reduce the threat to an acceptable level for this service.
- The firm declines the work; it may recommend that Tamarack engage another adviser, and it continues to audit the controls once implemented.
Answer: Decline the service; it is prohibited for a listed or issuer audit client.
Common mistakes
MistakeTreating independence as a once-a-year form.
InsteadScreen independence at acceptance, during the engagement and before signing, including component auditors and network firms.
MistakeAssuming any service is acceptable if fees are small.
InsteadSome services are prohibited regardless of fees; others need evaluation of threats and pre-approval.
MistakeLetting the assurance team help prepare the information it assures.
InsteadPreparing the subject matter creates a self-review threat; management must prepare and own it.
MistakeEquating audit quality with a clean inspection.
InsteadQuality is achieved engagement by engagement through judgment, scepticism, resources and supervision.
MistakeAccepting a tool's output as evidence without understanding it.
InsteadUnderstand how the tool works, investigate exceptions and evaluate whether the evidence is sufficient.
MistakeStarting each year's plan from a blank page.
InsteadCarry forward deficiencies, misstatements and lessons from the prior audit into the new plan.
Summary and key terms
- Independence frameworks identify self-interest, self-review, advocacy, familiarity and intimidation threats.
- Provincial codes aligned with IESBA prohibit certain services and require partner rotation for listed entities.
- Tamarack's fees are about 4% of firm revenue; the proposed ERP design work is prohibited.
- Audit quality is inspected by regulators and increasingly discussed with audit committees.
- Audit committees appoint the auditor, pre-approve services and evaluate performance.
- Professional scepticism is documented through the alternatives considered and evidence sought.
- Technology changes how judgment is exercised but not the need for it.
- The planning memorandum integrates quality, group scoping, IT, controls, estimates, reporting and independence.
- Public interest entity
- An entity, such as a listed entity, subject to additional independence requirements.
- Self-review threat
- The threat that a practitioner will not appropriately evaluate work the firm previously performed.
- Self-interest threat
- The threat that a financial or other interest will inappropriately influence judgment.
- Familiarity threat
- The threat that a long or close relationship will make the practitioner too sympathetic to the client.
- Intimidation threat
- The threat that pressure will deter a practitioner from acting objectively.
- Partner rotation
- A limit on the years a partner may serve on an engagement, followed by a cooling-off period.
- Audit quality indicators
- Measures of inputs and processes, such as hours and experience, used to discuss audit quality.
- Planning memorandum
- The document summarizing the overall audit strategy and plan for an engagement.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Name the five categories of threats to independence.
Show answer
Self-interest, self-review, advocacy, familiarity and intimidation.
Why is the ERP access module design prohibited?
Show answer
It involves designing a system that generates information for the financial statements, creating a self-review threat.
What share of firm revenue do Tamarack's fees represent?
Show answer
About 4 per cent.
Change the engagement partner's years in the program to 4. What does the output say?
Show answer
Three years remaining.
What coverage do full audits provide in the capstone scoping?
Show answer
94 per cent of revenue and pre-tax income.
How is the remaining pre-tax income covered?
Show answer
Specified procedures on snacks inventory and revenue, and analytical procedures and audited statements for the investee.
Give three matters carried forward from 2026 into the 2027 plan.
Show answer
The goodwill review weakness, the payroll reconciliation, the access exceptions and the inventory provision method.
Why must the GHG team avoid preparing the emissions statement?
Show answer
It would create a self-review threat; management must prepare and own the subject matter.
What questions might an audit committee ask its auditor?
Show answer
About group scoping, component auditors, specialists and technology, significant risks and responses, and inspection results.
How does professional scepticism appear in documentation?
Show answer
Through the alternatives considered, contradictory evidence sought and reasons for accepting or rejecting management's position.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.