
MBA-602 · Lesson 8 of 12 · 23 min
Legal structures, intellectual property and founder agreements
Dr. Marchetti invites a guest to the eighth session: a lawyer who has advised several hundred startups and who says that most of the legal problems she sees could have been avoided with a few hours of work at the start. Founders, she says, tend to put off legal work because it costs money and does not feel like progress. Then an investor's lawyers find that a co-founder never signed over the code he wrote, or that the company's name belongs to someone else, or that a departed founder still owns a third of the shares, and the financing stalls. The session covers the choices that should be made before the venture takes outside money: the legal form, the agreements among founders, the protection of intellectual property and the contracts with key partners.
Legal forms
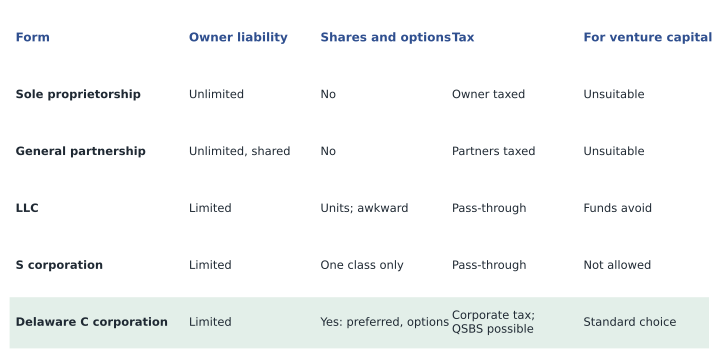
The simplest form is the sole proprietorship, in which one person carries on business in their own name or a registered business name. It costs almost nothing to set up, but the owner is personally liable for all the business's debts, and the business cannot issue shares to investors. A general partnership is the same arrangement for two or more people, each of whom is personally liable for the partnership's obligations, including those incurred by the other partners. Limited partnerships, in which some partners have limited liability, are used mainly for investment funds, including venture capital funds themselves.
A corporation is a separate legal person. It owns its assets, signs its contracts and is liable for its debts; shareholders risk only what they invested, apart from personal guarantees they give and certain liabilities, such as unpaid wages and some taxes, that the law places on directors. A corporation can issue different classes of shares, grant stock options and admit new investors without reorganizing, which is why almost every venture that intends to raise equity is incorporated. Founders sometimes start as a partnership and incorporate later, but moving assets and intellectual property into a new corporation creates tax and paperwork that are easier to avoid by incorporating at the start.
In the United States, corporations are created under state law, and most venture-backed startups incorporate in Delaware even if they operate elsewhere. Delaware's corporate statute is detailed and frequently updated, its Court of Chancery specializes in corporate disputes and decides them without juries, and its case law is the most developed in the country, so investors and their lawyers know what to expect. A Delaware corporation operating in another state must register there as a foreign corporation and pay that state's fees. Delaware's annual franchise tax can surprise founders, because the default calculation is based on authorized shares; most startups file using the alternative method based on assets, which usually produces a much smaller bill. Some companies have recently moved to Texas or Nevada, but Delaware remains the default for venture-backed firms.
Tax status and why it matters
Founders in the United States choose among a C corporation, an S corporation and a limited liability company, or LLC. S corporations and LLCs are pass-through entities whose profits and losses flow to the owners' personal tax returns, avoiding a second layer of corporate tax. But an S corporation can have no more than 100 shareholders, only one class of stock and generally only US individual shareholders, which rules out venture investors and preferred shares. Venture funds generally avoid investing in LLCs because pass-through income creates tax problems for their tax-exempt and foreign investors. So a venture that intends to raise venture capital is almost always a Delaware C corporation. A C corporation's shares may also qualify as qualified small business stock under section 1202 of the tax code. For stock issued after 4 July 2025, a holder can exclude 50 percent of the gain after three years, 75 percent after four and 100 percent after five, up to the greater of 15 million dollars or ten times the holder's basis, provided the company's gross assets did not exceed 75 million dollars when the stock was issued and the company runs a qualifying active business.
Second Ascent's founders follow the usual path for a venture expecting outside investment. They incorporate a single corporation, issue 10 million common shares to the three founders at a nominal price, adopt the standard vesting arrangements described in lesson 7 and put the intellectual property into the company from the start. They do not create a holding company for each founder at this stage, although their accountant points out that some founders do so for tax planning; it can be added later.
Founder share issuances
Founders usually buy their shares for a nominal amount at incorporation, subject to vesting. Because the shares can be repurchased if the founder leaves, the tax code treats them as restricted stock, and without further action the founder would be taxed on the value of the shares as each portion vests, when the company may be worth much more. The solution is an 83(b) election filed with the Internal Revenue Service within 30 days of the share issuance, which tells the IRS to tax the shares at their value on the issue date, typically almost nothing. Missing the 30-day deadline is one of the most common and costly startup mistakes, because it cannot be fixed later. Filing the election also starts the holding period for capital gains and for the qualified small business stock exclusion.
Shareholders' agreements
A shareholders' agreement sets the rules among the owners that the corporate statute and the company's articles or bylaws leave open. Typical terms include the composition of the board and who can appoint directors; matters that need approval by a supermajority of shareholders; restrictions on transferring shares; a right of first refusal, under which the company or other shareholders can buy shares before they are sold to an outsider; co-sale or tag-along rights, which let minority holders sell on the same terms if a majority holder sells; drag-along rights, which let a majority force minority holders to join a sale of the company; vesting and leaver terms; and deadlock procedures. Investors in later rounds will usually replace the founders' agreement with a more detailed one, but having an agreement from the start prevents the most common disputes.
In Delaware corporations, investors in priced rounds usually sign a set of documents based on the model legal documents published by the National Venture Capital Association, including a voting agreement, an investors' rights agreement and a right of first refusal and co-sale agreement. Founders who have signed a simple stockholders' agreement at the start should expect it to be replaced or folded into these documents at the first priced round.
Intellectual property
Intellectual property is often a startup's most valuable asset and the one most often left unprotected. Four kinds matter to most ventures. Patents protect inventions that are new, useful and not obvious, for up to 20 years from filing, in exchange for public disclosure. Trademarks protect names, logos and other signs that identify the source of goods or services, for as long as they are used and renewed. Copyright protects original works, including software code, text and designs, automatically from creation, though registration helps enforce it. Trade secrets protect valuable confidential information, such as methods, formulas and customer data, for as long as the owner takes reasonable steps to keep it secret.
The most important step is to make sure the company, not the individual founders or contractors, owns the intellectual property. Every founder, employee and contractor should sign an agreement assigning to the company any intellectual property they create in connection with the business, along with confidentiality obligations. Work done before incorporation, such as Tariq's booking prototype, should be assigned to the company in writing. In both countries, contractors generally own what they create unless they assign it, so a freelance designer who creates the logo owns the copyright unless the contract says otherwise. Investors' lawyers check these assignments in due diligence, and gaps can delay or kill a financing.
In the United States, patents and trademarks are registered with the United States Patent and Trademark Office. A provisional patent application gives an inventor a filing date and 12 months to file a full application, which is useful for startups that need to disclose an invention to investors or customers before they can afford full patent work. Trademark rights in the United States arise from use, but federal registration gives nationwide priority and stronger remedies. Design patents protect the ornamental design of a product. Trade secrets are protected by state law and, since 2016, by the federal Defend Trade Secrets Act.
Second Ascent's intellectual property is modest but real. Its name and logo should be protected by a trademark registration, and the founders' first legal task is a search, since several outdoor businesses use the word ascent. Its repair methods, the specifications for repairing many brands' products, are trade secrets, protected by confidentiality agreements and by limiting access to the method library. Its booking and repair-tracking software is protected by copyright. And its data on repair types, costs and failure rates across brands could become valuable to brands designing more repairable products, as long as contracts with brands and privacy policies with consumers allow it to be used. Patents are unlikely to matter, although Marta has designed a jig for replacing zippers on waterproof jackets that the lawyer thinks might be patentable.
Contracts with key partners
For many ventures, the most important legal document is not a shareholders' agreement but a contract with a key partner. Second Ascent depends on Cedarline for workshop space, referrals and overflow repairs, and lesson 2 identified that dependence as the venture's most serious potential flaw. The lawyer recommends a commercial agreement covering the term of the space lease and notice periods for ending it; the referral arrangements and fees in each direction; whether either side may compete in multi-brand repair, and for how long; the handling of customer data; and what happens if Cedarline is sold or changes strategy, through a change-of-control clause that gives Second Ascent time to move.
Cedarline's contribution also raises a question of equity. Cedarline will provide below-market space, a brand license to say that Second Ascent is Cedarline's authorized multi-brand repair partner, and its referral flow. In exchange, the founders propose to issue Cedarline 1.5 million shares, about 13 percent of the company after issuance, with the shares vesting over three years as Cedarline delivers the agreed space and referrals. Dr. Marchetti says this is a common structure for corporate partners: it aligns the partner's interests with the venture's, but founders should limit the partner's special rights. A corporate shareholder with a veto over financings or a right of first refusal on a sale of the company can frighten off later investors and potential acquirers.
Structures for social ventures
Hana's mobile clinic raises a different structural question. A nonprofit corporation that qualifies as a 501(c)(3) organization can receive tax-deductible donations and foundation grants, but it cannot issue shares to investors and its earnings cannot benefit private individuals. A for-profit corporation can raise equity but cannot receive deductible donations. Many states, including Delaware, allow public benefit corporations, which are for-profit corporations whose directors must balance shareholders' financial interests with a stated public benefit and the interests of those affected by the company's conduct. Some social ventures use two linked entities: a nonprofit that receives grants for the community program and a for-profit company that earns revenue from services. Hana thinks a nonprofit is the right start for the mobile clinic, because its likely funders are counties, health systems and foundations.
Tax on a successful exit
The legal form and share structure chosen at the start can make a large difference to what founders keep when they sell. The following code compares the tax on a founder's gain from selling shares in a successful exit, under simplified assumptions that a tax adviser would refine.
# United States: tax on a founder's gain with the section 1202 exclusion (simplified)
gain = 3_000_000          # founder's gain on selling stock issued after 4 July 2025
ltcg, niit = 0.20, 0.038  # federal long-term capital gains rate and net investment income tax
rate_1202 = 0.28          # federal rate on the non-excluded part of section 1202 gain

for years, excluded in ((2, 0.0), (3, 0.50), (4, 0.75), (5, 1.00)):
    if excluded == 0:
        tax = gain * (ltcg + niit)
    else:
        tax = gain * (1 - excluded) * (rate_1202 + niit)
print(f"held {years} years: excluded {excluded:4.0%}, federal tax {tax:>9,.0f}, effective rate {tax / gain:5.1%}")held 2 years: excluded 0%, federal tax 714,000, effective rate 23.8% held 3 years: excluded 50%, federal tax 477,000, effective rate 15.9% held 4 years: excluded 75%, federal tax 238,500, effective rate 8.0% held 5 years: excluded 100%, federal tax 0, effective rate 0.0%
The exclusion makes a large difference: a founder who holds qualifying stock for five years pays no federal tax on a gain within the cap, compared with about 714,000 dollars on a regular long-term gain. State tax is extra and varies; a few states do not follow the federal exclusion. The conditions for qualifying are technical and can be lost through choices such as redeeming stock from shareholders around the time of issuance or holding too many non-business assets, so Dr. Marchetti says the founders should ask their accountant to review qualification before every financing and before any sale.
Worked problem
Cleaning up before the seed round
Before approaching investors, Second Ascent's lawyer reviews the company's records and finds four issues: (1) Tariq built the booking prototype before incorporation and has not assigned it; (2) a freelance designer created the logo under an email agreement that says nothing about ownership; (3) the trademark search shows a ski touring shop in another province (or state) using the name Second Ascent; (4) the Cedarline agreement gives Cedarline a right to approve any future financing. Rank the issues and propose fixes.
Show solution
- Issue 1 is serious: the software is a core asset and the company does not own it. Fix: Tariq signs an assignment of all prior work to the company, which he should do readily as a shareholder.
- Issue 4 is serious for financing: a partner veto over future rounds will deter investors. Fix: renegotiate so that Cedarline has information rights and perhaps a right to participate in future rounds, but no approval right.
- Issue 3 needs legal advice: a business using the same name in a related field may have prior rights, especially in its region. Fix: assess the risk, approach the shop about coexistence, or choose a new name before spending on the brand.
- Issue 2 is easy to fix but must be fixed: the designer owns the copyright in the logo. Fix: obtain a written assignment, with a waiver of moral rights where applicable, for a modest fee.
Answer: Fix the software assignment and the Cedarline approval right first, since investors will treat them as conditions; resolve the name question before spending more on the brand; and get the logo assignment signed. All four are cheap to fix now and expensive to fix during a financing.
Common mistakes
MistakeIncorporate later, once the business is proven.
InsteadIncorporate before taking investment or creating valuable IP; moving assets later is costly and creates tax issues.
MistakeFounders automatically own what they create for the company, and so does the company.
InsteadOwnership must be assigned in writing by founders, employees and contractors; contractors own what they create unless they assign it.
MistakeGive a key corporate partner whatever rights it asks for in exchange for its support.
InsteadLimit partners' special rights; vetoes over financings or sales deter investors and acquirers.
MistakeTax planning for an exit can wait until there is a buyer.
InsteadQualification for exit tax benefits depends on choices made years earlier; review it before each financing.
Summary and key terms
- Ventures that expect outside equity incorporate, usually at the start, because corporations limit liability and can issue shares and options.
- Tax status matters: Canadian-controlled private corporations and qualified small business stock in the United States offer large benefits that can be lost.
- Founder shares are issued at a nominal price early, with vesting and the right tax filings.
- A shareholders' agreement sets board rights, transfer restrictions, drag-along and tag-along rights, leaver terms and deadlock procedures.
- The company must own its intellectual property through written assignments from founders, employees and contractors; protect names with trademarks and methods as trade secrets.
- Contracts with key partners should address term, exclusivity, data and change of control, and partners' equity should carry limited special rights.
- Limited liability
- The principle that shareholders risk only what they invested in a corporation.
- Shareholders' agreement
- A contract among owners setting rules on control, transfers and exits.
- Right of first refusal
- The right to buy shares before they are sold to an outsider, on the same terms.
- Drag-along right
- The right of a majority to require minority holders to join a sale of the company.
- Tag-along right
- The right of minority holders to sell on the same terms when a majority holder sells.
- IP assignment
- An agreement transferring intellectual property created by an individual to the company.
- Trade secret
- Valuable confidential information protected as long as reasonable steps keep it secret.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Why do venture investors generally require a corporation rather than a partnership?
Show answer
A corporation limits liability, can issue preferred shares and options, and admits new investors without reorganizing.
A contractor writes the first version of a venture's app under an invoice with no IP terms. Who owns the code?
Show answer
The contractor, as author, unless there is a written assignment; the company should obtain one.
What is the difference between a drag-along right and a tag-along right?
Show answer
Drag-along lets a majority force minority holders to sell with them; tag-along lets minority holders join a sale by a majority holder on the same terms.
Why might a corporate partner's right to approve future financings be a problem for a startup?
Show answer
Investors may refuse to invest when a partner can block or reshape rounds, and the right gives the partner leverage over the founders.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.