
FIN-301 · Lesson 11 of 12 · 31 min
Options and futures
Derivatives are contracts whose value depends on the price of something else: a share, an index, a bond, a currency or a commodity. They let investors and companies reshape risk, insuring against losses, locking in prices or taking leveraged positions, often far more cheaply than trading the underlying asset. They can also magnify losses dramatically when misused. This lesson covers the two main families. Options give the right, but not the obligation, to buy or sell at a fixed price. Futures and forwards are firm commitments to trade at a price agreed today. The lesson explains payoffs, the no-arbitrage relationships that tie option and futures prices to the underlying asset, the binomial and Black–Scholes pricing models, and the basic hedging strategies. FIN-201 lesson 9 introduced real options in capital budgeting; the same logic underlies everything here.
Calls and puts
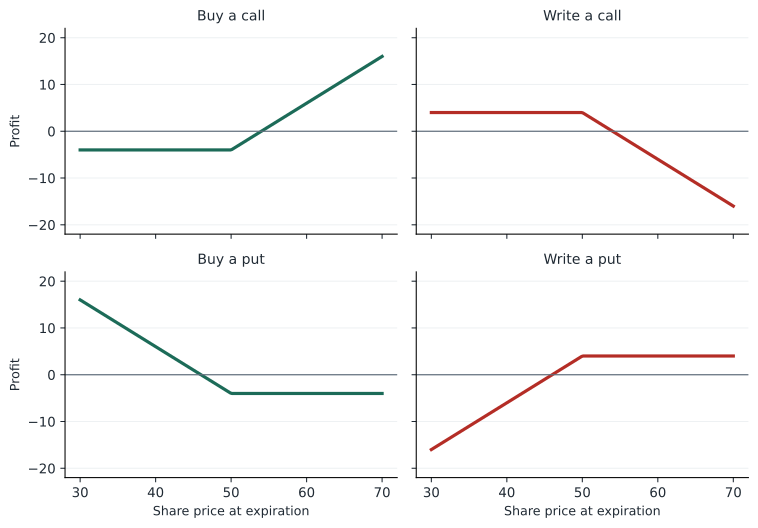
A call option gives its holder the right to buy the underlying asset at the exercise (strike) price on or before the expiration date; a put option gives the right to sell. American options can be exercised at any time up to expiration, European options only at expiration. The buyer pays the seller, or writer, a price called the premium. At expiration, a call is worth the share price minus the strike if that is positive, and nothing otherwise; a put is worth the strike minus the share price if positive. An option is in the money if exercising it now would pay off, at the money if the share price equals the strike, and out of the money otherwise. The buyer's loss is limited to the premium; a call writer's potential loss is unlimited, which is why brokers impose margin and approval requirements on option writing.
In the United States, listed options trade on several exchanges, including Cboe and Nasdaq exchanges, and clear through the Options Clearing Corporation. A standard equity option covers 100 shares. Under FINRA rules, brokers must approve customers for options trading and typically assign approval levels, with writing uncovered options requiring the highest level.
Put–call parity
A European call and put on the same share with the same strike and expiration are linked by an exact relationship. Buying a call and investing the present value of the strike in risk-free bonds gives the same payoff at expiration as buying the share and a put: either way, the investor ends with the larger of the share price and the strike. Two portfolios with identical payoffs must cost the same, otherwise there is an arbitrage. Put–call parity lets traders price a put from a call, create synthetic positions, and spot mispricing; for dividend-paying shares, the share price is reduced by the present value of dividends expected before expiration.
Worked problem
Using put–call parity
A share trades at $52. A 6-month European call with a strike of $50 costs $5.10. The continuously compounded risk-free rate is 4 % and no dividends are expected. What should the put with the same strike cost?
Show solution
- Present value of the strike = 50 × e^(−0.04 × 0.5) = 49.01.
- P = C + PV(K) − S = 5.10 + 49.01 − 52.00 = 2.11.
Answer: If the put traded at $2.50, a trader could sell the put, buy the call, short the share and lend the present value of the strike, locking in a riskless profit of about $0.39.
Option strategies
Options can be combined with shares and with each other to create almost any payoff. A protective put, buying a share and a put, sets a floor on losses at the strike minus the premium, like portfolio insurance. A covered call, owning a share and writing a call against it, earns the premium but gives up gains above the strike; it is popular with income-seeking investors, though it does not reduce downside risk much. A collar combines a protective put with a written call, financing the insurance by capping the upside. A straddle, buying a call and a put at the same strike, profits from a large move in either direction and is a bet on volatility. Spreads combine options with different strikes or expirations to fine-tune risk and cost.
| Strategy | Position | Profits when | Main risk |
|---|---|---|---|
| Protective put | Long share + long put | Share rises; loss floored if it falls | Cost of the premium |
| Covered call | Long share + short call | Share flat or rises modestly | Gives up gains above the strike |
| Collar | Long share + long put + short call | Share stays in a range | Upside capped |
| Straddle | Long call + long put, same strike | Large move either way | Loses both premiums if price is stable |
| Bull call spread | Long low-strike call + short high-strike call | Moderate rise | Limited gain and loss |
The binomial model
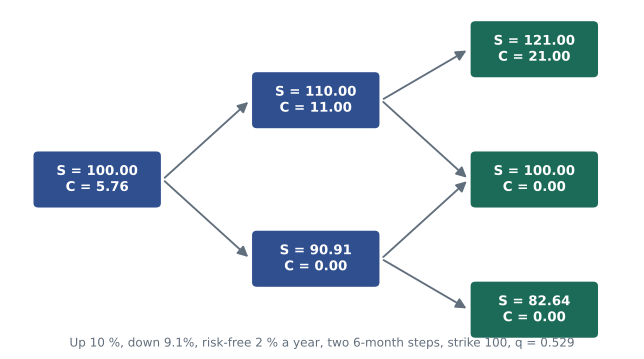
How much should an option cost? The key insight, from Fischer Black, Myron Scholes and Robert Merton, is that an option's payoff can be replicated by a combination of the share and borrowing. In a one-period binomial model, the share can rise to \( uS \) or fall to \( dS \). A portfolio of \( \Delta \) shares and some borrowing can be built to match the option's payoff in both states. The option must then cost the same as that portfolio. Remarkably, the probabilities of the up and down moves do not matter, and neither does the investor's risk aversion. The same answer comes from pretending investors are risk-neutral: weight the payoffs by risk-neutral probabilities and discount at the risk-free rate.
Worked problem
A one-period binomial call
A share at $100 will be worth either $120 or $85 in one year. The risk-free rate is 5 % (continuous). Price a one-year call with a strike of $100.
Show solution
- Payoffs: Cu = 20; Cd = 0.
- Hedge ratio Δ = (20 − 0) ÷ (120 − 85) = 0.5714 shares.
- Risk-neutral probability q = (e^0.05 − 0.85) ÷ (1.20 − 0.85) = (1.05127 − 0.85) ÷ 0.35 = 0.5751.
- C = e^−0.05 × 0.5751 × 20 = 10.94.
Answer: Holding 0.5714 shares and borrowing the present value of 48.57 replicates the call, and costs 57.14 − 46.20 = 10.94.
Splitting the year into many short steps, with up and down moves sized to match the share's volatility, gives a binomial tree that can price American options by checking at each node whether early exercise is worth more than holding on. As the number of steps grows, the price of a European option converges to the Black–Scholes value.
The Black–Scholes model
Black and Scholes, with Merton, derived in 1973 a closed-form formula for European options on a non-dividend-paying share whose price follows a continuous random walk with constant volatility. The formula depends on five inputs: the share price, the strike, the time to expiration, the risk-free rate and the volatility of the share's returns. Only volatility is not directly observable, and traders often work backward from market prices to the implied volatility. Scholes and Merton received the Nobel Prize in economics in 1997; Black had died in 1995.
\( N(\cdot) \) is the cumulative standard normal distribution. \( N(d_1) \) is the call's delta, the number of shares needed to hedge one option, and it rises toward 1 as the call moves deep into the money. Delta changes as the share price moves, so a delta hedge must be adjusted continually; the rate of change is gamma. Other sensitivities, called the Greeks, measure exposure to time decay (theta), volatility (vega) and interest rates (rho). Option prices rise with volatility, because a holder benefits from big moves in the favorable direction while losses are capped at the premium.
# Binomial and Black-Scholes option prices, implied volatility and a futures hedge
import math

def N(x):
    return 0.5 * (1 + math.erf(x / math.sqrt(2)))

def black_scholes(S, K, T, r, sigma, kind="call"):
    d1 = (math.log(S / K) + (r + sigma**2 / 2) * T) / (sigma * math.sqrt(T))
    d2 = d1 - sigma * math.sqrt(T)
    call = S * N(d1) - K * math.exp(-r * T) * N(d2)
    put = call + K * math.exp(-r * T) - S          # put-call parity
    return (call if kind == "call" else put), N(d1)

def binomial(S, K, T, r, sigma, steps, american=False, kind="put"):
    dt = T / steps
    u = math.exp(sigma * math.sqrt(dt)); d = 1 / u
    q = (math.exp(r * dt) - d) / (u - d); disc = math.exp(-r * dt)
    pay = (lambda s: max(K - s, 0)) if kind == "put" else (lambda s: max(s - K, 0))
    values = [pay(S * u**j * d**(steps - j)) for j in range(steps + 1)]
    for i in range(steps - 1, -1, -1):
        values = [disc * (q * values[j + 1] + (1 - q) * values[j]) for j in range(i + 1)]
        if american:
            values = [max(v, pay(S * u**j * d**(i - j))) for j, v in enumerate(values)]
    return values[0]

c, delta = black_scholes(100, 100, 0.5, 0.04, 0.25)
p, _ = black_scholes(100, 100, 0.5, 0.04, 0.25, "put")
print(f"Black-Scholes 6-month call {c:.3f} (delta {delta:.3f}), put {p:.3f}")
for n in (2, 10, 100, 500):
    print(f"binomial European put, {n:3d} steps: {binomial(100, 100, 0.5, 0.04, 0.25, n):.3f}")
print(f"binomial American put, 500 steps: {binomial(100, 100, 0.5, 0.04, 0.25, 500, american=True):.3f}")

# Implied volatility by bisection from a market call price of 8.50
lo, hi = 0.01, 2.0
for _ in range(100):
    mid = (lo + hi) / 2
    if black_scholes(100, 100, 0.5, 0.04, mid)[0] < 8.50: lo = mid
    else: hi = mid
print(f"implied volatility for a call priced at 8.50: {mid:.2%}")Black-Scholes 6-month call 8.008 (delta 0.580), put 6.028 binomial European put, 2 steps: 5.230 binomial European put, 10 steps: 5.855 binomial European put, 100 steps: 6.010 binomial European put, 500 steps: 6.024 binomial American put, 500 steps: 6.203 implied volatility for a call priced at 8.50: 26.78%
The binomial prices converge to the Black–Scholes put value as the number of steps rises, and the American put is worth slightly more than the European one because early exercise can be valuable when the put is deep in the money. Market prices imply a volatility for each strike and expiration; plotting them typically shows a smile or skew, with higher implied volatility for low-strike puts, evidence that traders price in fatter tails than the model's normal distribution, as lesson 3 described.
Futures and forwards
A forward contract obliges one party to buy and the other to sell an asset at a set price on a future date. It is negotiated privately, so it can be tailored but carries the risk that the other party fails to pay. A futures contract does the same on an exchange, with standardized terms and a clearing house that stands between buyer and seller. To protect the clearing house, futures are marked to market daily: gains and losses are settled in cash each day through margin accounts, and a trader whose account falls below the maintenance margin must top it up. Because only a small margin is posted, futures are highly leveraged.
Futures prices are tied to spot prices by arbitrage. An investor can buy the asset today and hold it, paying financing costs and receiving any income, or buy a futures contract and hold cash. The two strategies give the same position at delivery, so they must cost the same. This gives the cost-of-carry relationship: the futures price equals the spot price grown at the risk-free rate, minus the income the asset pays, plus storage costs for commodities.
Here \( q \) is the asset's dividend or income yield. For a share index with a 2 % dividend yield and a 4 % interest rate, the futures price is about 2 % a year above the index level.
The most traded US equity futures contract is the E-mini S&P 500 on the CME, worth US$50 times the index level, with a smaller Micro E-mini at US$5. Treasury futures and SOFR futures are among the most traded interest rate contracts in the world.
Hedging with futures
A portfolio manager who fears a market fall but does not want to sell shares, perhaps because of trading costs or taxes, can sell index futures. Gains on the futures offset losses on the portfolio. The number of contracts depends on the portfolio's value, its beta and the value of one contract. The hedge is imperfect: the portfolio may not move exactly with the index (basis and tracking risk), and the beta itself is an estimate. Futures can equally be bought to gain market exposure quickly, for example when a large cash inflow arrives.
Worked problem
Hedging an equity portfolio
A manager holds a $30 million US share portfolio with a beta of 1.1. The E-mini S&P 500 futures price is 6,000 and each contract is worth $50 times the index. How many contracts should be sold?
Show solution
- Value of one contract = 6,000 × 50 = 300,000.
- Contracts = 1.1 × 30,000,000 ÷ 300,000 = 110.
Answer: Selling these contracts removes most of the portfolio's market risk; what remains is the portfolio's firm-specific risk and its alpha, if any. Index levels are illustrative.
Common mistakes
MistakeAn option buyer can lose more than the premium.
InsteadThe buyer's loss is limited to the premium; it is the writer who faces large losses.
MistakeThe probability that a share rises determines the option price.
InsteadReplication and risk-neutral pricing make real-world probabilities irrelevant; volatility matters.
MistakeCovered calls are a low-risk way to earn extra income.
InsteadThey keep almost all the downside of owning the share while capping the upside.
MistakeFutures prices are forecasts of future spot prices.
InsteadThey are set by the cost of carry: spot price, interest rate, income and storage costs.
MistakeHedging with futures removes all risk.
InsteadBasis risk, tracking error and estimated betas leave some risk.
Summary and key terms
- Calls give the right to buy, puts the right to sell, at the strike price; buyers pay a premium.
- Put–call parity: C + PV(K) = S + P for European options.
- Protective puts, covered calls, collars and straddles reshape payoffs for different views.
- Binomial pricing replicates the option with shares and borrowing; risk-neutral probabilities give the same price.
- Black–Scholes prices European options from S, K, T, r and σ; delta is N(d1).
- Futures are standardized, marked to market daily and priced by the cost of carry, F = S e^((r − q)T).
- Index futures hedge market risk: contracts = β × portfolio value ÷ contract value.
- Call option
- The right to buy an asset at a fixed price before or at expiration.
- Put option
- The right to sell an asset at a fixed price before or at expiration.
- Strike price
- The price at which an option can be exercised.
- American option
- An option that can be exercised at any time up to expiration.
- Put–call parity
- The no-arbitrage relationship between European call and put prices.
- Risk-neutral probability
- A probability used to price derivatives by discounting expected payoffs at the risk-free rate.
- Delta
- The change in an option's price for a one-dollar change in the underlying price.
- Implied volatility
- The volatility that makes a pricing model match an option's market price.
- Marking to market
- Daily settlement of gains and losses on futures through margin accounts.
- Cost of carry
- The net cost of holding an asset until a future date, which links futures and spot prices.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Strike $40, share at expiration $47. Payoff of a call and a put?
Show answer
Call $7; put $0.
A call costs $3.20, S = $45, K = $45, PV(K) = $44.10. Put price from parity?
Show answer
3.20 + 44.10 − 45 = 2.30.
You buy a share at $60 and a $55 put for $2. Minimum value of the position at expiration (excluding cost)?
Show answer
$55, so the maximum loss is 60 + 2 − 55 = $7.
S = 50, u = 1.2, d = 0.9, e^(rΔt) = 1.03. Risk-neutral probability?
Show answer
(1.03 − 0.9) ÷ 0.3 = 0.4333.
In that tree, value a one-period call with K = 50.
Show answer
Cu = 10, Cd = 0; C = 0.4333 × 10 ÷ 1.03 = 4.21.
Why does a higher volatility raise both call and put prices?
Show answer
Holders gain from big favorable moves while losses are capped at the premium.
Index 5,000, r = 4 %, dividend yield 1.5 %, T = 0.5. Futures price?
Show answer
5,000 × e^(0.025 × 0.5) = 5,062.89.
A futures position loses $3,000 in a day and the margin account falls below maintenance. What happens?
Show answer
A margin call requires the trader to restore the account to the initial margin.
Portfolio $12 million, beta 0.9, futures value per contract $300,000. Contracts to sell?
Show answer
0.9 × 12,000,000 ÷ 300,000 = 36.
Portfolio task: look up an option chain for one large company and note how implied volatility varies with the strike.
Show answer
Answers vary; usually implied volatility is higher for low strikes.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.