
ACCT-331 · Lesson 12 of 12 · 29 min
The auditor's report, critical audit matters and capstone
Everything in the audit leads to a single document of a page or two. The auditor's report is the only part of the audit that most users ever see, and its wording is closely prescribed so that readers can tell at a glance what kind of opinion is being expressed and what it covers. This final lesson works through the structure of the report, the types of opinion and when each applies, the reporting of critical audit matters, emphasis of matter and other paragraphs, and the auditor's responsibilities for other information in the annual report. It ends with a capstone that brings the Fairhaven audit to its conclusion and drafts its report. ACCT-431 extends these topics to review engagements, special-purpose frameworks, group audits and other assurance services, and ACCT-341 builds on the internal control material for accounting information systems.
The structure of the unmodified report
AS 3101 prescribes the elements of the auditor's report on an issuer's financial statements. Since 2017, the report has put the opinion first, followed by the basis for opinion, and has disclosed the auditor's tenure. AU-C 700, as revised by SAS 134, prescribes a similar opinion-first format for non-issuer audits.
| Section | Content |
|---|---|
| Title | Report of Independent Registered Public Accounting Firm |
| Addressee | The shareholders and the board of directors |
| Opinion | Identifies the statements audited and states whether they present fairly, in all material respects, in accordance with the framework |
| Basis for opinion | States that the statements are management's responsibility, that the audit was conducted under PCAOB standards, and that the firm is registered and independent |
| Critical audit matters | Matters communicated to the audit committee that relate to material accounts or disclosures and involved especially challenging, subjective or complex judgment |
| Other information | Addressed separately under AS 2710; not a required section of the report |
| Responsibilities | Described within the basis for opinion |
| Signature, location, date | Firm signature, city and state, date; auditor tenure stated; engagement partner named on PCAOB Form AP |
The date of the report matters. It is no earlier than the date on which the auditor has obtained sufficient appropriate evidence, including evidence that the complete set of statements has been prepared and that those with authority have taken responsibility for them, usually by the board's approval. The auditor's responsibility for subsequent events searching runs to this date.
Types of opinion
The opinion depends on two questions. First, what is the nature of the problem? Either the statements are materially misstated, or the auditor has been unable to obtain sufficient appropriate evidence (a limitation on scope). Second, how pervasive are its effects? An effect is pervasive if it is not confined to specific elements, accounts or items, or if, though confined, it represents a substantial proportion of the statements, or if it concerns disclosures fundamental to users' understanding.
| Nature of the matter | Material but not pervasive | Material and pervasive |
|---|---|---|
| Statements are materially misstated | Qualified opinion (except for) | Adverse opinion |
| Unable to obtain sufficient appropriate evidence | Qualified opinion (except for) | Disclaimer of opinion |
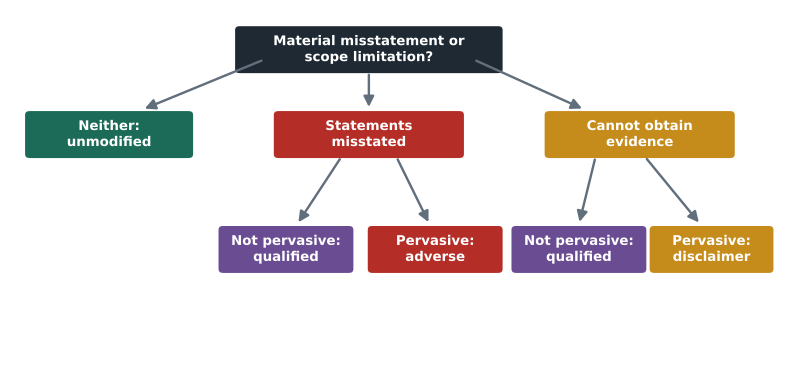
AS 3105 governs departures from unqualified opinions in issuer audits; AU-C 705 applies to non-issuers. The SEC generally does not accept qualified opinions or disclaimers in filings, so in practice issuer reports are almost always unqualified.
# Choosing the type of opinion: the nature of the problem and how pervasive it is
def opinion(problem, material, pervasive):
    if not material:
        return "Unmodified"
    if problem == "misstatement":
        return "Adverse" if pervasive else "Qualified (except for)"
    if problem == "scope limitation":
        return "Disclaimer of opinion" if pervasive else "Qualified (except for)"
    raise ValueError(problem)

cases = [
    ("Uncorrected projected misstatement of 146", "misstatement", False, False),
    ("Inventory write-down of 1,500 refused by management", "misstatement", True, False),
    ("Statements prepared on a going concern basis that is inappropriate", "misstatement", True, True),
    ("Count records destroyed; inventory of 38,500 cannot be verified", "scope limitation", True, True),
    ("One store's inventory of 900 inaccessible after a flood", "scope limitation", True, False),
]
for desc, prob, mat, perv in cases:
print(f"{desc:<70} -> {opinion(prob, mat, perv)}")Uncorrected projected misstatement of 146 -> Unmodified Inventory write-down of 1,500 refused by management -> Qualified (except for) Statements prepared on a going concern basis that is inappropriate -> Adverse Count records destroyed; inventory of 38,500 cannot be verified -> Disclaimer of opinion One store's inventory of 900 inaccessible after a flood -> Qualified (except for)
When the opinion is modified, the basis for opinion section is retitled (for example, Basis for Qualified Opinion) and explains the matter, quantifying its effects where practicable. A disclaimer is unusual: the auditor states that it does not express an opinion, explains why, and omits most of the description of the audit, because describing work that did not produce an opinion could mislead.
Critical audit matters
Critical audit matters (CAMs) are matters arising from the audit that were communicated or required to be communicated to the audit committee and that relate to accounts or disclosures material to the financial statements and involved especially challenging, subjective or complex auditor judgment. AS 3101 has required CAMs for large accelerated filers since fiscal years ending on or after June 30, 2019, and for other issuers since December 15, 2020, with exceptions such as emerging growth companies. For each CAM, the report identifies the matter, describes the principal considerations that led the auditor to determine it was a CAM, describes how it was addressed in the audit, and refers to the relevant accounts or disclosures.
The purpose is transparency: rather than a boilerplate report identical for every company, users see where the auditor focused and why. A CAM is not a modification of the opinion, and it should not be used to disclose information management has not disclosed, though it may lead management to improve its disclosures. For Fairhaven, the team identifies two matters.
- Valuation of inventory: slow-moving styles, a significant risk involving subjective judgments about selling prices and markdowns, addressed by testing the write-down against subsequent sales, evaluating management's assumptions for bias, and testing the data conversion of the new warehouse system.
- Revenue recognition for wholesale sales with return rights: a presumed fraud risk involving judgment about the refund liability, addressed by cut-off testing, confirmations, review of January credit notes and testing of the return-rate assumptions.
Emphasis of matter, other matter and other information
An emphasis of matter paragraph draws users' attention to a matter properly presented or disclosed in the statements that is fundamental to their understanding, such as a significant subsequent event or a major catastrophe. An other matter paragraph refers to something not presented in the statements that is relevant to users' understanding of the audit or the auditor's responsibilities, such as the fact that the prior period was audited by another auditor. Neither modifies the opinion. Under AS 3101, these are called explanatory paragraphs, which are required in some circumstances, such as substantial doubt about going concern or a change in accounting principle, and emphasis paragraphs, which are optional.
Other information in documents containing audited statements, such as the rest of the Form 10-K, is covered by AS 2710: the auditor reads it and considers whether it is materially inconsistent with the statements, and if so, determines whether the statements or the other information need revision. Unlike the international standards, AS 2710 does not require a section of the report on other information.
The integrated audit report
As an accelerated filer, Fairhaven receives an opinion on ICFR as well as on its financial statements. Bramble Shaw may issue a combined report or two separate reports that refer to each other. Because the credit approval deficiency found in lesson 6 was evaluated as a significant deficiency, not a material weakness (compensating controls in the monthly aging review reduced the likelihood of a material misstatement), the ICFR opinion is unqualified. Had it been a material weakness, the ICFR opinion would be adverse, while the financial statement opinion could still be unqualified.
Capstone: completing the Fairhaven audit
It is February 2027. The team has finished its procedures, management has agreed to the corrections described in lesson 11, and the engagement partner is preparing for the audit committee meeting. The program below posts the agreed adjustments to the draft figures and reassesses materiality and the debt covenant.
# Capstone: Fairhaven's audited figures after the corrections agreed with management (thousands of dollars)
draft = {"revenue": 184_000, "pretax": 12_600, "receivables_net": 21_400 - 650, "inventory": 38_500,
         "payables": 17_800, "equity": 64_400, "debt": 46_000}
tax_rate = 0.27
adj = [  # (description, revenue, pretax, receivables_net, inventory, payables)
    ("Revenue cut-off", -307, -123, -307, 184, 0),
    ("Unrecorded purchases and utilities", 0, -359, 0, 0, 359),
    ("Receivables items found in sample", -25, -25, -25, 0, 0),
    ("Allowance increase", 0, -254, -254, 0, 0),
    ("Inventory write-down increase", 0, -133, 0, -133, 0),
]
final = dict(draft)
for d, rev, pt, ar, inv, ap in adj:
    final["revenue"] += rev; final["pretax"] += pt; final["receivables_net"] += ar
    final["inventory"] += inv; final["payables"] += ap
after_tax = sum(a[2] for a in adj) * (1 - tax_rate)
final["equity"] = round(draft["equity"] + after_tax)
for k in draft:
    print(f"{k:<18}{draft[k]:>10,}{final[k]:>10,}{final[k] - draft[k]:>+9,}")
print(f"Debt to equity after corrections: {final['debt'] / final['equity']:.3f} (covenant 0.75)")
print(f"Materiality reassessed at 5% of final income before tax: {0.05 * final['pretax']:.0f}")
print("Remaining uncorrected misstatement: 146 (projected), below reassessed materiality")revenue 184,000 183,668 -332 pretax 12,600 11,706 -894 receivables_net 20,750 20,164 -586 inventory 38,500 38,551 +51 payables 17,800 18,159 +359 equity 64,400 63,747 -653 debt 46,000 46,000 +0 Debt to equity after corrections: 0.722 (covenant 0.75) Materiality reassessed at 5% of final income before tax: 585 Remaining uncorrected misstatement: 146 (projected), below reassessed materiality
The corrections reduce income before tax from 12,600 to 11,706. Receivables, net of the allowance, fall by 586, inventory rises slightly because the cut-off correction puts back the cost of goods not yet shipped and is offset by the larger write-down, and payables rise by 359. Equity falls by about 650 after tax, and debt to equity rises to about 0.72, still inside the 0.75 covenant. Reassessed materiality, at 5 percent of final income, is about 585; the remaining projected misstatement of 146 is well below it, and below performance materiality, so it can be left uncorrected.
| Matter | Lesson | Resolution |
|---|---|---|
| Independence: senior with shares; prohibited services proposed | 2 | Senior removed; IT and valuation work declined |
| Materiality 630; performance 410; trivial 30 | 5 | Reassessed at about 585; conclusions unchanged |
| Credit approval control failed | 6, 8 | Extended receivables testing; deficiency reported to governance |
| MUS upper limit 702 over tolerable 410 | 8 | Management investigated; known items corrected; projected 146 remains |
| Cut-off overstatement of revenue 307 | 9 | Corrected |
| Allowance understated 254; write-down understated 133 | 9, 10 | Corrected after qualitative evaluation |
| Unrecorded liabilities 359 | 10 | Corrected |
| Fictitious invoice by a sales representative | 8, 11 | Isolated; reported to the audit committee |
| Going concern | 11 | No material uncertainty; covenant headroom discussed |
| Critical audit matters | 12 | Inventory valuation; wholesale revenue with return rights |
With all matters resolved, the remaining uncorrected misstatement immaterial, the representation letter signed and the engagement quality reviewer's concurrence obtained, the opinion is unmodified. The report is dated on the day the board approves the statements, and the engagement partner signs it for the firm.
Worked problem
Drafting the opinion paragraph
Write the opinion paragraph for Fairhaven's 2026 statements.
Show solution
- Identify the entity and the statements: the balance sheet as of December 31, 2026, and the related statements of operations, comprehensive income, stockholders' equity and cash flows for the year, with notes.
- State that the statements present fairly, in all material respects, the financial position and the results and cash flows.
- Name the framework: accounting principles generally accepted in the United States of America.
Answer: "In our opinion, the financial statements present fairly, in all material respects, the financial position of Fairhaven Outdoor Gear Inc. as of December 31, 2026, and the results of its operations and its cash flows for the year then ended, in conformity with accounting principles generally accepted in the United States of America."
Worked problem
A different ending
Suppose management had refused to record the inventory write-down of 133 and the allowance increase of 254, leaving 533 uncorrected and income above the bonus target. What opinion would follow?
Show solution
- The uncorrected misstatements are material because of the bonus-target effect.
- They are confined to inventory and receivables and are not pervasive.
- The statements are materially misstated, but not pervasively.
Answer: A qualified (except for) opinion, with a basis for qualified opinion section quantifying the effects; in an SEC filing, management would in practice have to correct the statements, because the SEC does not accept qualified opinions.
Common mistakes
MistakeThinking a CAM is a qualification.
InsteadIt explains where the auditor focused; the opinion remains unmodified.
MistakeDating the report before the board approves the statements.
InsteadThe report is dated no earlier than when sufficient appropriate evidence, including approval, is obtained.
MistakeIssuing a disclaimer for a material but non-pervasive scope limitation.
InsteadA non-pervasive limitation leads to a qualified opinion; a disclaimer is for pervasive ones.
MistakeUsing an emphasis of matter paragraph to fix inadequate disclosure.
InsteadInadequate disclosure is a misstatement and leads to a modified opinion.
MistakeIgnoring other information in the annual report.
InsteadAS 2710 requires the auditor to read it for material inconsistencies.
Summary and key terms
- The report puts the opinion first, followed by the basis for opinion and the responsibilities of each party.
- Opinions are unmodified, qualified, adverse or a disclaimer, depending on the nature and pervasiveness of the matter.
- AS 3101 requires critical audit matters involving especially challenging, subjective or complex judgment.
- Emphasis of matter and other matter paragraphs do not modify the opinion.
- AS 2710 requires reading other information for material inconsistencies.
- Fairhaven's corrected income before tax is 11,706; the remaining 146 is immaterial, and the opinion is unmodified.
- Two matters, inventory valuation and wholesale revenue with return rights, are reported as critical audit matters.
- Critical audit matter
- A matter communicated to the audit committee involving especially challenging, subjective or complex judgment, reported under AS 3101.
- Unmodified opinion
- An opinion that the statements present fairly in all material respects.
- Qualified opinion
- An opinion that the statements are fairly presented except for the effects of a material but not pervasive matter.
- Adverse opinion
- An opinion that the statements are not fairly presented because of material and pervasive misstatement.
- Disclaimer of opinion
- A statement that the auditor does not express an opinion because of a pervasive inability to obtain evidence.
- Pervasive
- Effects not confined to specific items, or substantial, or fundamental to users' understanding.
- Emphasis of matter paragraph
- A paragraph drawing attention to a matter properly presented that is fundamental to understanding.
- Other matter paragraph
- A paragraph on something not in the statements relevant to users' understanding of the audit.
- Other information
- Information in the annual report other than the statements and the auditor's report.
- Date of the auditor's report
- The date on which sufficient appropriate evidence, including approval of the statements, has been obtained.
Practice problems
Work each problem on paper first, then reveal the answer to check.
What two questions determine the type of modified opinion?
Show answer
The nature of the matter (misstatement or scope limitation) and whether its effects are pervasive.
Rerun the opinion program with the inventory write-down refusal treated as pervasive. What opinion results?
Show answer
Adverse.
A flood makes one store's inventory of 900 impossible to verify, and no alternative procedures work. What opinion?
Show answer
Qualified, because the possible effect is material but not pervasive.
Which issuers are exempt from CAM reporting?
Show answer
Emerging growth companies, among a few others such as brokers and dealers and investment companies.
Rerun the capstone program with a tax rate of 25 percent. What is equity after corrections?
Show answer
About 64,400 − 0.75 × 894 = 63,730.
What is reassessed materiality at Fairhaven?
Show answer
About 585, 5 percent of 11,706.
Does a CAM modify the opinion?
Show answer
No.
What is the difference between an emphasis of matter and an other matter paragraph?
Show answer
Emphasis of matter refers to something in the statements; other matter to something outside them relevant to the audit.
When is the auditor's report dated?
Show answer
No earlier than the date on which sufficient appropriate evidence, including approval of the statements, is obtained.
Name the two matters reported for Fairhaven.
Show answer
Valuation of inventory, and revenue recognition for wholesale sales with return rights.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.