
SLS-222 · Lesson 9 of 12 · 19 min
Selling to executives
▶ Video coming soon A video version of this lesson is on the way.
On Wednesday, November 11, 2026, Maya had twenty-five minutes with Raymond Wiebe, Keystone's president and the son of its founder, and with Marlene Toews. Rob came too, as Ridgeline's executive sponsor for the account. The meeting had taken Dale Petrie two weeks to arrange, and Raymond had agreed to it on one condition, which Dale passed on word for word: "Tell them I've got twenty-five minutes, and I don't want a slide show."
Maya prepared for that meeting more carefully than for any meeting so far in her time at Ridgeline. At the value desk the day before, Rob had walked her through what changes when the buyer is an executive.
What is different about executives
Executives are not simply senior buyers. They decide which problems the organization will spend money on at all, they balance competing demands for the same capital, and they answer to owners, boards or councils. They usually see a purchase like the training centre as one of many possible uses of 48,000 dollars, alongside new production equipment, hiring or paying down debt. Their questions are broader and shorter.
| A manager tends to ask | An executive tends to ask |
|---|---|
| Which product is best? | Is this the right problem to spend money on now? |
| How does it work? | What happens to the business if we do it, and if we don't? |
| What does it cost? | What do we get back, how soon, and how sure are we? |
| How long will installation take? | What could go wrong, and who is accountable? |
| Can you meet our specification? | Does this fit where we are taking the company? |
Neil Rackham's research in large sales found that senior decision makers responded to sellers who understood the implications of a problem for the business, not to those who described products well. Later work on business buying, including Gartner's research on buying groups of six to ten people, describes executives as the people who settle disagreements within those groups and approve the final spend. The common thread is that the executive conversation is about the business, and the seller who cannot talk about the business is handed back to the manager.
Getting access
Executives protect their time, and a seller asking for a meeting cold rarely gets one. Access usually comes through someone inside the customer who has credibility with the executive and a reason to want the seller in the room: a champion, in the language of SLS-211. At Keystone, that was Dale. Maya's job was to give Dale a good reason to spend his credibility on her. She did that by showing him, before asking, that she understood what Raymond cared about: dealer relationships, a difficult year for farm incomes and the cost of the company's hotel bills.
Executive meetings also go better with a peer on the seller's side. Many companies, Ridgeline among them, assign an executive sponsor to each key account: a senior leader who builds a relationship with the customer's leaders, attends key meetings and can make commitments the account executive cannot. Rob's role in the room was not to sell but to show that Ridgeline's leadership stood behind what Maya promised, and to answer any question about Ridgeline itself.
Preparing: the executive brief
Rob's rule for executive meetings was that everything important should fit on one page, which the seller could leave behind or send in advance. Ridgeline called it the executive brief. It was not a summary of the proposal; it was the argument for the decision, in the executive's terms.
| Part of the brief | What it says | Keystone |
|---|---|---|
| The situation | The business issue, in the customer's words | Dealer training is growing; it now costs about 27,800 dollars a year in hotel rooms and trips |
| Why it matters | The impact on the business | Training keeps dealers selling Keystone equipment; costs rise with every new dealer |
| The recommendation | What Ridgeline proposes, in a sentence | Turn six unused plant rooms into a training centre with video and booking |
| The investment | Total cost and payment options | 48,000 dollars, or about 962 dollars a month over five years |
| The return | Payback and the customer's own measure | Payback in about 23 months on Keystone's figures |
| The risks and how they are handled | What could go wrong | Installation in January quiet weeks; four-hour service; price held to January 31 |
| The decision needed | What, by whom, by when | Board approval at the January meeting |
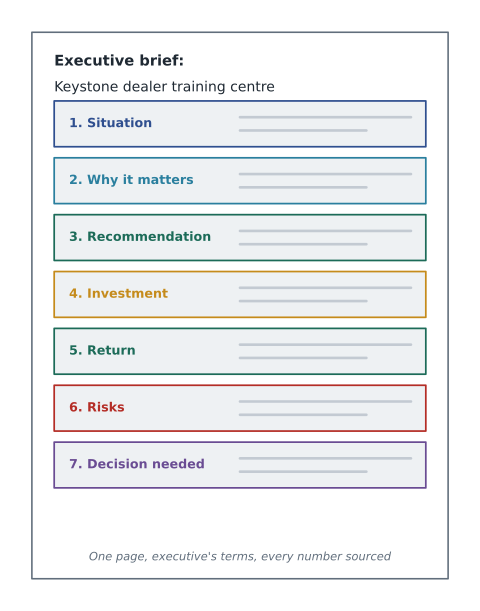
Putting the numbers in an executive's terms
Executives think in scale and in comparisons. Maya prepared three numbers she could say in a sentence each, all from figures Keystone already knew.
Worked problem
Three ways to state the training-centre investment
The training centre costs 48,000 dollars plus RoomFlow at 3,240 dollars a year, and Keystone ran 16 hotel training days in 2025 at about 1,100 dollars a day. Keystone's revenue is 42 million dollars. Calculate: (a) the investment as a share of a year's revenue; (b) the five-year cost per training day if Keystone keeps running 16 days a year; (c) the net benefit lost for each month the decision is delayed, using the net annual benefit of 24,560 dollars.
Show solution
- \[\text{(a) } \frac{48{,}000}{42{,}000{,}000} \approx 0.0011 \approx 1.1 \text{ in } 1{,}000\]
- \[\text{(b) } \frac{48{,}000 + 5(3{,}240)}{5 \times 16} = \frac{64{,}200}{80} \approx 803 \text{ dollars per day}\]
- \[\text{(c) } \frac{24{,}560}{12} \approx 2{,}047 \text{ dollars per month}\]
Answer: The investment is about one-tenth of 1 in 100 of a year's revenue; over five years each training day costs about 800 dollars in Keystone's own rooms against 1,100 in a hotel; and every month of delay costs about 2,000 dollars of savings.
The second number was the one that registered. Raymond knew the hotel bills. Hearing that his own rooms would cost about 800 dollars a training day over five years, against 1,100 for a hotel, and that the rooms would be available for other meetings between training days, was easier to weigh than any ROI percentage.
In the room
Maya used the first two minutes to confirm the situation rather than to present. "Dale tells me dealer training is now sixteen days a year in hotels, and growing. Is that the issue you'd most like to solve, or is there something bigger behind it?" Raymond's answer took four minutes and was more useful than anything in her brief: Keystone was about to add a second dealer group in Manitoba and was worried about training a new network at a distance. That made video training more valuable, not less.
The rest of the meeting followed a pattern Rob had suggested: confirm the issue, state the recommendation and the return in two sentences, then stop and let the executive steer. Marlene asked about the lease option and the January price hold. Raymond asked who would be accountable if the installation ran into the shipping season. Rob answered that one: Ridgeline would commit in writing to finish by February 15 and would provide loaner equipment for any room not ready. Maya never opened her laptop.
| Do | Avoid |
|---|---|
| Confirm the business issue in the first minutes | Starting with your company's history or a product overview |
| State the recommendation and the return briefly, then listen | Walking through every feature or slide |
| Use the customer's own numbers and words | Industry statistics the executive cannot check |
| Answer risk questions directly, with commitments | Promising that nothing can go wrong |
| Agree the next step and who owns it | Leaving with "we'll be in touch" |
| Finish early if the business is done | Using every remaining minute |
After the meeting
Maya sent a short follow-up that afternoon, as SLS-212 recommended: three sentences confirming what had been discussed, the revised one-page brief with a line added about the Manitoba dealer group, and the next step, which was for Marlene to put the proposal on the January board agenda with the lease and purchase options. She copied Dale, so that the person who had arranged the meeting knew exactly what had happened.
Rob also made a note in the CRM's executive sponsor section: Raymond Wiebe preferred plain conversation, disliked slides, cared most about the dealer network and responded well to direct answers about risk. That note would matter for every future executive conversation with Keystone, whoever on Ridgeline's side had it.
Going around people
One thing Rob warned Maya never to do was to use an executive meeting to go around the people who had been working with her. Sellers sometimes ask for an executive meeting because a manager is slow or skeptical, hoping the executive will overrule them. It occasionally works once, and it usually destroys the relationship with the manager, who will be there long after the executive has moved on to other things. Maya's meeting worked because Dale had arranged it, attended it and had his view respected in it.
When the decision belongs to a board
Raymond Wiebe would not decide on the training centre alone. Keystone's owners met as a board once a quarter, and any capital purchase over 20,000 dollars went to them. Many organizations work the same way: a school division's board of education, a city council, a hospital's finance committee, a family company's board of directors. The seller is almost never in the room when the board decides. The case has to be carried by someone else.
That changes what the seller must provide. A board member who has not met Maya and has ten minutes to read an agenda item needs a document that stands on its own. Marlene would take the proposal to the board, so the material had to work for her: Keystone's own format, Keystone's figures, and nothing that sounded like a sales pitch.
| What the person carrying the case needs | Why | What Maya gave Marlene |
|---|---|---|
| The decision in one sentence | Board items start with the motion | "Approve 48,000 dollars, or a five-year lease, for a dealer training centre in rooms 4 to 9" |
| The figures in the board's usual format | Familiar formats are easier to approve | Payback, the three-year return and the lease option, in Keystone's capital request template |
| Alternatives considered | Boards ask "what else did we look at?" | Keep using hotels; the regional integrator's quote; a four-room option |
| Risks and protections | Directors are responsible for risk | Fixed completion date, loaner equipment, price held to January 31 |
| Who will be accountable inside the company | A project needs an owner | Linda Sorensen for training; Dale Petrie for the rooms |
Maya also offered to be available by phone during the board meeting in case a question came up that Marlene could not answer, and to attend if invited. She was not invited, which is normal. Rob's comment was that the best measure of a seller's work for a board decision is whether the champion can present it confidently without the seller.
Preparing with public information
Executives notice when a seller has done homework, and much of the useful information is public. For a private company like Keystone, Maya used its website and news releases, its job postings (three openings for dealer support staff told her the dealer network was growing), trade association news about farm-equipment sales, and her own CRM history. For public companies, annual reports and investor presentations set out the executive team's priorities in their own words. For public bodies, council and board minutes record exactly what leaders have said about budgets and priorities.
The purpose of the homework is not to recite it. It is to ask a sharper first question and to avoid wasting the executive's time on things the seller could have found out alone. Asking a president "What are your plans for the dealer network?" is fine. Asking "Your posting for three dealer support roles suggests the network is growing; how is training keeping up?" shows that the seller has thought about the business before arriving.
Executives also notice when a seller has not done the homework. A wrong fact about the customer's own business, a competitor's name used in place of the customer's, or a question about something on the front page of the customer's website can end an executive's interest in seconds. Rob's last instruction before the meeting was to read Keystone's website once more that morning, in case anything had changed.
Common mistakes
MistakeAn executive is a senior buyer who wants the same detail as a manager.
InsteadExecutives decide whether the problem is worth solving at all, and want the business case briefly.
MistakeThe best way to reach an executive is to go around the manager.
InsteadAccess usually comes through a champion; going around people damages the relationship that matters most.
MistakeA thorough slide presentation shows respect for an executive's time.
InsteadA one-page brief, a short statement and listening usually work better.
MistakeExecutives are persuaded by impressive industry statistics.
InsteadThey are persuaded by their own numbers, stated in terms they already use.
Summary and key terms
- Executives decide which problems are worth spending on, balance competing uses of capital and answer to owners or boards.
- Their questions are broader and shorter than a manager's.
- Access usually comes through a champion, and an executive sponsor on the seller's side adds weight.
- A one-page executive brief sets out the situation, why it matters, the recommendation, the investment, the return, the risks and the decision needed.
- Numbers should be stated in the executive's terms, such as cost per training day or the cost of delay.
- In the meeting, confirm the issue, state the recommendation briefly, listen and agree a next step.
- Follow up promptly and never use an executive to go around the people who opened the door.
- Executive sponsor
- A senior leader on the seller's side who builds relationships with the customer's leaders on a key account.
- Champion
- A person inside the customer with credibility and a reason to help the seller succeed.
- Executive brief
- A one-page argument for a decision, written in the executive's terms.
- Cost of delay
- The benefit lost for each period a decision is postponed.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A 30,000-dollar project saves 18,000 dollars a year. What does each month of delay cost?
Show answer
18,000 ÷ 12 = 1,500 dollars a month.
What are the seven parts of Ridgeline's executive brief?
Show answer
Situation, why it matters, recommendation, investment, return, risks and how they are handled, and the decision needed.
Why did Maya start the meeting by asking about the issue rather than presenting?
Show answer
To confirm what mattered most to the executive; Raymond's answer about the Manitoba dealer group changed the case.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.