
CHE-446 · Lesson 8 of 12 · 19 min
Operating costs and raw materials
Capital is spent once; operating costs are paid every year for the life of the plant. For a small chemical plant that buys its raw materials on the open market, the operating costs are usually the larger number over the plant's life, and the gap between the cost of making a tonne of product and the price it sells for is what pays back the capital. This lesson builds the cost of production for the ester line, the second main input to the investment decision. Malik, who runs the commercial side, works with Theo on it, because most of the numbers are prices rather than engineering.
Cost of production is usually presented in two parts. Variable costs scale with output: raw materials, utilities, catalyst, waste treatment, and any cost tied to emissions. Fixed costs do not change much with output: operating labour, supervision, maintenance, insurance, property tax and plant overhead. The distinction matters because a plant that runs at 70 % of capacity still pays nearly all its fixed costs, so its cost per tonne rises sharply as rates fall. Lesson 9 uses the 70 % first-year rate, and lesson 12 asks what happens if the market is weaker than expected.
Raw materials
For ethyl acetate made by esterification, raw materials dominate everything else. The balance from lesson 3 gives the consumption: about 1.585 t of acetic acid and 1.211 t of ethanol for every 2.30 t of ester, or about 0.69 t of acid and 0.53 t of ethanol per tonne of product. Those ratios come straight from the stoichiometry and the yields of 98.9 % on acid and 99.3 % on ethanol; a plant that lost more to waste or by-products would pay for it directly here. A one-point drop in acid yield would cost about 5 Canadian dollars per tonne of product, or about 0.1 million a year. That is why lesson 3 spent so long on recoveries.
Prices are the harder part. Acetic acid is a global commodity made mostly from methanol and carbon monoxide; its price follows methanol, natural gas and coal prices and the balance of supply in Asia, and it has swung widely over the past decade. Malik uses an illustrative contract price of 700 Canadian dollars per tonne delivered, with a range of about 550 to 900 for the sensitivity analysis. Ethanol is transferred from the existing plant, and the question of what price to use is a real one. Using the plant's cost of production would understate the cost, because every litre of ethanol turned into ester is a litre not sold as fuel. The correct price is the opportunity cost: what the ethanol would have earned as fuel, net of shipping and selling costs. Malik's figure, about 750 Canadian dollars per tonne, is the fuel price less the costs avoided by not shipping it.
The product price is set by the market, and the ester line is a price taker. Ethyl acetate sells to coatings, inks, adhesives, pharmaceuticals and food flavourings, and the price moves with acetic acid, because most of the world's ethyl acetate is made from it. That linkage is useful: when acid rises, the product price tends to follow, which narrows the swing in the margin. Malik uses 1,450 Canadian dollars per tonne for product delivered to customers within a day's trucking, a modest premium over imported product for being local and bio-based.
Malik also insists that every price in the estimate is stated in the same money. The economic model in lesson 9 works in real terms, in today's Canadian dollars, with no general inflation, so each price is a long-run average in today's money rather than this month's spot price or a forecast with inflation built in. Where Malik expects a price to move relative to general inflation, as with the carbon cost or a long-term contract with a fixed escalation clause, he shows the change explicitly. Mixing real and nominal prices in one model is a common way to make a marginal project look better than it is.
Utilities
Utilities are the second largest variable cost. The ester line uses steam for its reboilers, cooling water for its condensers and coolers, electricity for its pumps and instruments, and nitrogen for blanketing. Lesson 4 set the minimum steam at about 2.44 MW, which over 8,400 hours is about 74,000 GJ a year. The site's steam comes from natural gas boilers, and its cost is about 12 Canadian dollars per GJ, set by the gas price, the boiler efficiency and the cost of running the boiler house. Cooling water is cheap, about 0.30 per GJ removed, and electricity about 0.10 per kWh. The plant's total electrical load, including instruments, lighting and the small motors around the tanks, is about 80 kW.
Steam, at about 0.9 million a year, is small compared with raw materials but large compared with every other variable cost, and it is the one the engineers can change. Every 10 % of steam saved is worth about 90,000 Canadian dollars a year. That is the case for the MVR compressor from lesson 6.
There is a third piece in Ontario: the cost of the carbon dioxide from the boilers. The site is covered by Ontario's Emissions Performance Standards program, which prices the emissions of large industrial sites above a performance standard in line with the federal benchmark. That benchmark price was 110 per tonne of carbon dioxide equivalent in 2026 and was scheduled, when it was set in 2021, to reach 170 in 2030; the benchmark itself is under review. Under an output-based system like this, a facility pays only on emissions above its performance standard, not on all of them, so the cost is a fraction of the headline price. Theo estimates that the new steam load adds about 4,900 t of CO₂ a year and, as an illustrative assumption, that the site pays on about 20 % of it. At 110 per tonne that is about 0.11 million a year, rising to about 0.17 million at 170. These are small amounts, but they rise every year and are uncertain, so they appear as a separate line.
# Cost of production for the ethyl acetate line, with Ontario's output-based industrial carbon price (illustrative)
hours = 8400
ester_t = 2.300 * hours; acid_t = 1.585 * hours; eth_t = 1.211 * hours
price = {'ester': 1450, 'acid': 700, 'eth': 750}            # dollars per tonne, illustrative
fci = 34.8e6                                                 # fixed capital from lesson 7
steam_kw, cw_kw, power_kw = 2441, 1676, 80                    # from lessons 4 to 6
steam_GJ = steam_kw * 3.6e-3 * hours
var = {
  'acetic acid':          acid_t * price['acid'],
  'ethanol (transfer)':   eth_t * price['eth'],
  'steam at 12 per GJ':   steam_GJ * 12.0,
  'cooling water':        cw_kw * 3.6e-3 * hours * 0.30,
  'electricity at 0.10':  power_kw * hours * 0.10,
  'nitrogen':             15 * hours * 0.15,
  'catalyst and resin':   80e3,
  'wastewater treatment': 0.50 * hours * 4.0 + 25e3,
}
labour = 5.5 * 110e3                                         # one operator position around the clock
fixed = {
  'operating labour':     labour,
  'supervision and engineering (25 %)': 0.25 * labour,
  'maintenance (3 % of FCI)': 0.03 * fci,
  'insurance and property tax (1.5 %)': 0.015 * fci,
  'plant overhead (50 % of labour and maintenance)': 0.5 * (1.25 * labour + 0.03 * fci),
}
co2_t = steam_GJ / 0.85 * 0.0561                              # gas boiler at 85 %, 56.1 kg CO2 per GJ of gas
for year, cprice in [(2026, 110), (2030, 170)]:
    var[f'carbon cost {year} (pays on 20 % above benchmark)'] = 0.20 * co2_t * cprice
vc = sum(v for k, v in var.items() if '2030' not in k); fc = sum(fixed.values())
print(f"production {ester_t:,.0f} t/yr; steam {steam_GJ:,.0f} GJ/yr")
print("\nvariable costs                                       per year       per t ester")
for k, v in var.items(): print(f"  {k:50s} {v/1e6:7.3f} M   {v/ester_t:8.1f}")
print("fixed costs")
for k, v in fixed.items(): print(f"  {k:50s} {v/1e6:7.3f} M   {v/ester_t:8.1f}")
sales = ester_t * price['ester']
print(f"\nsales                                                {sales/1e6:7.2f} M   {price['ester']:8.1f}")
print(f"cash cost of production (using the first carbon line) {(vc+fc)/1e6:6.2f} M   {(vc+fc)/ester_t:8.1f}")
print(f"cash margin (EBITDA)                                 {(sales-vc-fc)/1e6:7.2f} M   {(sales-vc-fc)/ester_t:8.1f}")
print(f"raw materials share of cash cost {(var['acetic acid']+var['ethanol (transfer)'])/(vc+fc)*100:.0f} %")
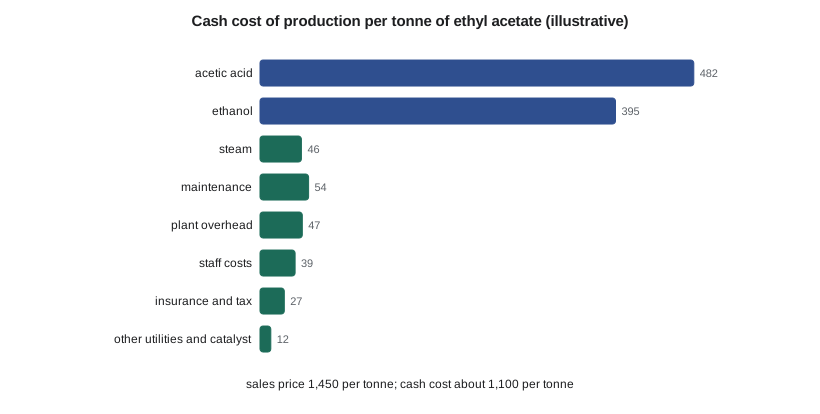
print(f"boiler CO2 {co2_t:,.0f} t/yr = {co2_t/ester_t:.3f} t per t ester")production 19,320 t/yr; steam 73,816 GJ/yr variable costs per year per t ester acetic acid 9.320 M 482.4 ethanol (transfer) 7.629 M 394.9 steam at 12 per GJ 0.886 M 45.8 cooling water 0.015 M 0.8 electricity at 0.10 0.067 M 3.5 nitrogen 0.019 M 1.0 catalyst and resin 0.080 M 4.1 wastewater treatment 0.042 M 2.2 carbon cost 2026 (pays on 20 % above benchmark) 0.107 M 5.5 carbon cost 2030 (pays on 20 % above benchmark) 0.166 M 8.6 fixed costs operating labour 0.605 M 31.3 supervision and engineering (25 %) 0.151 M 7.8 maintenance (3 % of FCI) 1.044 M 54.0 insurance and property tax (1.5 %) 0.522 M 27.0 plant overhead (50 % of labour and maintenance) 0.900 M 46.6 sales 28.01 M 1450.0 cash cost of production (using the first carbon line) 21.39 M 1107.0 cash margin (EBITDA) 6.63 M 343.0 raw materials share of cash cost 79 % boiler CO2 4,872 t/yr = 0.252 t per t ester
Fixed costs
Operating labour is estimated from the number of positions the plant needs around the clock. Carla's question from lesson 1 changed this line. The first draft assumed the existing crew could absorb the new line. Carla showed that the field operator who would cover the ester area already had a full round on the ethanol plant and that during an ethanol plant turnaround nobody would be free to watch the new tanks and loading. The final basis is one new operator position, covered around the clock. Filling one position for 8,760 hours a year with shifts, holidays, training and sick leave takes about 5.5 people, at an average loaded cost of about 110,000 Canadian dollars, or about 0.6 million a year. Supervision and engineering support add 25 % of that.
Maintenance is estimated as a percentage of fixed capital; 3 % a year is typical for a clean, low-pressure liquid process with few rotating machines. That gives about 1.04 million, the largest fixed cost. Insurance and property tax are taken at 1.5 % of fixed capital, about 0.52 million. Plant overhead, which covers the share of site services such as the laboratory, the safety department, the warehouse, the site management and the office, is taken at 50 % of labour and maintenance, about 0.9 million. These factors are rough, and Ingrid insists that each one is replaced by a site-specific figure from the ethanol plant's accounts wherever possible.
The result
At nameplate, the line sells about 19,300 t a year for about 28.0 million Canadian dollars. The cash cost of production is about 21.4 million, or about 1,107 per tonne, of which raw materials are 79 %. The cash margin before tax and depreciation, often called EBITDA, is about 6.6 million a year, about 343 per tonne. The carbon cost, at 5.5 per tonne in 2026, is less than 1 % of the cost.
Two things stand out. The first is how thin the margin is relative to the raw materials. A 5 % rise in acetic acid without a matching rise in the product price would remove about 0.47 million a year, 7 % of the margin. The second is how little the engineering choices move the total, once yield is high. Steam, maintenance and labour together are about 10 % of the cost. The project's economics depend mostly on the spread between product and raw material prices, which the engineers cannot control, and on the capital, which they can.
| Cost group | Per tonne | Share of cash cost |
|---|---|---|
| Raw materials | 877 | 79 % |
| Steam, cooling water, electricity | 50 | 5 % |
| Catalyst, nitrogen, waste, carbon | 13 | 1 % |
| Labour and supervision | 39 | 4 % |
| Maintenance, insurance, overhead | 128 | 12 % |
| Cash cost of production | 1,107 | 100 % |
The margin per tonne is the number Malik watches. At about 345 per tonne, the line earns a reasonable return only if it runs near nameplate and if the capital estimate holds. Lesson 9 turns this into cash flows; but Malik has already noted that the margin is sensitive enough to price that he wants a long-term contract for at least part of the acid supply, an idea that becomes option C in lesson 12.
Cost per tonne at reduced rates
At 70 % of nameplate in the first year, variable costs fall in proportion but fixed costs do not. The fixed costs total about 3.2 million a year, about 166 per tonne at nameplate; at 70 % they are about 238 per tonne. The cash margin per tonne falls by about 71, to about 270 to 280, and the annual margin falls from about 6.6 to 6.7 million to about 3.7 million. This is why start-up and the early months of selling are as important to the economics as the design itself, and why the market study from CHE-390 matters: a plant that takes three years to fill its order book instead of one loses several million in margin.
Common mistakes
MistakeValuing transferred ethanol at its production cost.
InsteadUse its opportunity cost: what it would earn as fuel.
MistakeIgnoring the link between acid and product prices.
InsteadBoth follow the acid market, which narrows the swing in margin.
MistakeTreating fixed costs as variable.
InsteadAt low rates, fixed costs per tonne rise sharply.
MistakeUsing generic percentages for maintenance and overhead without checking.
InsteadReplace each factor with site data where it exists.
MistakeAssuming a new line needs no extra operators.
InsteadCheck rounds, turnarounds and loading duties with operations.
Summary and key terms
- Raw materials are about 80 % of the cash cost; yield and price matter most.
- Steam is the largest utility at about 0.9 million a year; pumps are trivial.
- One operator position around the clock needs about 5.5 people.
- Maintenance, insurance and overhead are factored from capital and labour, then checked against site data.
- At nameplate the cash margin is about 6.6 to 6.7 million a year, about 345 per tonne.
- Variable cost
- A cost that scales with production.
- Fixed cost
- A cost that changes little with production.
- Opportunity cost
- The value of the best alternative use of a resource.
- Cash cost of production
- All cash costs of making the product, before depreciation and tax.
- EBITDA
- Earnings before interest, tax, depreciation and amortisation; here, the cash margin.
- Price taker
- A seller too small to influence the market price.
Practice problems
Work each problem on paper first, then reveal the answer to check.
How much acetic acid is used per tonne of ester?
Show answer
About 0.69 t.
Why is ethanol priced at its fuel value rather than its cost?
Show answer
Every tonne turned into ester is a tonne not sold as fuel.
What is the steam cost per year?
Show answer
About 0.89 million.
How many people fill one operator position around the clock?
Show answer
About 5.5.
What is the fixed cost per tonne at 70 % of nameplate?
Show answer
About 238.
Why does the product price tend to follow the acid price?
Show answer
Most ethyl acetate is made from acetic acid.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.