
ENGG-401 · Lesson 5 of 12 · 30 min
Annual worth analysis
Annual worth analysis expresses every alternative as an equivalent uniform amount per year over its life. Because many costs and revenues already occur annually, and because managers think naturally in yearly budgets, annual worth is often easier to interpret than present worth. It always gives the same decision as present worth for a given study period, and it has a particular advantage for alternatives with unequal lives. This lesson covers the annual worth method, capital recovery cost, equivalent uniform annual cost, comparing alternatives with unequal lives, levelized cost of energy and other per-unit costs, permanent investments, and the relationship between annual worth and the other methods.
The annual worth method
The annual worth (AW), sometimes called equivalent uniform annual worth (EUAW), of an alternative is the uniform annual amount over its life that is equivalent to all of its cash flows at the MARR. It can be found by converting the present worth into a uniform series:
In practice, it is usually easier to compute annual worth directly: uniform annual cash flows are already annual; first costs and salvage values are converted using capital recovery; gradients use \((A/G)\); and irregular cash flows are first discounted to present worth and then annualized. The decision rules mirror those of present worth: accept a single investment if \(AW \ge 0\); among mutually exclusive alternatives, choose the highest AW or lowest equivalent uniform annual cost (EUAC).
Capital recovery cost
The capital recovery (CR) cost is the equivalent annual cost of owning an asset: the uniform annual amount that recovers its first cost \(P\) with interest at the MARR, less the annual equivalent of its salvage value \(S\):
The second form shows the intuition: the depreciable amount \(P - S\) is recovered over the life with interest, and interest is also earned on the salvage amount, which remains invested until the end. Capital recovery is the annual worth of ownership, distinct from annual operating costs, and it lets engineers compare the annualized cost of buying equipment with leasing payments, maintenance contracts or other annual costs.
Worked problem
Annual worth of an investment
For the inspection system ($80,000 first cost, $22,000 annual savings, $10,000 salvage after 6 years, MARR 10 %), find the capital recovery cost and the annual worth.
Show solution
- \((A/P, 10\,\%, 6) = 0.22961\); \((A/F, 10\,\%, 6) = 0.12961\).
- \(CR = 80{,}000 \times 0.22961 - 10{,}000 \times 0.12961 = 18{,}369 - 1{,}296 = 17{,}073\).
- \(AW = 22{,}000 - 17{,}073 = 4{,}927\).
- Check: \(PW \times (A/P, 10\,\%, 6) = 21{,}460 \times 0.22961 = 4{,}927\).
Answer: Capital recovery cost $17,073 per year; annual worth +$4,927 per year, consistent with the present worth.
Equivalent uniform annual cost
When alternatives provide the same service and differ only in costs, it is convenient to express costs as positive numbers and compute the equivalent uniform annual cost (EUAC): capital recovery plus annual operating and maintenance costs plus the annual equivalents of any other costs. The alternative with the lowest EUAC is preferred. EUAC is widely used for equipment selection, fleet management, building systems and infrastructure maintenance.
Unequal lives made simple
Annual worth has a powerful property: if an alternative is repeated with identical cash flows, its annual worth is the same in every cycle. So when the least common multiple assumption is acceptable, alternatives with unequal lives can be compared simply by computing each one's annual worth over its own life, without building the LCM cash flow stream.
Worked problem
Unequal lives by annual worth
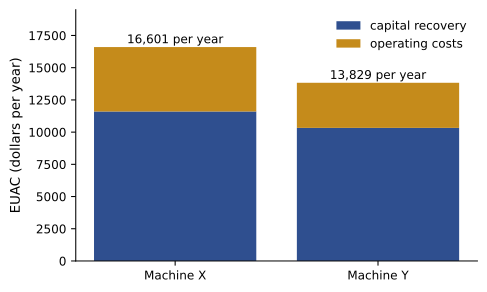
Revisit machines X (cost $30,000, annual costs $5,000, life 3 years, salvage $3,000) and Y (cost $45,000, annual costs $3,500, life 6 years, salvage $5,000) at a MARR of 12 %.
Show solution
- X: \(CR = 30{,}000 \times 0.41635 - 3{,}000 \times 0.29635 = 12{,}490 - 889 = 11{,}601\); EUAC = \(11{,}601 + 5{,}000 = 16{,}601\).
- Y: \(CR = 45{,}000 \times 0.24323 - 5{,}000 \times 0.12323 = 10{,}945 - 616 = 10{,}329\); EUAC = \(10{,}329 + 3{,}500 = 13{,}829\).
- Y has the lower EUAC, matching the LCM result in Lesson 4.
- Check: the LCM present costs (−68,255 and −56,857) annualized over 6 years at 12 % give the same EUACs.
Answer: Machine Y, with an EUAC of about $13,829 compared with $16,601 for X.
When the repeatability assumption is not appropriate, for example when replacements are expected to be cheaper due to technological change or the service is needed only for a limited time, a study period with explicit market values should be used instead, and annual worths should be computed over that period.
Levelized costs per unit
Annual worth extends naturally to cost per unit of output. Dividing the equivalent uniform annual cost of a facility by its annual output gives a levelized cost, widely used in the energy industry as the levelized cost of energy (LCOE), and in other industries as cost per metric ton, per liter, per unit produced or per square meter of floor area. LCOE allows generation technologies with very different cost structures, such as capital-intensive wind and solar with low operating costs versus gas turbines with lower capital costs and high fuel costs, to be compared on a common basis.
Worked problem
Levelized cost of a solar installation
A commercial rooftop solar system costs $1,200,000 installed, has annual operating and maintenance costs of $15,000, and produces 1,600,000 kWh per year for 25 years with negligible salvage. At a discount rate of 7 %, what is its levelized cost of energy, ignoring degradation and taxes?
Show solution
- \((A/P, 7\,\%, 25) = 0.08581\), so capital recovery is \(1{,}200{,}000 \times 0.08581 = 102{,}973\).
- Annual cost: \(102{,}973 + 15{,}000 = 117{,}973\).
- LCOE: \(117{,}973 / 1{,}600{,}000 = 0.0737\) per kWh.
Answer: About 7.4 cents per kWh, which can be compared with the price of purchased electricity.
Real LCOE analyses include panel degradation (often about 0.5 % per year), inverter replacement, taxes, incentives and financing structures. The LCOE also hides important differences: solar energy is produced in daytime and summer, while the value of electricity varies by hour and season, so LCOE comparisons should be complemented by analyses of value and system costs.
Permanent investments
For investments with indefinite lives, such as dams, tunnels or endowed facilities, the annual worth of the first cost is simply \(P \times i\), the interest forgone on the capital, because the principal is never recovered. Recurring costs every \(k\) years, such as a major overhaul, are converted to annual amounts with \((A/F, i, k)\). The annual worth of a permanent investment is therefore its first cost times \(i\), plus annual operating costs, plus the annual equivalents of periodic costs. This is equivalent to capitalized cost (Lesson 3) multiplied by \(i\).
Annual worth in budgeting and leasing
Annual worth connects engineering decisions to operating budgets. A facilities manager deciding between leasing equipment for $14,000 a year and buying it can compare the lease payment with the EUAC of owning, including capital recovery, maintenance and insurance. Energy managers express retrofits as annual savings net of capital recovery: an LED lighting retrofit costing $40,000 with annual savings of $9,000 over 10 years at 8 % has an annual worth of \(9{,}000 - 40{,}000 \times 0.14903 = 3{,}039\) per year, a figure that fits directly into an annual budget. Lease versus buy decisions must also consider taxes, since lease payments are usually deductible while ownership provides depreciation deductions (Lesson 9), and the terms of the lease, such as maintenance responsibilities and end-of-lease options.
| Method | Result | Decision rule | Best for |
|---|---|---|---|
| Present worth | Single amount at time 0 | Highest PW | Project value, portfolios |
| Future worth | Single amount at end | Highest FW | Value at a future date |
| Annual worth | Uniform amount per year | Highest AW or lowest EUAC | Unequal lives, budgets, unit costs |
| Rate of return | Interest rate | Incremental IRR ≥ MARR | Communicating returns (Lessons 6–7) |
| Benefit-cost ratio | Ratio | Incremental B/C ≥ 1 | Public projects (Lesson 8) |
Consistency of methods
Present worth, future worth and annual worth are different expressions of the same equivalence, so for a given study period and MARR they always rank alternatives identically. If a calculation shows otherwise, there is an error, typically inconsistent study periods or misplaced cash flows. Choosing among them is a matter of convenience and communication: present worth for total value, annual worth for unequal lives and budgets, future worth for values at a point in time. Rate of return and benefit-cost methods, covered next, give consistent results only when applied incrementally to mutually exclusive alternatives.
Annual worth of irregular cash flows
When cash flows are irregular, such as an overhaul in year 5 and a major refurbishment in year 12, annual worth is found by first computing present worth and then multiplying by the capital recovery factor for the study period. For recurring irregular costs, such as an overhaul every 5 years for the life of a permanent facility, each recurring amount can be converted to an annual equivalent using \\((A/F, i, 5)\\), because the pattern repeats in every 5-year cycle. This approach is common in pavement management, where resurfacing every 12 to 15 years and reconstruction every 30 to 40 years are annualized and compared across pavement types.
Worked problem
Annualizing a periodic overhaul
A compressor station needs a $120,000 overhaul every 5 years indefinitely. At 8 %, what is the equivalent annual cost of the overhauls?
Show solution
- \((A/F, 8\,\%, 5) = 0.08 / (1.08^5 - 1) = 0.17046\).
- Annual equivalent: \(120{,}000 \times 0.17046 = 20{,}455\).
Answer: About $20,455 per year.
Annual worth in competitive bidding
Contractors use annual worth to price equipment in bids. The hourly or daily ownership rate of a bulldozer or crane is its capital recovery cost plus insurance, storage and taxes, divided by the expected hours of use per year, plus operating costs per hour for fuel, repairs, tires and operator wages. Industry rental rate guides, such as those published by equipment cost data providers and provincial or state road agencies, are built on this logic. Underestimating ownership costs leads to bids that lose money; overestimating them loses work to competitors.
Equivalent annual cost of ownership for vehicles and equipment
Comparing the total cost of ownership of vehicles, such as an electric truck against a diesel truck, is a common annual worth application. The EUAC includes capital recovery, fuel or electricity, maintenance, insurance, tires, licenses and charging infrastructure, and sometimes the value of incentives or emissions. Electric vehicles usually have higher first costs and lower operating costs, so their advantage grows with annual distance driven and with fuel prices, and shrinks with higher interest rates. A break-even analysis of annual distance, at which the two options have equal EUAC, is a useful way to present the result to fleet managers.
Annual worth and inflation
When annual worth is computed in real terms, the result is a constant real annual amount, convenient for comparison with today's budgets. When computed in nominal terms, the uniform annual amount is constant in nominal dollars and therefore declines in purchasing power. Analysts should state which convention they use, especially for long-lived assets where the difference becomes significant.
As with present worth, annual worth results should be reported with a sensible number of significant figures and accompanied by the key assumptions, so that readers understand how precise the comparison really is and which estimates drive it.
Common mistakes
MistakeAnnualizing first cost without interest (dividing by n).
InsteadUse capital recovery with (A/P, i, n).
MistakeForgetting interest on salvage in capital recovery.
InsteadCR = (P − S)(A/P) + S i.
MistakeUsing annual worth for unequal lives when replacements will differ.
InsteadUse a study period with market values.
MistakeComparing LCOE without considering timing and value.
InsteadComplement LCOE with value and system analysis.
MistakeExpecting AW and PW to rank alternatives differently.
InsteadThey agree for the same period and MARR; check for errors.
Summary and key terms
- Annual worth converts all cash flows into an equivalent uniform annual amount.
- AW = PW (A/P, i, n) and gives the same decisions as PW.
- Capital recovery is the annual cost of ownership including interest.
- EUAC compares cost-only alternatives; lowest EUAC wins.
- With repeatable cycles, alternatives with unequal lives compare directly by AW.
- Levelized costs such as LCOE divide EUAC by annual output.
- Permanent investments have an annual cost of P × i plus recurring costs.
- Annual worth
- Equivalent uniform annual amount of all cash flows.
- EUAC
- Equivalent uniform annual cost.
- Capital recovery
- Annual cost of recovering an investment with interest.
- Repeatability assumption
- Identical replacement cycles for unequal lives.
- Levelized cost
- Annualized cost divided by annual output.
- LCOE
- Levelized cost of energy.
- Degradation
- Gradual decline in equipment output.
- Permanent investment
- Investment with an indefinite life.
- Lease versus buy
- Comparison of leasing payments with ownership costs.
- Unit cost
- Cost per unit of output or service.
Practice problems
Work each problem on paper first, then reveal the answer to check.
AW of an investment with PW $50,000 over 10 years at 8 %?
Show answer
About $7,451 per year.
Capital recovery of $100,000 with $20,000 salvage over 5 years at 10 %?
Show answer
About $23,104 per year.
Why can unequal lives be compared directly by AW?
Show answer
AW is the same in every repeated cycle.
When should a study period replace the repeatability assumption?
Show answer
When replacements differ or the need is limited.
What is LCOE?
Show answer
Annualized cost of a generator divided by annual energy.
Annual cost of a permanent $5 million investment at 4 %?
Show answer
$200,000 plus operating costs.
Annual equivalent of $60,000 every 15 years at 6 %?
Show answer
About $2,578 per year.
What does EUAC include?
Show answer
Capital recovery plus annual operating and other costs.
Do PW and AW ever rank alternatives differently?
Show answer
Not for the same period and MARR.
Name one limitation of LCOE.
Show answer
Ignores timing and value of output.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.