
ACCT-431 · Lesson 8 of 12 · 26 min
Completing the audit: subsequent events, representations and reporting judgments
By late February 2027, the work on Tamarack's components, controls and estimates is largely done. What remains is a sequence of procedures that can still change the financial statements and the auditor's report: searching for subsequent events, obtaining written representations, reading the other information that will accompany the statements, evaluating misstatements and disclosures in total, and deciding what the report will say. ACCT-331 introduced the auditor's report and key audit matters; this lesson focuses on the judgments that arise at the end of a complex engagement, using the Tamarack audit, whose report is planned for March 4, 2027.
Subsequent events
ASC 855, Subsequent Events, distinguishes recognized subsequent events, which provide additional evidence about conditions that existed at the balance sheet date, from nonrecognized subsequent events, which provide evidence about conditions that arose after that date. Recognized events are reflected in the financial statements; nonrecognized events are disclosed if necessary to keep the statements from being misleading. An SEC filer evaluates subsequent events through the date the financial statements are issued; other entities evaluate through the date they are available to be issued and disclose that date.
Under AU-C 560, the auditor performs procedures designed to identify events between the date of the financial statements and the date of the auditor's report that require adjustment or disclosure. Typical procedures include inquiring of management and legal counsel, reading minutes of board and audit committee meetings held after year end, reading the latest interim financial information and budgets, and examining significant transactions after year end, such as large credit notes, payments to settle provisions and new borrowings. Procedures should be performed as close as possible to the report date.
The program classifies the events found in Tamarack's subsequent events review, from January 1 to the March 4 report date, and decides what each requires.
# Subsequent events log from January 1 to the report date of March 4, 2027 (invented, thousands).
materiality = 1_400
events = [
    ("2027-01-12", "Customer owing 1,180 at year end files for bankruptcy; insolvency began in 2026", 1_180, True),
    ("2027-01-28", "Lawsuit filed in 2026 settled for 640; provision at year end was 400", 240, True),
    ("2027-02-09", "Fire destroys Snacks warehouse stock bought in 2027", 2_300, False),
    ("2027-02-17", "Board approves acquisition of a cold-storage business for 18,500", 18_500, False),
    ("2027-02-24", "Annual price list increase of 3% announced", 0, False),
    ("2027-03-02", "Mexican tax audit assessment relating to 2024, previously unknown", 310, True),
]
print(f"{'Date':<12}{'Type':<15}{'Amount':>8}  Action")
for date, text, amt, condition_existed in events:
    if condition_existed:
        kind = "recognized"
        action = "adjust the statements" if amt >= 70 else "adjustment trivial"
    else:
        kind = "nonrecognized"
        action = "disclose" if amt >= 0.5 * materiality else "no disclosure needed"
    print(f"{date:<12}{kind:<15}{amt:>8,}  {action}: {text}")
adj = sum(e[2] for e in events if e[3])
print(f"\nTotal recognized amounts: {adj:,} (compare with materiality {materiality:,})")Date Type Amount Action 2027-01-12 recognized 1,180 adjust the statements: Customer owing 1,180 at year end files for bankruptcy; insolvency began in 2026 2027-01-28 recognized 240 adjust the statements: Lawsuit filed in 2026 settled for 640; provision at year end was 400 2027-02-09 nonrecognized 2,300 disclose: Fire destroys Snacks warehouse stock bought in 2027 2027-02-17 nonrecognized 18,500 disclose: Board approves acquisition of a cold-storage business for 18,500 2027-02-24 nonrecognized 0 no disclosure needed: Annual price list increase of 3% announced 2027-03-02 recognized 310 adjust the statements: Mexican tax audit assessment relating to 2024, previously unknown Total recognized amounts: 1,730 (compare with materiality 1,400)
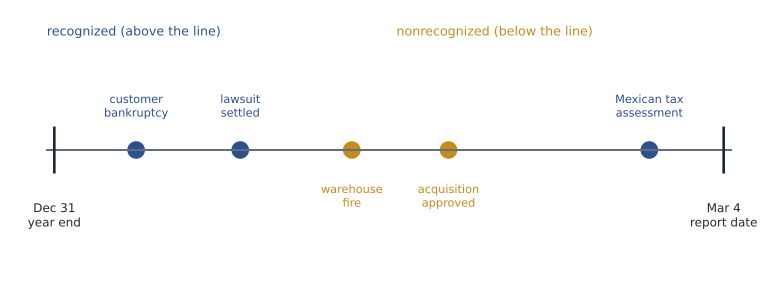
Three events reflect conditions that existed at year end and require adjustment. The customer bankruptcy in January confirms that its 1.18-million-dollar receivable was impaired at December 31, because the customer's financial difficulties began in 2026. The lawsuit settled for 640,000 dollars against a provision of 400,000 provides evidence of the obligation that existed at year end, so the provision is increased by 240,000. The Mexican tax assessment relates to 2024 and is newly discovered; the obligation existed at year end, so it is recognized. Together the three adjustments total 1.73 million, above group materiality, and management agrees to record them.
Two events reflect conditions arising after year end. The fire in February destroyed stock bought in 2027, so the loss belongs to 2027; at 2.3 million dollars before insurance recoveries, it is disclosed. The board's approval of an 18.5-million-dollar acquisition is disclosed as a significant commitment and future event. The price increase needs no disclosure. The program's disclosure threshold of half of materiality is a teaching simplification; in practice the test is whether the omission would make the statements misleading, considering qualitative factors.
Facts discovered after the report date
The auditor has no obligation to perform procedures after the report date, but if a fact becomes known that, had it been known at that date, might have caused the auditor to amend the report, the auditor discusses it with management and determines whether the financial statements need amendment. If they are amended before issue, the auditor extends subsequent events procedures to the new report date or dual-dates the report, keeping the original date except for the note describing the amendment, which carries a later date. If the statements have already been issued, management may need to recall or reissue them; if management refuses to take necessary action, the auditor takes steps to prevent reliance on the report, often with legal advice.
Written representations
AU-C 580 requires written representations from management with appropriate responsibilities, usually the CEO and CFO, that management has fulfilled its responsibility for preparing the financial statements, has provided all relevant information and access, and has recorded all transactions. Other standards require specific representations, for example on fraud, non-compliance with laws, related parties, subsequent events, estimates and going concern, and uncorrected misstatements, with a summary of the uncorrected items attached. Representations are dated as near as practicable to, but not after, the date of the auditor's report, and must cover all periods referred to in the report.
Written representations are necessary evidence but not sufficient on their own for any material matter. They do not replace procedures. If management refuses to provide a required representation, or the auditor concludes that representations are unreliable because of doubts about management's integrity, the auditor must consider the effect on the audit, which can include a disclaimer of opinion. For a group, the group engagement team also obtains representations from component management through component auditors, covering matters such as completeness of intercompany balances.
Other information
AU-C 720 requires the auditor of a private entity to read the other information in the annual report and consider material inconsistencies, with an Other Information section in the report. For issuers, PCAOB AS 2710 requires the auditor to read other information in documents containing audited financial statements, such as the Form 10-K, and consider whether it is materially inconsistent with the statements; the auditor's report does not include an other information section. For Tamarack, the team reads management's ICFR report and MD&A, which describe the goodwill material weakness, for consistency with its findings.
Evaluating misstatements and the overall presentation
At completion, the team accumulates all misstatements identified, from the group team, component auditors and specialists, and asks management to correct them. Uncorrected misstatements are evaluated individually and in total against materiality, including qualitative factors: whether a misstatement changes a loss into income, affects compliance with a covenant, hides a change in earnings trend, or relates to a matter of interest to regulators. For Tamarack, the covenant is a sensitive qualitative factor: an uncorrected misstatement of 300,000 dollars that would take the net debt to EBITDA ratio over 3.5 would be material even though it is well below 1.4 million.
The team also performs final analytical procedures on the statements as a whole, to see whether they are consistent with its understanding, and evaluates whether the statements, including disclosures, achieve fair presentation. Late changes, such as the adjustments from the subsequent events review and the goodwill impairment, need to be traced through to the final statements, the notes and the MD&A.
Key audit matters and critical audit matters
For issuers, PCAOB AS 3101 requires the auditor to communicate critical audit matters: matters arising from the audit that were communicated or required to be communicated to the audit committee, that relate to accounts or disclosures that are material to the financial statements, and that involved especially challenging, subjective or complex auditor judgment. For Tamarack, Hollis Ward identifies two CAMs: the goodwill impairment assessment for the snacks business and the trade promotion accruals. Each description identifies the matter, the principal considerations for determining that it is a CAM, how it was addressed and the relevant accounts or disclosures. Private entity auditors may communicate key audit matters under AU-C 701 if engaged to do so.
The two concepts overlap but are not identical. Both select the most difficult areas of the audit and explain them to readers. The international concept emphasizes the matters of most significance; the PCAOB concept is defined by three criteria and does not cap or target a number. In both, a matter that leads to a modified opinion or a material uncertainty related to going concern is reported in its own section, not as a key or critical audit matter.
Modified opinions and additional paragraphs
The decision to modify the opinion depends on two questions: is there a material misstatement, or an inability to obtain sufficient appropriate evidence; and, if so, are its possible effects pervasive? Pervasive effects are not confined to specific elements, accounts or items, or, if confined, represent a substantial proportion of the statements, or relate to disclosures fundamental to users' understanding.
| Nature of the matter | Material but not pervasive | Material and pervasive |
|---|---|---|
| Financial statements are materially misstated | Qualified opinion | Adverse opinion |
| Inability to obtain sufficient appropriate evidence | Qualified opinion | Disclaimer of opinion |
Separately, under AU-C 706, the auditor may include an emphasis of matter paragraph to draw attention to a matter appropriately presented or disclosed that is fundamental to users' understanding, such as a major catastrophe or significant subsequent event, and an other matter paragraph to communicate a matter relevant to users' understanding of the audit or the auditor's responsibilities. Neither modifies the opinion. For Tamarack, the team considers an emphasis of matter on the February fire but concludes it is not fundamental to users' understanding; the disclosure itself suffices.
Tamarack's report, dated March 4, 2027, therefore contains an unmodified opinion on the financial statements with two critical audit matters, and, because of the goodwill material weakness, an adverse opinion on internal control over financial reporting. The two opinions may be presented in a combined report or in separate reports that refer to each other.
Worked problem
Classifying a subsequent event
On February 20, 2027, Tamarack learns that inventory it sold in December 2026 was contaminated during production in November, and customers are returning it. Is this an event that requires adjustment?
Show solution
- The contamination occurred in November 2026, before year end.
- The returns provide evidence about a condition, defective inventory and a return obligation, that existed at December 31.
- The event therefore requires adjustment: revenue, receivables and a refund liability or provision are adjusted as at year end.
- Disclosure of the recall and its effect may also be needed if material.
Answer: Yes. It reflects a condition existing at year end and requires adjustment.
Common mistakes
MistakeTreating every material event after year end as requiring adjustment.
InsteadAdjust only for events that provide evidence of conditions existing at year end; disclose material events arising after.
MistakePerforming the subsequent events review weeks before the report date.
InsteadPerform procedures as close to the report date as practicable.
MistakeDating written representations after the auditor's report.
InsteadDate them as near as practicable to, but not after, the report date.
MistakeRelying on representations as sufficient evidence for a material matter.
InsteadRepresentations complement, but do not replace, other audit evidence.
MistakeIgnoring small misstatements that affect covenants.
InsteadConsider qualitative factors such as covenant compliance when evaluating materiality.
MistakeUsing an emphasis of matter paragraph instead of modifying the opinion.
InsteadAn emphasis of matter cannot substitute for a modified opinion when the statements are materially misstated.
Summary and key terms
- ASC 855 distinguishes recognized and nonrecognized subsequent events through the issuance date.
- Tamarack's adjusting events total 1.73 million; the fire and the acquisition are disclosed.
- Facts discovered after the report date may require amended statements, dual dating or steps to prevent reliance.
- Written representations are dated near, but not after, the report date and do not replace evidence.
- The auditor reads other information for material inconsistencies with the statements and audit knowledge.
- Uncorrected misstatements are evaluated with qualitative factors such as covenant effects.
- Critical audit matters meet three criteria under AS 3101; Tamarack has two, and an adverse ICFR opinion.
- Modified opinions depend on whether matters are material and whether their effects are pervasive.
- Recognized subsequent event
- An event after the balance sheet date that provides evidence of conditions existing at that date.
- Critical audit matter
- A matter communicated to the audit committee, relating to material accounts or disclosures, involving especially challenging, subjective or complex judgment.
- Dual dating
- Dating the auditor's report with the original date, except for a specific note dated later for an amendment.
- Written representation
- A written statement by management confirming matters or supporting other evidence.
- Other information
- Financial or non-financial information, other than the statements and report, included in the annual report.
- Pervasive
- Effects not confined to specific elements, or substantial, or fundamental to users' understanding.
- Emphasis of matter paragraph
- A paragraph drawing attention to a matter properly presented that is fundamental to users' understanding.
- Other matter paragraph
- A paragraph about a matter relevant to users' understanding of the audit or the auditor's responsibilities.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Give three procedures used to identify subsequent events.
Show answer
Inquiry of management and counsel; reading minutes; reading interim information; examining significant post-year-end transactions.
Why does the customer bankruptcy require adjustment?
Show answer
The customer's difficulties existed at year end, so the receivable was impaired at that date.
Change the fire loss in the program to 500 (thousand). What happens?
Show answer
It falls below the disclosure threshold in the program and is not flagged for disclosure, though qualitative factors should still be considered.
What is dual dating?
Show answer
Keeping the original report date except for a note describing a later amendment, which carries a later date.
Why are representations not sufficient evidence on their own?
Show answer
They are management's statements; material matters need corroborating evidence.
When might a 300,000-dollar uncorrected misstatement be material for Tamarack?
Show answer
If it would cause a covenant breach or affect another qualitative factor.
What are Tamarack's two critical audit matters?
Show answer
Goodwill impairment for snacks and trade promotion accruals.
When is an adverse opinion appropriate?
Show answer
When the statements are materially misstated and the effects are pervasive.
Can an emphasis of matter paragraph replace a qualified opinion?
Show answer
No; it does not modify the opinion and cannot substitute for one.
What should the auditor do if a fact discovered after issue would have changed the report and management refuses to act?
Show answer
Take steps to prevent reliance on the report, usually with legal advice.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.