
ACCT-431 · Lesson 7 of 12 · 27 min
Accounting estimates, going concern and the use of specialists
The hardest judgments in an audit rarely involve counting or vouching. They involve numbers that depend on the future: how much inventory will expire unsold, whether a business will generate enough cash to support its goodwill, whether the entity itself will survive the next year. ACCT-331 introduced estimates and going concern as part of completing the audit. This lesson treats them in depth, along with the use of specialists, whose work increasingly underpins the evidence for complex estimates.
The revised approach to estimates
AU-C 540, Auditing Accounting Estimates and Related Disclosures, requires the auditor to assess inherent risk for estimates by considering three factors: estimation uncertainty, complexity and subjectivity, along with susceptibility to management bias or fraud. The higher the inherent risk, the more persuasive the evidence needed. The auditor's response includes one or more of three approaches: obtaining evidence from events occurring up to the date of the auditor's report; testing how management made the estimate, including its method, significant assumptions and data; or developing the auditor's own point estimate or range.
| Factor | Questions | Tamarack examples |
|---|---|---|
| Estimation uncertainty | How precisely can the amount be measured? | Goodwill recoverable amount depends on long-range cash flows and a discount rate |
| Complexity | Is the method or data complex? | Trade promotion accruals combine thousands of customer agreements with sell-through data |
| Subjectivity | How much judgment is involved in selecting assumptions? | The terminal growth rate for the snacks business |
| Susceptibility to bias | Could management be motivated to choose a particular outcome? | Bonuses depend on group operating profit; covenant headroom is tight |
Testing how management made the estimate means looking at the method, which should be appropriate to the framework and applied consistently; the significant assumptions, which should be reasonable individually and together and consistent with each other and with other information; and the data, which should be relevant, reliable and accurately used. It also means considering whether management understood and addressed estimation uncertainty, for example by considering alternative assumptions and disclosing the range of reasonably possible outcomes.
Developing a range
When management's process is weak or its assumptions cannot be supported, the auditor may develop its own point estimate or range. The range should include only amounts that are supported by audit evidence and that the auditor considers reasonable; a range wide enough to include anything is not useful. If management's estimate falls outside the auditor's range, the misstatement is at least the difference between management's estimate and the nearest point of the range.
Tamarack's provision for slow-moving and expired packaged inventory is 1.85 million dollars. Management calculated it using rates applied to an aging of inventory, but the rates have not been updated for three years. The team builds its own range from the same aging, using low and high rates derived from actual write-offs in 2025 and 2026 and sell-through after year end, and performs a retrospective review of last year's estimate.
# Accounting estimate: provision for slow-moving and expired packaged inventory (thousands).
# The auditor builds an independent range from the aging and recent sell-through (invented data).
aging = {"0-90 days": 31_400, "91-180 days": 5_200, "181-365 days": 2_350, "Over 365 days": 980}
low_rates = {"0-90 days": 0.00, "91-180 days": 0.10, "181-365 days": 0.40, "Over 365 days": 0.90}
high_rates = {"0-90 days": 0.01, "91-180 days": 0.15, "181-365 days": 0.55, "Over 365 days": 1.00}
management = 1_850

low = sum(aging[b] * low_rates[b] for b in aging)
high = sum(aging[b] * high_rates[b] for b in aging)
print(f"Auditor's range: {low:,.0f} to {high:,.0f}   management's estimate: {management:,.0f}")
if management < low:
    print(f"Estimate below the range: misstatement at least {low - management:,.0f} (understated provision)")
elif management > high:
    print(f"Estimate above the range: misstatement at least {management - high:,.0f}")
else:
    print("Estimate within the range: no misstatement identified, consider indicators of bias")
# Retrospective review: last year's provision against what actually happened
prior_estimate, prior_actual_writeoffs = 1_600, 2_140
print(f"Prior-year provision {prior_estimate:,} vs write-offs {prior_actual_writeoffs:,}: "
f"shortfall {prior_actual_writeoffs - prior_estimate:,} ({(prior_actual_writeoffs/prior_estimate - 1):.0%})")Auditor's range: 2,342 to 3,366 management's estimate: 1,850 Estimate below the range: misstatement at least 492 (understated provision) Prior-year provision 1,600 vs write-offs 2,140: shortfall 540 (34%)
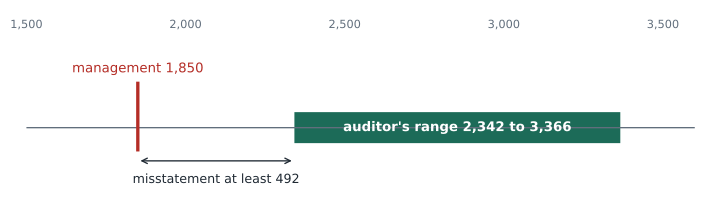
The auditor's range runs from about 2.34 million to 3.37 million dollars. Management's estimate is below the range, so the provision is understated by at least 492,000 dollars, which is accumulated as a misstatement. The retrospective review supports the conclusion: last year's provision of 1.6 million fell short of actual write-offs by 34 percent, which suggests the old rates are too low. A retrospective review is not intended to second-guess judgments that were reasonable when made; its purpose is to evaluate the effectiveness of management's estimation process and to identify possible bias. The team also considers whether the direction of all estimate differences, here consistently in favor of higher profit, is an indicator of possible management bias, a matter it must evaluate at the overall level as well as estimate by estimate.
Going concern: responsibilities
Under US GAAP (ASC 205-40), management must evaluate whether conditions or events raise substantial doubt about the entity's ability to continue as a going concern within one year after the date the financial statements are issued, or are available to be issued, and disclose when substantial doubt exists, including whether management's plans alleviate it. AU-C 570, and for issuers PCAOB AS 2415, require the auditor to evaluate whether there is substantial doubt about the entity's ability to continue as a going concern for a reasonable period. PCAOB AS 2415 refers to a period not exceeding one year beyond the date of the financial statements; the AICPA standard aligns its period with the framework, which for US GAAP means one year after issuance.
The auditor considers events or conditions that may cast significant doubt on going concern: financial indicators, such as recurring losses, negative operating cash flows, breaches or near-breaches of covenants and the inability to refinance maturing debt; operating indicators, such as the loss of a major customer or key supplier, labor difficulties and shortages of important supplies; and other indicators, such as pending litigation, changes in law and uninsured catastrophes. When such events or conditions exist, the auditor performs additional procedures, including evaluating management's plans for future actions and the feasibility of those plans, and the cash flow forecasts on which they depend.
Testing a cash flow forecast
Tamarack is profitable, but its debt is high after the snacks acquisition. Its term loan has a covenant requiring net debt to EBITDA of no more than 3.5 times, and its revolving credit facility of 25 million dollars is 9 million drawn. Management's 2027 cash flow forecast shows cash staying positive with headroom on the revolver. The team tests the forecast's key assumptions against history, budgets and post-year-end results, and performs a stress test to see how much the assumptions would need to change to create a problem.
# Going concern: stress testing the group's monthly cash forecast for 2027 (invented, thousands).
base_receipts = [33_500, 32_800, 34_900, 35_600, 36_200, 37_000, 36_400, 35_900, 35_100, 34_600, 33_800, 36_800]
base_payments = [33_900, 33_600, 33_700, 34_800, 35_300, 35_900, 35_800, 35_200, 34_700, 34_300, 33_900, 34_900]
opening_cash, revolver_limit, revolver_drawn = 6_200, 25_000, 9_000
debt_service = {3: 2_400, 6: 2_400, 9: 2_400, 12: 2_400}    # quarterly term loan payments
annual_ebitda, net_debt = 46_000, 132_000                    # covenant: net debt / EBITDA <= 3.5

def run(receipt_factor=1.0, payment_factor=1.0, delay_month=None, ebitda_cut=0.0):
    cash, low, low_m = opening_cash, opening_cash, 0
    for m in range(12):
        r = base_receipts[m] * receipt_factor
        if delay_month is not None and m == delay_month: r -= 9_000      # large customer pays two months late
        if delay_month is not None and m == delay_month + 2: r += 9_000
        cash += r - base_payments[m] * payment_factor - debt_service.get(m + 1, 0)
        if cash < low: low, low_m = cash, m + 1
    headroom = revolver_limit - revolver_drawn + low
    ratio = net_debt / (annual_ebitda * (1 - ebitda_cut))
    return low, low_m, headroom, ratio

scenarios = {"Base forecast": run(),
             "Sales volume -5%": run(receipt_factor=0.95, payment_factor=0.965, ebitda_cut=0.15),
             "Volume -5% and late customer": run(0.95, 0.965, delay_month=2, ebitda_cut=0.15),
             "Severe: volume -10%": run(0.90, 0.935, delay_month=2, ebitda_cut=0.30)}
print(f"{'Scenario':<30}{'Lowest cash':>12}{'Month':>6}{'Liquidity':>11}{'Net debt/EBITDA':>17}")
for name, (low, m, head, ratio) in scenarios.items():
    flag = "  covenant breach" if ratio > 3.5 else ""
print(f"{name:<30}{low:>12,.0f}{m:>6}{head:>11,.0f}{ratio:>17.2f}{flag}")Scenario Lowest cash Month Liquidity Net debt/EBITDA Base forecast 3,200 12 19,200 2.87 Sales volume -5% -3,370 12 12,630 3.38 Volume -5% and late customer -6,718 3 9,282 3.38 Severe: volume -10% -12,020 12 3,980 4.10 covenant breach
Under the base forecast, cash bottoms out at 3.2 million in December and liquidity, the undrawn revolver plus cash, stays above 19 million, with the covenant ratio at 2.87. A 5 percent fall in sales volume pushes cash below zero, requiring revolver draws, but liquidity of about 12.6 million remains and the covenant ratio of 3.38 is still inside the limit. Adding a large customer that pays two months late, as happened in 2025, creates a low point in March but does not exhaust liquidity. Only the severe scenario, a 10 percent volume decline, breaches the covenant and leaves less than 4 million of liquidity.
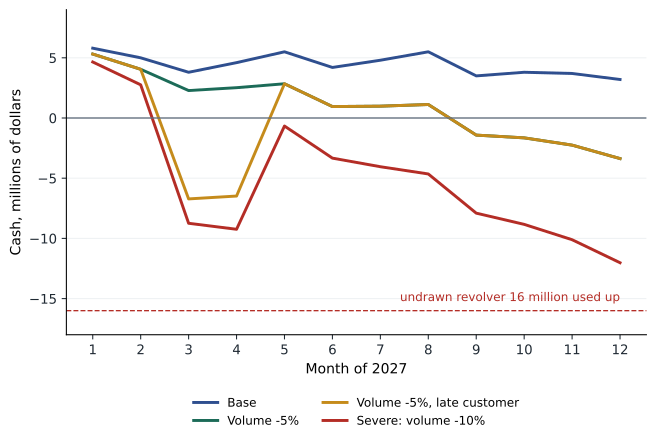
The question is whether the severe scenario is plausible within the assessment period. The team considers that volumes fell 3 percent in 2025, that the largest customer represents 14 percent of sales, and that the lenders granted a covenant waiver once before. It concludes that no material uncertainty exists, because the plausible downside scenarios remain within the covenant and liquidity limits, but it recommends that management disclose the covenant and its headroom, and it reports the analysis to the audit committee. If the severe scenario had been plausible, the team would have evaluated management's mitigating plans, such as cost reductions or a covenant amendment, including whether they are feasible and within management's control, and would have considered whether a material uncertainty existed.
| Conclusion | Effect on the auditor's report |
|---|---|
| Going concern basis appropriate; no material uncertainty | Unmodified opinion; no going concern paragraph |
| Going concern basis appropriate; material uncertainty adequately disclosed | Unmodified opinion with a going concern emphasis paragraph (substantial doubt) |
| Material uncertainty not adequately disclosed | Qualified or adverse opinion |
| Going concern basis inappropriate | Adverse opinion, unless a different basis of accounting is used and disclosed |
Using the work of specialists
Complex estimates often require expertise outside accounting and auditing: valuation of goodwill or financial instruments, actuarial calculations for pensions, engineering assessments of reserves, legal interpretation, environmental remediation estimates. Two kinds of specialist need to be distinguished. A management's specialist is engaged or employed by the entity to help prepare the financial statements, such as the valuation adviser Tamarack hired for its goodwill impairment test. An auditor's specialist, or auditor's expert, is engaged or employed by the auditor to help obtain evidence, such as Hollis Ward's internal valuation group.
For issuer audits, the PCAOB amended its standards on using the work of specialists, effective for audits of fiscal years ending on or after December 15, 2020. AS 1105 Appendix A now governs the use of a company's specialist as evidence, requiring the auditor to evaluate the specialist's knowledge, skill, ability and relationship to the company, and to test or evaluate the data, significant assumptions and methods used; AS 1210 governs an auditor-engaged specialist, and AS 1201 Appendix C an auditor-employed specialist. For private entity audits, AU-C 620 covers auditor's specialists and AU-C 500 covers management's specialists, in terms similar to the international standards.
Objectivity is the point most often overlooked. A management's specialist who is paid by the entity, or whose fee depends on the outcome, may be competent but not objective. The auditor's evaluation of the specialist's work must be more rigorous where objectivity is weaker. For Tamarack, the team's valuation specialists review the management specialist's discounted cash flow model, test the discount rate against market data, and compare the terminal growth rate with long-term inflation and industry forecasts; they conclude that the discount rate is too low by 0.8 percentage points, which, together with the weakness in management's review identified in lesson 6, leads to further discussion with management and an impairment adjustment.
Disclosures and documentation
Estimates and going concern judgments are only as good as their disclosure. The auditor evaluates whether disclosures describe the estimation uncertainty, the key assumptions and, where required by the framework, the sensitivity of the amounts to changes in assumptions. For goodwill under IAS 36 or ASC 350, that includes the key assumptions on which recoverable amount or fair value is based. Documentation should show how the team evaluated management's methods, assumptions and data, the range or point estimate developed, how bias was considered, and the basis for the conclusions, so that an experienced auditor with no connection to the engagement can understand them.
Worked problem
A point estimate outside the range
Management's warranty provision is 900,000 dollars. The auditor's supportable range is 1.0 million to 1.3 million. What is the misstatement, and what else should the auditor consider?
Show solution
- Management's estimate is below the range.
- The misstatement is at least the difference to the nearest point of the range: 1.0 million minus 0.9 million.
- The auditor accumulates a misstatement of 100,000 dollars.
- The auditor also considers whether this and other estimates indicate possible management bias.
Answer: A misstatement of at least 100,000 dollars, plus an evaluation of possible bias across estimates.
Common mistakes
MistakeUsing the auditor's point estimate as the misstatement when management's estimate is within a supportable range.
InsteadWhen management's estimate is within the range, no misstatement arises from the estimate itself; consider bias.
MistakeBuilding a range wide enough to include any figure.
InsteadInclude only amounts supported by evidence and considered reasonable.
MistakeTreating a retrospective review as a test of hindsight.
InsteadUse it to evaluate the estimation process and indicators of bias, not to fault reasonable past judgments.
MistakeAccepting a cash flow forecast without stress testing key assumptions.
InsteadTest assumptions against history and evidence, and evaluate how much change would cause a problem.
MistakeRelying on a management's specialist without evaluating objectivity.
InsteadEvaluate competence, capabilities and objectivity, and test the specialist's data, assumptions and methods.
MistakeLooking at each estimate in isolation.
InsteadConsider the direction of estimate differences in total as a possible indicator of bias.
Summary and key terms
- AU-C 540 assesses inherent risk using estimation uncertainty, complexity, subjectivity and susceptibility to bias.
- Responses include subsequent events, testing management's process, and developing the auditor's own estimate or range.
- A misstatement is at least the difference between management's estimate and the nearest point of the auditor's range.
- Tamarack's inventory provision was understated by at least 492,000 dollars.
- ASC 205-40 looks one year beyond issuance; PCAOB AS 2415 refers to a reasonable period not exceeding one year beyond the statement date.
- Stress tests show how far assumptions must move before liquidity or covenants fail.
- Auditors evaluate the competence, capabilities and objectivity of both management's and auditor's specialists.
- Disclosures of estimation uncertainty and key assumptions are part of the evidence evaluated.
- Substantial doubt
- Conditions or events that make it probable the entity will be unable to meet obligations within one year after issuance.
- Estimation uncertainty
- Susceptibility of an estimate to an inherent lack of precision in its measurement.
- Auditor's range
- A range of amounts supported by evidence that the auditor considers reasonable.
- Retrospective review
- Comparison of prior estimates with actual outcomes to evaluate the estimation process.
- Management bias
- A lack of neutrality by management in preparing information.
- Stress test
- An analysis of how changes in key assumptions affect outcomes such as liquidity.
- Management's specialist
- An individual or organization with expertise outside accounting used by the entity in preparing the statements.
- Auditor's specialist
- An individual or organization with expertise outside accounting and auditing used by the auditor to obtain evidence.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Name the three responses to the risks of misstatement in an estimate.
Show answer
Evidence from events up to the report date; testing how management made the estimate; developing the auditor's own estimate or range.
What is the auditor's range for the inventory provision?
Show answer
About 2.34 million to 3.37 million dollars.
Change management's estimate to 2,500 in the program. What happens?
Show answer
It falls within the range, so no misstatement is identified, though bias should still be considered.
What does the retrospective review show?
Show answer
Last year's provision fell short of write-offs by 540,000, or 34 percent, suggesting outdated rates.
Under which scenario does Tamarack breach its covenant?
Show answer
The severe scenario, with a 10 percent volume decline.
Change the covenant limit to 3.25 in your head. Which scenarios would breach it?
Show answer
The two 5 percent volume scenarios (3.38) and the severe scenario (4.10).
Why did the team conclude there was no material uncertainty?
Show answer
Plausible downside scenarios stayed within liquidity and covenant limits.
Distinguish a management's specialist from an auditor's specialist.
Show answer
The first is used by the entity to prepare the statements; the second by the auditor to obtain evidence.
Why does objectivity matter when evaluating a management's specialist?
Show answer
A specialist paid by the entity may be influenced; weaker objectivity requires more rigorous evaluation of the work.
What should estimate disclosures include?
Show answer
Estimation uncertainty, key assumptions and, where required, sensitivity to changes in assumptions.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.