
ACCT-101 · Lesson 1 of 12 · 34 min
Accounting and its users
Accounting is often called the language of business. Owners use it to see whether their business is making money, lenders use it to decide whether to lend, investors use it to compare companies, governments use it to collect tax, and managers use it every day to decide what to make, what to charge and what to cut. Like any language, accounting has a vocabulary, a grammar and conventions that make it possible for people who have never met to understand each other. This course teaches that language from the beginning: how business events are recorded, how the records are summarized in financial statements, and how those statements are read.
This first lesson sets the scene. It explains what accounting is for, who uses accounting information and what they need, how financial accounting differs from managerial accounting, who sets the rules, and what the accounting profession looks like. Later lessons build the technical skills: the accounting equation in lesson 2, double-entry bookkeeping in lessons 3 and 4, the adjusting process in lessons 5 and 6, the financial statements in lesson 7, merchandising and inventory in lessons 8 and 9, cash and receivables in lessons 10 and 11, and cash flows and analysis in lesson 12. Throughout, numbers are illustrative and invented unless a source is named, and nothing here is accounting or tax advice for a particular business.
What accounting does
Accounting is the process of identifying, measuring, recording and communicating economic information about an organization so that people can make decisions. Each of those four verbs matters. Identifying means deciding which events count: a sale to a customer is an accounting event, but hiring a promising new employee is not, because nothing has yet been exchanged. Measuring means attaching a number, usually in dollars, to the event. Recording means entering the event in a systematic way so that nothing is lost and everything can be traced. Communicating means summarizing thousands of recorded events into a small number of reports that a busy reader can understand.
Bookkeeping is the recording part of this process: entering transactions, keeping the ledger in balance, and producing the raw numbers. Accounting is broader. It includes designing the system, choosing how to measure difficult items, interpreting the results, and making sure the reports are reliable. Today software does most of the arithmetic of bookkeeping, but someone still has to decide what each transaction means and whether the software has been told the right thing. That judgment is what this course aims to build.
The users of accounting information
Accounting information has two broad groups of users. Internal users work inside the organization: owners who run the business, managers, supervisors and employees. They can ask for whatever reports they need, in whatever format, as often as they like. External users are outside the organization: investors who own or might buy shares, lenders such as banks and bondholders, suppliers who sell on credit, customers, tax authorities, regulators, labor unions and the public. They cannot demand custom reports, so they rely on general-purpose financial statements prepared under agreed rules.
| User | Typical question | Information they rely on |
|---|---|---|
| Owner of a small business | Am I making money, and can I pay myself more? | Income statement, cash balance, owner's equity |
| Manager | Which product line is most profitable? Can we afford to hire? | Internal reports, budgets, cost data (ACCT-102) |
| Investor | Will this company grow its earnings and dividends? | Audited financial statements, notes, management discussion |
| Lender | Will the borrower repay principal and interest on time? | Cash flows, debt ratios, assets available as security |
| Supplier | Should we sell to this customer on 30-day credit? | Liquidity ratios, payment history, credit reports |
| Internal Revenue Service | How much tax is owed? | Taxable income computed from accounting records under tax law |
| Employees and unions | Can the company afford higher wages? Is it stable? | Profitability, cash position, pension information |
The common thread is clear: every user is trying to predict the future, especially future cash flows, using information about the past. A lender wants to know whether the borrower will have the cash to repay. An investor wants to estimate future earnings. A manager wants to know what will happen if prices rise by 5 percent. Accounting cannot see the future, but a clear, honest record of what has happened is the best starting point anyone has.
Financial accounting and managerial accounting
Financial accounting produces general-purpose reports for external users. Its reports follow published standards, cover the whole organization, are usually prepared at least once a year (quarterly for public companies), and for many organizations are reviewed or audited by an independent accountant. Managerial accounting produces reports for internal decision makers. It has no required format, can focus on a single product, department or customer, can use estimates and forecasts freely, and is judged by whether it helps managers decide well. This course is about financial accounting; ACCT-102 Introductory Managerial Accounting covers the internal side, including cost behavior, budgeting and variance analysis.
| Feature | Financial accounting | Managerial accounting |
|---|---|---|
| Main users | External: investors, lenders, regulators | Internal: managers and employees |
| Rules | US GAAP for most companies | None required; whatever helps decisions |
| Scope | The whole entity | Any segment: product, plant, project |
| Time focus | Mostly historical, period by period | Historical and forward-looking |
| Frequency | Annual, quarterly for public companies | As often as needed, even daily |
| Verification | Often audited or reviewed | Usually not audited |
Forms of business organization
The rules of accounting are the same in spirit for every business, but the equity section of the balance sheet looks different depending on how the business is organized. A sole proprietorship is owned by one person; the business is not legally separate from the owner, but accounting still treats it as a separate entity so that the owner's personal spending does not get mixed into the business records. A partnership is owned by two or more partners who share profits. A corporation is a separate legal person owned by shareholders; it can sign contracts, sue and be sued, and it continues even if the shareholders change.
In the United States, most small businesses start as sole proprietorships, limited liability companies (LLCs) or corporations formed under state law, often Delaware's. The stockholders' equity of a corporation is split between contributed capital, usually shown as common stock and additional paid-in capital, and retained earnings, which are profits kept in the business. A sole proprietorship shows a single capital account for the owner, with withdrawals recorded separately. This course uses a small corporation for its main running example, because that is what you will see in most published statements, and points out where a proprietorship differs.
Who sets the rules
Financial statements are only useful to outsiders if everyone follows the same rules. In the United States, the Financial Accounting Standards Board (FASB), a private body, sets generally accepted accounting principles (US GAAP), organized in the FASB Accounting Standards Codification (ASC). The Securities and Exchange Commission (SEC) has legal authority over financial reporting by public companies and recognizes FASB as the standard setter; public companies must file audited statements with the SEC. Private companies also commonly use US GAAP, with some simpler alternatives developed through the Private Company Council, because banks and investors ask for it. State and local governments follow standards from the Governmental Accounting Standards Board (GASB). Most other countries use International Financial Reporting Standards (IFRS) from the International Accounting Standards Board (IASB), and foreign companies listed in the US may file IFRS statements without reconciling to US GAAP.
IFRS and US GAAP have converged on many topics, such as revenue recognition, but differences remain. For an introductory course the most visible ones are terminology and a few choices: US GAAP permits the last-in, first-out (LIFO) inventory method that IFRS prohibits, and IFRS allows some assets to be revalued to fair value where US GAAP requires historical cost. The course mentions these differences where they come up so that you can read statements from Canada, Europe and other IFRS countries too.
| Item | United States | International |
|---|---|---|
| Standard setter | Financial Accounting Standards Board (FASB) | International Accounting Standards Board (IASB) |
| Main frameworks | US GAAP (ASC); GASB for governments | IFRS, IFRS for SMEs |
| Public company regulator | Securities and Exchange Commission (SEC) | National regulators |
| Auditing standards | PCAOB standards for public companies; AICPA standards for private | International Standards on Auditing (ISA) |
| Professional body | AICPA and state boards of accountancy | IFAC member bodies |
The conceptual framework in brief
Standard setters work from a conceptual framework, a statement of the purpose of financial reporting and the qualities that make information useful. You will meet it in depth in ACCT-211, but its main ideas guide everything in this course. The objective of general-purpose financial reporting is to provide information that helps investors, lenders and other creditors make decisions about providing resources to the entity. To be useful, information must be relevant, meaning capable of making a difference to decisions, and must faithfully represent what it claims to represent, meaning complete, neutral and free from error. Comparability, verifiability, timeliness and understandability enhance usefulness, and the benefits of information should justify the cost of producing it.
Several assumptions underlie the statements. The economic entity assumption says the business is accounted for separately from its owners and from other businesses. The going concern assumption says the business will continue operating for the foreseeable future, which is why equipment is reported at cost less depreciation rather than at what it would fetch in a forced sale. The monetary unit assumption says transactions are measured in a stable currency. The periodicity assumption says the life of a business can be divided into periods such as months and years. And the accrual basis says revenues are recorded when earned and expenses when incurred, not merely when cash changes hands, an idea you will use constantly from lesson 5 onward.
| Principle or assumption | Meaning | Example |
|---|---|---|
| Economic entity | Keep business and owner records separate | The owner's family groceries are not a business expense |
| Going concern | Assume the business continues | Equipment carried at cost less depreciation, not liquidation value |
| Monetary unit | Measure in a stable currency | Records kept in dollars; general inflation ignored |
| Periodicity | Report for defined periods | Monthly management statements, annual financial statements |
| Historical cost | Record assets at what was paid | Land bought for $200,000 stays at $200,000 even if its value rises |
| Accrual basis | Record revenue when earned, expenses when incurred | December repairs billed in January are a December expense |
Worked problem
Applying the entity assumption
Maya owns Birchwood Bikes, a small bicycle shop. In one week the business account pays for $2,400 of bicycle parts, $600 of shop rent and $180 for Maya's personal cell phone plan, which she also uses to take customer calls about 20 percent of the time.
Show solution
- The parts and rent relate only to the business, so both are business transactions.
- The phone plan is mainly personal. Under the entity assumption, the personal portion is not a business expense; it is treated as a withdrawal of the owner's money (or, for a corporation, as an amount owed by the shareholder or as extra pay).
- A reasonable approach records 20 % of $180 = $36 as a business telephone expense and $144 as a personal amount, with documentation of how the split was estimated.
- Tax rules on mixed-use expenses are separate from accounting rules; this course does not give tax advice.
Answer: Business costs are $2,400 + $600 + $36 = $3,036; the $144 personal portion is not a business expense.
The accounting profession
Accountants work in public accounting firms, providing audit, assurance, tax and advisory services; in industry, as controllers, analysts and chief financial officers; in government and not-for-profit organizations; and in education. In the United States, the Certified Public Accountant (CPA) license is granted by each state's board of accountancy. Candidates pass the four-part Uniform CPA Examination, meet education and experience rules and an ethics requirement. For decades most states required 150 semester hours of education. Since the model law was amended in 2024, a growing majority of states also accept a bachelor's degree (about 120 hours) plus two years of experience; check your state board for current rules. Bookkeepers, enrolled agents for tax and certified management accountants work alongside CPAs.
Whatever the designation, professional accountants are bound by codes of ethics built on integrity, objectivity, professional competence and due care, confidentiality and professional behavior. Ethics is not an add-on to accounting. Financial statements are only valuable if readers can trust them, and the history of business is full of cases where people bent the numbers to hide losses or inflate profits. BUS-310 discusses fraud and governance; in this course, ethical questions appear wherever there is a temptation to record something in a way that flatters the business.
| Code | Core principles | Applies to |
|---|---|---|
| AICPA Code of Professional Conduct | Integrity, objectivity, due care, independence for attest work, public interest | AICPA members; adopted by many state boards |
| State board rules | Licensing and conduct rules backed by law | Licensed CPAs in that state |
| IESBA International Code | Integrity, objectivity, competence, confidentiality, professional behavior | Basis for many national codes |
Worked problem
An ethical pressure point
On 30 December, the owner of a small company asks the bookkeeper to record a $25,000 sale that the customer has only promised to place in January, because the bank will review the year-end statements before renewing a loan.
Show solution
- Under the accrual basis, revenue is recorded when it is earned. No goods have been delivered and no service performed, so no revenue has been earned in December.
- Recording the sale would overstate revenue, receivables and profit, and would mislead the bank, a user who relies on the statements.
- The bookkeeper should decline, explain the rule, and suggest honest alternatives such as giving the bank the signed order as supporting information for the January forecast.
- If pressured further, the bookkeeper should escalate to an accountant or advisor; professional codes forbid association with misleading information.
Answer: Do not record the sale in December. It belongs in the period in which it is earned.
Accounting systems today
Small businesses commonly use cloud accounting software that connects to bank feeds, sales systems and payroll services. Larger organizations use enterprise resource planning (ERP) systems that record accounting entries automatically as sales are shipped or invoices approved. Automation changes who types the entries, not the logic underneath. Every system still records debits and credits, keeps a general ledger and produces a trial balance. When something goes wrong, such as a duplicated bank feed, a misclassified expense or a sale recorded in the wrong month, the person who understands the underlying logic is the one who can find and fix it. ACCT-240 Accounting Information Systems covers system design and internal controls in depth.
Throughout the course, short Python programs show the logic in a form you can run and change. You do not need to be a programmer; the code is short and commented. The program below is the smallest possible illustration of the accounting equation, which lesson 2 develops: whatever happens, the resources of the business equal the claims on them.
# The accounting equation: assets = liabilities + equity
# Birchwood Bikes starts business (illustrative numbers)
assets = 0
liabilities = 0
equity = 0

# Owner invests $50,000 cash in exchange for shares
assets += 50000; equity += 50000
# Business borrows $20,000 from the bank
assets += 20000; liabilities += 20000
# Business buys $15,000 of equipment for cash (one asset for another)
assets += 15000 - 15000

print(f"Assets      {assets:>8,}")
print(f"Liabilities {liabilities:>8,}")
print(f"Equity      {equity:>8,}")
print("Balanced?", assets == liabilities + equity)Assets 70,000 Liabilities 20,000 Equity 50,000 Balanced? True
Each transaction kept the equation in balance. That is not luck; it is built into the system, and it is the reason accountants can find many errors simply by checking whether things still add up.
The four financial statements
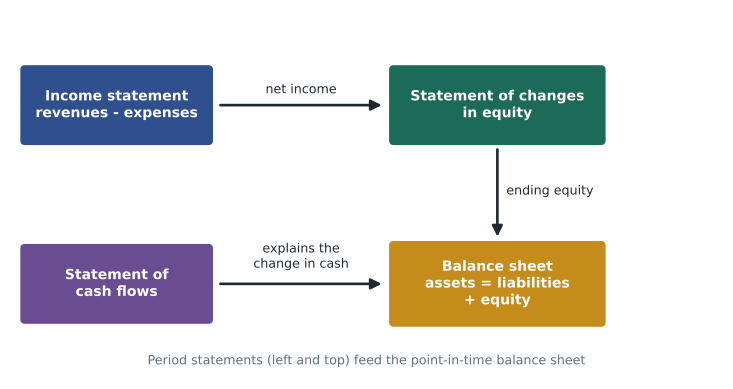
Financial accounting summarizes a period's activity in four statements, each answering a different question. The income statement (also called the statement of profit or loss, or statement of operations) shows revenues and expenses for a period and the resulting net income or loss: did the business make money? The statement of changes in equity, which for a small business may be a simpler statement of retained earnings or of owner's capital, shows how equity changed: what was earned, invested and paid out? The balance sheet, called the statement of financial position under IFRS, lists assets, liabilities and equity at a moment in time: what does the business own and owe? The statement of cash flows shows cash coming in and going out from operating, investing and financing activities: where did the cash come from and where did it go?
The statements are linked. Net income from the income statement flows into retained earnings; ending retained earnings appear on the balance sheet; and the change in cash on the balance sheet is explained by the statement of cash flows. Notes to the financial statements explain accounting policies and add detail. Lesson 7 builds all four from a trial balance, and lesson 12 completes the cash flow statement and shows how analysts read them together. Note that a new IFRS standard on presentation (IFRS 18) changes the layout of the income statement for IFRS reporters from 2027; the underlying accounting you learn here does not change.
Common mistakes
MistakeThinking bookkeeping and accounting are the same thing.
InsteadBookkeeping records transactions; accounting also designs the system, measures difficult items, interprets results and communicates them.
MistakeMixing the owner's personal spending into business records because the owner and the business are the same person legally.
InsteadThe economic entity assumption keeps business records separate even for a sole proprietorship.
MistakeRecording revenue when an order is promised to make results look better.
InsteadRevenue is recorded when it is earned, which usually means when goods are delivered or services performed.
MistakeAssuming managerial reports must follow published accounting standards.
InsteadOnly financial accounting reports for external users must follow a framework; managerial reports follow whatever helps decisions.
MistakeAssuming US companies can choose IFRS freely.
InsteadUS public companies must use US GAAP; foreign private issuers may use IFRS.
Summary and key terms
- Accounting identifies, measures, records and communicates economic information for decisions.
- Internal users can request custom reports; external users rely on general-purpose financial statements.
- Financial accounting serves external users under published standards; managerial accounting serves internal users with no required format.
- The US uses US GAAP set by FASB, with the SEC overseeing public company reporting.
- The conceptual framework emphasizes relevance and faithful representation, supported by assumptions such as entity, going concern and accrual accounting.
- Professional accountants follow codes of ethics built on integrity, objectivity and competence.
- The four statements are the income statement, statement of changes in equity, balance sheet and statement of cash flows, and they link to each other.
- Accounting
- The process of identifying, measuring, recording and communicating economic information for decision making.
- Bookkeeping
- The recording part of accounting: entering transactions and maintaining the ledger.
- Financial accounting
- Accounting that produces general-purpose reports for external users under published standards.
- Managerial accounting
- Accounting that produces reports for internal decision makers, with no required format.
- IFRS
- International Financial Reporting Standards, issued by the IASB and used in more than 140 jurisdictions.
- Generally accepted accounting principles (GAAP)
- The body of standards used in a jurisdiction; in the US, the standards set by FASB and codified in the Accounting Standards Codification.
- Economic entity assumption
- The principle that a business is accounted for separately from its owners and other entities.
- Going concern assumption
- The assumption that a business will continue operating for the foreseeable future.
- Accrual basis
- Recording revenues when earned and expenses when incurred, regardless of when cash changes hands.
- Faithful representation
- The quality of information that is complete, neutral and free from material error.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Name three external users of accounting information and one question each might ask.
Show answer
Examples: a bank (can the borrower repay?), an investor (will earnings grow?), a supplier (will the customer pay on time?).
Give two differences between financial and managerial accounting.
Show answer
Financial is for external users and follows standards; managerial is for internal users and follows no required format. Financial covers the whole entity; managerial can focus on segments.
Which framework must a US company listed on the NYSE use?
Show answer
US GAAP.
A business owner pays her home electricity bill from the business bank account. How should it be treated?
Show answer
Not as a business expense; it is a withdrawal by the owner (or an amount owed by the shareholder).
Why is equipment usually reported at cost less depreciation instead of at its resale value?
Show answer
Because of the going concern assumption and historical cost: the business expects to use the equipment, not sell it.
What are the two fundamental qualities of useful information in the conceptual framework?
Show answer
Relevance and faithful representation.
A customer pays in December for a service to be performed in February. Under the accrual basis, when is the revenue earned?
Show answer
In February, when the service is performed. In December the business has an obligation (unearned revenue).
List the four financial statements and the question each answers.
Show answer
Income statement (profit?), changes in equity (what was earned, invested and paid out?), balance sheet (what is owned and owed?), cash flows (where did cash come from and go?).
Why do professional accountants need a code of ethics?
Show answer
Because users rely on financial information they cannot check themselves; trust requires integrity and objectivity.
Portfolio task: find the annual report of a public company you know and list its four financial statements and the name it uses for each.
Show answer
Answers vary; note names such as statement of financial position or consolidated statement of operations.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.