
ACCT-101 · Lesson 8 of 12 · 30 min
Merchandising operations and sales taxes
So far Birchwood Bikes has earned all its revenue from repairs, a service. In June it starts selling new bicycles and accessories, which makes it a merchandiser as well: a business that buys goods and resells them without changing their form. Merchandising adds a large new expense, the cost of the goods sold, and a new asset, merchandise inventory. It also brings sales taxes into the records. This lesson explains the operating cycle of a merchandiser, the perpetual and periodic inventory systems, how purchases, returns, discounts and freight are recorded, how gross profit and the multiple-step income statement are built, and how sales taxes are accounted for. Lesson 9 covers how inventory costs are assigned when prices change.
The operating cycle of a merchandiser
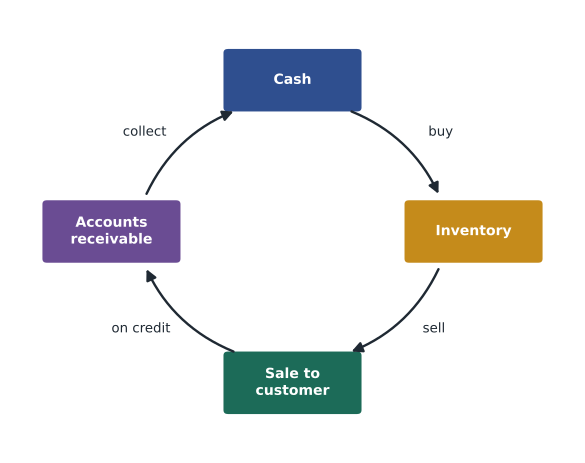
A merchandiser's operating cycle runs from cash, to inventory bought from suppliers, to sales to customers (often on credit), to receivables, and back to cash. For a grocery store the cycle may be a couple of weeks; for a bicycle shop that buys its spring stock in winter, it can be many months. The length of the cycle affects how much cash the business must tie up in inventory and receivables, a theme lesson 12 returns to with turnover ratios.
Gross profit is what is left from sales after paying for the goods; it must cover all the other operating expenses, such as wages, rent and advertising, before there is any net income. Gross profit divided by net sales is the gross margin, a key measure for retailers.
Perpetual and periodic inventory systems
Under a perpetual inventory system, the inventory account and the cost of goods sold account are updated with every purchase and every sale. Each sale is recorded with two entries: one for the revenue at selling price and one transferring the cost of the item from inventory to cost of goods sold. Barcode scanners and point-of-sale software make the perpetual system the norm for most retailers today. It shows the inventory that should be on hand at any time, so shrinkage from theft, damage or error can be measured by comparing the records with a physical count.
Under a periodic inventory system, purchases are recorded in a Purchases account, and inventory and cost of goods sold are not updated during the period. At the end of the period, a physical count establishes ending inventory, and cost of goods sold is calculated as beginning inventory plus net purchases minus ending inventory. The periodic system is simpler to run but gives no running inventory figure and cannot separate shrinkage from goods sold. Some small businesses still use it.
| Event | Perpetual system | Periodic system |
|---|---|---|
| Buy goods on account, $5,000 | Dr Inventory 5,000 / Cr Accounts payable 5,000 | Dr Purchases 5,000 / Cr Accounts payable 5,000 |
| Sell goods costing $3,000 for $4,500 on account | Dr Accounts receivable 4,500 / Cr Sales revenue 4,500; and Dr COGS 3,000 / Cr Inventory 3,000 | Dr Accounts receivable 4,500 / Cr Sales revenue 4,500 (no cost entry) |
| End of period | Count; adjust Inventory for shrinkage | Count; compute COGS; adjust Inventory to the count |
Purchases: returns, discounts and freight
Purchase returns and allowances reduce the cost of inventory: if goods are returned to the supplier or the supplier gives a price reduction for damage, the perpetual entry debits Accounts payable (or Cash) and credits Inventory. Purchase discounts are reductions for paying early. Terms of 2/10, n/30 mean the buyer may deduct 2 percent if it pays within 10 days, and otherwise the full amount is due in 30 days. Under the gross method, the purchase is recorded at the full price and the discount, if taken, reduces inventory when payment is made. Taking such a discount is usually a very good deal: giving up 2 percent to pay 20 days later is equivalent to an annual interest rate of about 37 percent.
Freight costs depend on the shipping terms. FOB shipping point means ownership passes to the buyer when the goods leave the seller, and the buyer pays the freight; the freight is part of the cost of the inventory. FOB destination means ownership passes when the goods arrive, and the seller pays the freight as a selling expense (often called freight-out or delivery expense). The terms also decide which business owns goods that are in transit on the balance sheet date, which matters for the year-end count. International contracts often use Incoterms such as EXW, FCA or DDP, which set the same kinds of rules in more detail.
Worked problem
Recording a purchase with discount and freight (perpetual)
On 1 June Birchwood Bikes buys 20 bicycles at $400 each from a distributor on terms 2/10, n/30, FOB shipping point. It pays $240 freight to a carrier in cash. On 4 June it returns one damaged bicycle. It pays the balance on 10 June. Ignore sales tax.
Show solution
- 1 June purchase: debit Inventory 8,000; credit Accounts payable 8,000.
- 1 June freight: debit Inventory 240; credit Cash 240. Freight-in is part of the cost of the goods.
- 4 June return: debit Accounts payable 400; credit Inventory 400. Amount owed is now 7,600.
- 10 June payment within the discount period: discount = 2 % × 7,600 = $152. Debit Accounts payable 7,600; credit Inventory 152; credit Cash 7,448.
- Cost of the 19 bicycles = 8,000 + 240 − 400 − 152 = $7,688, or about $404.63 each.
Answer: Inventory carries the net cost of $7,688 for 19 bicycles.
Sales: returns, discounts and cost of goods sold
On the selling side, a perpetual system records two entries for each sale: revenue at selling price, and the transfer of cost from inventory to cost of goods sold. If a customer returns goods, the seller reverses part of the revenue through a contra revenue account, Sales returns and allowances, and, if the goods can be resold, returns their cost to inventory. Sales discounts for early payment are also recorded in a contra revenue account. Net sales equals gross sales less returns, allowances and discounts. Under current revenue standards, a business that expects customers to return goods or take discounts estimates them when it records the sale; ACCT-211 covers that refinement.
Worked problem
Recording a sale and a return (perpetual)
On 12 June Birchwood Bikes sells four bicycles for $650 each on account to a youth club, terms 1/10, n/30. Each cost $404.63. On 15 June one bicycle is returned unused. The club pays the balance on 21 June. Ignore sales tax.
Show solution
- 12 June: debit Accounts receivable 2,600; credit Sales revenue 2,600. Also debit Cost of goods sold 1,618.52; credit Inventory 1,618.52.
- 15 June: debit Sales returns and allowances 650; credit Accounts receivable 650. Also debit Inventory 404.63; credit Cost of goods sold 404.63.
- 21 June: balance owed = 1,950; discount 1 % = 19.50. Debit Cash 1,930.50; debit Sales discounts 19.50; credit Accounts receivable 1,950.
- Net sales = 2,600 − 650 − 19.50 = 1,930.50; COGS = 1,213.89; gross profit = 716.61.
Answer: Net sales $1,930.50; cost of goods sold $1,213.89; gross profit $716.61.
Sales taxes
In the United States there is no federal sales tax. Forty-five states and the District of Columbia impose a state sales tax, and many cities and counties add local taxes, so combined rates vary by location; this lesson uses an illustrative combined rate of 7.5 percent for Birchwood's location. Sales tax is levied on the final consumer. A retailer collects it from customers at the point of sale and records it as a liability, Sales tax payable, because it is collected on behalf of the state; it remits the tax monthly or quarterly. The tax is not revenue. A retailer does not pay sales tax on goods bought for resale, because it gives the supplier a resale or exemption certificate. Sales tax it pays on items for its own use, such as supplies or equipment, becomes part of the cost of those items. Since the 2018 Supreme Court decision in South Dakota v. Wayfair, states can require out-of-state sellers to collect tax once their sales into the state pass an economic nexus threshold, commonly $100,000; rules differ by state.
Worked problem
Recording sales tax on a sale and a supply purchase
Birchwood Bikes sells a bicycle for $650 plus 7.5 % sales tax to a cash customer. It bought the bicycle for resale for $404.63 with a resale certificate, so no tax was charged. It also bought $200 of shop cleaning supplies and paid $15 sales tax. Sales tax collected for the month totals $1,950.
Show solution
- Sale: debit Cash 698.75; credit Sales revenue 650.00; credit Sales tax payable 48.75. Also record COGS and reduce inventory by 404.63.
- Bicycle purchase: debit Inventory 404.63; credit Accounts payable 404.63 (no tax, because of the resale certificate).
- Supplies purchase: debit Supplies 215; credit Cash 215. The tax is part of the cost because Birchwood is the final consumer.
- Month end: debit Sales tax payable 1,950; credit Cash 1,950 when remitted to the state.
Answer: Revenue is $650 for this sale, not $698.75; the tax collected is a liability until remitted.
# Gross profit and sales tax for a month of merchandise sales (illustrative)
units_sold, price, unit_cost = 42, 650.00, 404.63
returns_units = 2
tax_rate = 0.13          # HST in Ontario; change to 0.075 for the US example

gross_sales = units_sold * price
returns = returns_units * price
net_sales = gross_sales - returns
cogs = (units_sold - returns_units) * unit_cost
gross_profit = net_sales - cogs
tax_collected = net_sales * tax_rate

print(f"Gross sales      {gross_sales:>10,.2f}")
print(f"Less returns     {returns:>10,.2f}")
print(f"Net sales        {net_sales:>10,.2f}")
print(f"Cost of goods    {cogs:>10,.2f}")
print(f"Gross profit     {gross_profit:>10,.2f}")
print(f"Gross margin     {gross_profit / net_sales:>10.1%}")
print(f"Sales tax collected (a liability, not revenue): {tax_collected:,.2f}")Gross sales 27,300.00 Less returns 1,300.00 Net sales 26,000.00 Cost of goods 16,185.20 Gross profit 9,814.80 Gross margin 37.7% Sales tax collected (a liability, not revenue): 3,380.00
The multiple-step income statement
A merchandiser usually presents a multiple-step income statement, which shows subtotals that help users understand performance: net sales, cost of goods sold, gross profit, operating expenses (often split into selling and administrative), operating income, other income and expenses (such as interest), income before tax, income tax, and net income. The single-step format, used in lesson 7, lists all revenues and all expenses with one subtraction; both give the same net income.
| Birchwood Bikes Inc., June (illustrative) | ||
|---|---|---|
| Sales revenue | $27,300 | |
| Less: sales returns and discounts | (1,320) | |
| Net sales | 25,980 | |
| Service revenue | 6,900 | |
| Total revenue | 32,880 | |
| Cost of goods sold | (16,190) | |
| Gross profit | 16,690 | |
| Operating expenses | ||
| Wages | $7,400 | |
| Rent | 2,000 | |
| Advertising | 850 | |
| Depreciation | 420 | |
| Utilities, insurance and supplies | 1,230 | |
| Total operating expenses | (11,900) | |
| Operating income | 4,790 | |
| Interest expense | (100) | |
| Income before income tax | $4,690 |
For a business that sells both goods and services, gross profit is sometimes reported only for merchandise, with service revenue shown separately. Accountants choose the layout that best informs users and apply it consistently.
Inventory shrinkage and the year-end count
Even with a perpetual system, businesses count their inventory at least once a year. The count checks the records against reality and measures shrinkage. If the records show $48,200 of inventory and the count finds $47,350, the $850 shortfall is recorded by debiting Cost of goods sold (or a separate Inventory shrinkage expense) and crediting Inventory. Cut-off procedures make sure goods received or shipped around the count date are recorded in the right period, which is where the FOB terms matter. Shrinkage is a significant cost for retailers; industry surveys often put it at between 1 and 2 percent of sales.
Common mistakes
MistakeRecording freight-in as an operating expense.
InsteadFreight paid to bring goods in (FOB shipping point) is part of the cost of inventory.
MistakeRecording sales tax collected as revenue.
InsteadSales taxes collected are liabilities owed to the government until remitted.
MistakePaying sales tax on goods bought for resale.
InsteadGive the supplier a resale certificate; the final customer pays the tax.
MistakeForgetting the cost entry for a sale under a perpetual system.
InsteadEach sale needs two entries: revenue at selling price, and cost of goods sold out of inventory at cost.
MistakeRecording sales returns as a direct debit to Sales revenue.
InsteadUse the contra revenue account Sales returns and allowances so gross sales and returns are both visible.
Summary and key terms
- A merchandiser buys and resells goods; gross profit = net sales − cost of goods sold.
- A perpetual system updates inventory and COGS with each sale; a periodic system computes COGS from a count.
- Purchase returns, discounts and freight-in adjust the cost of inventory.
- FOB shipping point: buyer owns goods in transit and pays freight; FOB destination: seller does.
- Sales returns, allowances and discounts are contra revenue accounts that reduce gross sales to net sales.
- Sales tax collected is a liability remitted to the state; tax paid on items for the business's own use becomes part of their cost.
- A multiple-step income statement shows gross profit and operating income before net income.
- Merchandiser
- A business that buys goods and resells them without changing their form.
- Merchandise inventory
- Goods held for sale in the ordinary course of business.
- Cost of goods sold (COGS)
- The cost of the inventory sold during the period.
- Gross profit
- Net sales minus cost of goods sold.
- Perpetual inventory system
- A system that updates inventory and cost of goods sold with every transaction.
- Periodic inventory system
- A system that determines inventory and cost of goods sold from a physical count at period end.
- FOB shipping point
- Shipping terms under which ownership passes to the buyer when goods leave the seller.
- Sales returns and allowances
- A contra revenue account for goods returned or price reductions given to customers.
- Sales tax payable
- A liability for sales tax collected from customers and not yet remitted; goods bought for resale are exempt with a resale certificate.
- Shrinkage
- Inventory lost to theft, damage or error, measured by comparing records with a physical count.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Beginning inventory $12,000, purchases $45,000, purchase returns $1,500, freight-in $800, ending inventory $14,300. Find COGS (periodic).
Show answer
12,000 + 45,000 − 1,500 + 800 − 14,300 = $42,000.
Net sales are $80,000 and COGS $52,000. Find gross profit and gross margin.
Show answer
$28,000; 35 %.
A $6,000 purchase on terms 2/10, n/30 is paid within the discount period. How much is paid?
Show answer
$5,880.
Who pays freight and owns goods in transit under FOB destination?
Show answer
The seller.
A perpetual system shows inventory of $31,400; the count is $30,950. Record the adjustment.
Show answer
Debit Cost of goods sold (or shrinkage expense) 450; credit Inventory 450.
A retailer sells goods for $2,000 plus 7.5 % sales tax on account. Record the sale (ignore cost).
Show answer
Debit Accounts receivable 2,150; credit Sales revenue 2,000; credit Sales tax payable 150.
In a month a retailer collects $9,100 of sales tax. What does it remit?
Show answer
$9,100.
Why are sales returns recorded in a contra account?
Show answer
So users see both gross sales and the level of returns.
What annual interest rate is implied by forgoing a 2/10, n/30 discount?
Show answer
About 2/98 × 365/20 ≈ 37 %.
Change tax_rate in the Python program and confirm that gross profit does not change. Why?
Show answer
Sales tax is a liability, not revenue or expense, so it does not affect gross profit.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.