
CON-320 · Lesson 3 of 12 · 26 min
Contractor financial statements
A contractor's financial statements look much like any company's at first glance: a balance sheet, an income statement, a statement of cash flows and notes. Read closely, they have features that only make sense in construction. The balance sheet carries holdback or retainage on both sides, contract assets and contract liabilities that reflect the gap between billings and work done, and often a large fleet of equipment. The income statement shows thin gross margins on large revenue. The notes describe how revenue is recognized, how much backlog the firm carries, and what contingencies hang over it. This lesson builds Kestrel Builders' statements for fiscal 2025 and explains each line from a contractor's point of view.
Kestrel reports under Accounting Standards for Private Enterprises (ASPE), which most private Canadian contractors use. Publicly accountable enterprises in Canada, such as listed construction companies, must use International Financial Reporting Standards (IFRS). The structure of the statements is similar under both; the main differences for contractors are in terminology, revenue recognition detail and lease accounting, discussed in Lessons 4 and 9.
The balance sheet
The balance sheet, or statement of financial position, shows what the firm owns and owes at a single date. Contractors almost always present a classified balance sheet, separating current items (expected to be collected or paid within the operating cycle or a year) from long-term items, because sureties and lenders focus on working capital.
| Kestrel Builders, balance sheet at 31 December 2025 | $ |
|---|---|
| Cash | 2,850,000 |
| Contract receivables, excluding holdback | 6,900,000 |
| Holdback receivable | 2,700,000 |
| Contract assets (costs and estimated earnings in excess of billings) | 1,150,000 |
| Inventory, prepaid expenses and deposits | 350,000 |
| Total current assets | 13,950,000 |
| Construction equipment and vehicles, net of accumulated amortization | 3,200,000 |
| Total assets | 17,150,000 |
| Trade and subcontract payables | 5,800,000 |
| Holdback payable | 2,100,000 |
| Contract liabilities (billings in excess of costs and estimated earnings) | 2,250,000 |
| Accrued liabilities, including payroll and taxes | 950,000 |
| Current portion of long-term debt | 400,000 |
| Bank line of credit | 0 |
| Total current liabilities | 11,500,000 |
| Long-term debt, net of current portion | 1,250,000 |
| Total liabilities | 12,750,000 |
| Share capital | 200,000 |
| Retained earnings | 4,200,000 |
| Total shareholders' equity | 4,400,000 |
| Total liabilities and equity | 17,150,000 |
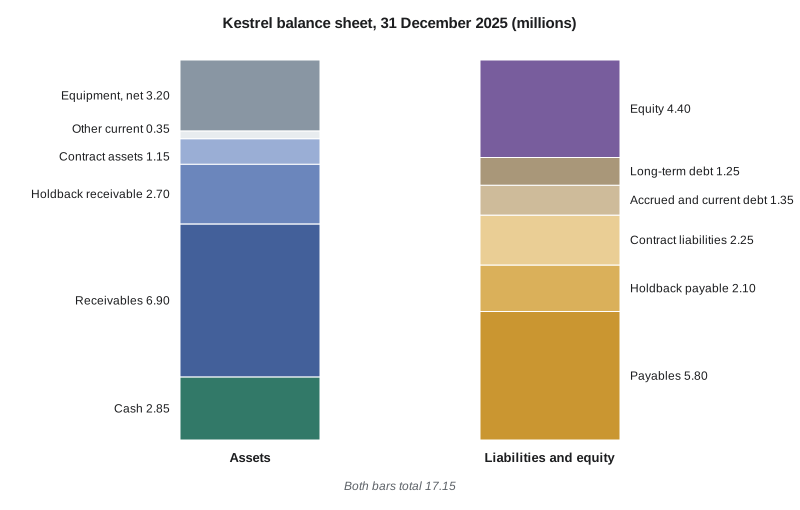
Several features stand out. Receivables, holdback and contract assets make up about 63 % of total assets; a contractor's main assets are claims on its customers, not physical things. Payables and holdback payable are the largest liabilities, because the firm is in turn being financed by its subcontractors and suppliers. Working capital, current assets minus current liabilities, is $2,450,000. Equity is $4,400,000, about a quarter of total assets.
Contractor-specific balance sheet items
| Item | What it is | What readers watch for |
|---|---|---|
| Holdback receivable | Amounts the owner has withheld from progress payments, collectable after substantial completion or another release event | Old holdbacks on finished jobs may signal disputes or deficiencies |
| Contract assets | Revenue earned on jobs in excess of amounts billed (underbillings) | Large or growing underbillings can mean unbilled changes, slow billing or overstated progress |
| Contract liabilities | Amounts billed in excess of revenue earned (overbillings) | Overbillings are cash already collected for work still to be done; a firm that spends them may be short when the work is due |
| Holdback payable | Amounts the contractor has withheld from subcontractors | Usually matched by holdback receivable on the same jobs |
| Construction equipment | Owned equipment at cost less accumulated depreciation | Age of fleet, borrowing secured on it, whether it earns its cost (Lesson 7) |
| Accrued liabilities | Payroll, benefits, taxes and costs incurred but not invoiced | Unpaid source deductions or trust funds are serious red flags |
| Due from related parties | Loans to owners or affiliated companies | Sureties often deduct these from working capital because they may not be collectable |
Contract assets and liabilities are the subject of Lesson 5. For now, note that they are not cash or invoices; they are adjustments that bring revenue in line with work done. Under IFRS 15 and ASC 606, contract assets and contract liabilities are the formal terms, but many contractors and sureties still use the older names: costs and estimated earnings in excess of billings, and billings in excess of costs and estimated earnings. The two are often called underbillings and overbillings.
The income statement
The income statement shows performance over a period. A contractor's statement usually separates contract revenue and contract costs to show gross profit, then deducts general and administrative overhead.
| Kestrel Builders, income statement for the year ended 31 December 2025 | $ | % of revenue |
|---|---|---|
| Contract revenue | 58,400,000 | 100.0 |
| Contract costs | 53,440,000 | 91.5 |
| Gross profit | 4,960,000 | 8.5 |
| General and administrative expenses | 3,300,000 | 5.7 |
| Income from operations | 1,660,000 | 2.8 |
| Interest expense | (140,000) | (0.2) |
| Gain on sale of equipment | 40,000 | 0.1 |
| Income before income taxes | 1,560,000 | 2.7 |
| Income taxes | (330,000) | (0.6) |
| Net income | 1,230,000 | 2.1 |
Contract costs include all direct job costs: labour, materials, subcontracts, equipment charged to jobs and other direct costs, plus any field overhead the firm allocates to jobs. General and administrative expenses are the costs of running the company: executive and office salaries, estimating, accounting, rent, office technology, professional fees and the part of insurance not charged to jobs. Where the line between them falls is a policy choice that affects reported gross margin, so comparisons between contractors should check what each includes. Lesson 6 looks at that choice.
| General and administrative expenses (illustrative) | $ |
|---|---|
| Executive, office and estimating salaries and benefits | 1,920,000 |
| Office rent, utilities and maintenance | 310,000 |
| Technology, software and communications | 260,000 |
| Professional fees: accounting, legal, consulting | 180,000 |
| Insurance not charged to jobs | 150,000 |
| Bidding costs, marketing and travel | 210,000 |
| Office equipment amortization | 90,000 |
| Other | 180,000 |
| Total | 3,300,000 |
Gross margin and overhead are the two numbers a contractor's management watches most. Here the firm earns 8.5 cents of gross profit on each revenue dollar and spends 5.7 cents on overhead. If gross margin fell to 6.5 % on the same volume, operating income would fall to about $500,000; at 5.7 % it would be zero. That leverage is why a contractor's profit can swing so much from year to year.
The statement of cash flows
The statement of cash flows explains the change in cash during the year, in three groups: operating, investing and financing activities. Most contractors use the indirect method, starting from net income and adjusting for items that did not involve cash and for changes in working capital accounts.
| Kestrel Builders, statement of cash flows for 2025 | $ |
|---|---|
| Net income | 1,230,000 |
| Amortization of equipment | 620,000 |
| Gain on sale of equipment | (40,000) |
| Increase in contract receivables | (900,000) |
| Increase in holdback receivable | (450,000) |
| Increase in contract assets | (300,000) |
| Increase in prepaid expenses | (50,000) |
| Increase in trade and subcontract payables | 600,000 |
| Increase in holdback payable | 250,000 |
| Increase in contract liabilities | 400,000 |
| Increase in accrued liabilities | 100,000 |
| Cash from operating activities | 1,460,000 |
| Purchase of equipment | (950,000) |
| Proceeds from sale of equipment | 120,000 |
| Cash used in investing activities | (830,000) |
| New equipment loan | 350,000 |
| Repayment of long-term debt | (380,000) |
| Dividends paid | (350,000) |
| Cash used in financing activities | (380,000) |
| Increase in cash | 250,000 |
| Cash, beginning of year | 2,600,000 |
| Cash, end of year | 2,850,000 |
The working capital lines tell the story. Kestrel grew during the year, so its receivables, holdback and underbillings rose by $1.65 million, absorbing more cash than its net income. Its suppliers, subcontractors and overbillings provided $1.35 million back. Operating cash flow was positive, but much of it went into new equipment. A surety reading this statement would note that operating cash flow covered the equipment purchases and dividends only narrowly.
ni, dep, gain = 1_230_000, 620_000, -40_000
wc_changes = {"receivables": -900_000, "holdback receivable": -450_000,
              "contract assets": -300_000, "prepaid": -50_000,
              "payables": 600_000, "holdback payable": 250_000,
              "contract liabilities": 400_000, "accrued": 100_000}
cfo = ni + dep + gain + sum(wc_changes.values())
cfi = -950_000 + 120_000
cff = 350_000 - 380_000 - 350_000
print(f"Operating {cfo:,}  Investing {cfi:,}  Financing {cff:,}")
print(f"Change in cash {cfo + cfi + cff:,}; ending cash {2_600_000 + cfo + cfi + cff:,}")
absorbed = -sum(v for v in wc_changes.values() if v < 0)
provided = sum(v for v in wc_changes.values() if v > 0)
print(f"Working capital absorbed {absorbed:,}, provided {provided:,}")Operating 1,460,000 Investing -830,000 Financing -380,000 Change in cash 250,000; ending cash 2,850,000 Working capital absorbed 1,700,000, provided 1,350,000
How the three statements connect
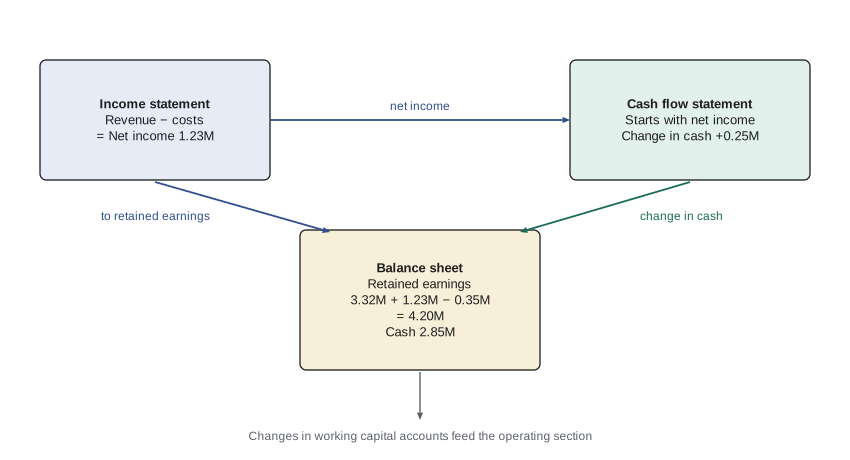
The statements are linked. Net income from the income statement increases retained earnings on the balance sheet, after dividends. The statement of cash flows starts with the same net income and explains how cash on the balance sheet moved from the beginning to the end of the year. Changes in each working capital account on the balance sheet appear as lines in the operating section.
Worked problem
Checking retained earnings
Kestrel's retained earnings were $3,320,000 at the start of 2025. It earned $1,230,000 and paid dividends of $350,000. What should retained earnings be at year-end?
Show solution
- Opening retained earnings: $3,320,000.
- Add net income: 3,320,000 + 1,230,000 = $4,550,000.
- Deduct dividends: 4,550,000 − 350,000 = $4,200,000.
Answer: Retained earnings of $4,200,000 match the balance sheet. A difference would mean an error or an item recorded directly in equity that needs explaining.
The notes and supplementary schedules
Much of what a surety or lender wants to know about a contractor is in the notes and the supplementary schedules rather than the face of the statements.
| Note or schedule | What it shows |
|---|---|
| Significant accounting policies | How revenue is recognized, how progress is measured, how equipment is depreciated, how leases are treated |
| Contract balances | Contract assets and liabilities, holdback or retainage, and how they changed |
| Backlog or remaining performance obligations | Signed work not yet performed and when it is expected to be earned |
| Debt and credit facilities | Loans, interest rates, security and covenants |
| Commitments and contingencies | Claims, lawsuits, guarantees, leases and bonded obligations |
| Related party transactions | Dealings with owners and affiliated companies |
| Schedule of contracts in progress (WIP schedule) | Each open job's contract value, estimated cost, revenue and gross profit to date, billings and over or underbilling (Lesson 5) |
| Schedule of completed contracts | Final revenue, cost and gross profit on jobs finished during the year, compared with earlier estimates |
The two schedules at the bottom of the table are not required by the accounting standards, but sureties ask for them as a matter of course. The schedule of completed contracts is especially telling, because it shows whether the firm's estimates of job profit while work was in progress held up when the jobs finished. A contractor whose completed jobs consistently earned less than its WIP schedules predicted has a problem with its estimates, and sureties will discount its current WIP schedule accordingly.
Levels of assurance on the statements
Statements prepared by a contractor's own staff, or compiled by an outside accountant without testing, carry no independent assurance. A review engagement by a public accountant provides limited assurance based mainly on inquiry and analysis. An audit provides reasonable assurance based on testing the records, confirming balances with third parties and evaluating job estimates. Sureties usually set the level they require by the size of the bonding program: compiled statements may be accepted for small programs, reviewed statements for mid-sized ones, and audited statements for larger programs. Lesson 11 returns to this.
| Level | Canadian standard | Assurance | Typical use by contractors |
|---|---|---|---|
| Compilation | CSRS 4200 | None | Small firms, small bonding programs, internal use |
| Review | CSRE 2400 | Limited | Mid-sized bonding programs and bank lines |
| Audit | Canadian Auditing Standards | Reasonable | Large bonding programs, public owners, larger lenders |
Common mistakes
MistakeReading a contractor's balance sheet like a manufacturer's.
InsteadMost of a contractor's assets are claims on customers, including holdback and contract assets, and most liabilities are amounts owed to subcontractors and suppliers.
MistakeCounting contract assets as if they were cash or invoices.
InsteadContract assets are revenue earned but not yet billed; they still have to be billed and collected.
MistakeTreating overbillings as free money.
InsteadContract liabilities represent work still to be done; spending that cash on other things leaves the firm short when the work is due.
MistakeComparing gross margins between contractors without checking what is in contract costs.
InsteadFirms allocate field overhead and equipment differently; compare like with like.
MistakeLooking only at net income.
InsteadRead the statement of cash flows; growth in receivables and holdback can absorb all of a year's profit.
MistakeSkipping the notes and schedules.
InsteadBacklog, contingencies, related parties and the WIP and completed contract schedules tell readers the most about a contractor.
Summary and key terms
- A contractor's balance sheet is dominated by receivables, holdback or retainage and contract balances on one side and payables on the other.
- Contract assets (underbillings) and contract liabilities (overbillings) adjust revenue to the work done; they are not cash or invoices.
- A contractor's income statement shows thin gross margins and overhead, so small margin changes swing profit sharply.
- The statement of cash flows shows how working capital changes absorb or release cash, especially during growth.
- The three statements connect through net income, retained earnings and the change in cash.
- Notes and supplementary schedules, especially the WIP and completed contract schedules, are central for sureties and lenders.
- Statements may be compiled, reviewed or audited; sureties set the level they require by program size.
- Classified balance sheet
- A balance sheet that separates current and long-term items.
- Contract asset
- Revenue recognized on a contract in excess of amounts billed; an underbilling.
- Contract liability
- Amounts billed on a contract in excess of revenue recognized; an overbilling.
- Gross profit
- Contract revenue minus contract costs.
- General and administrative expenses
- The costs of running the company that are not charged to jobs.
- Indirect method
- A way of preparing the operating section of the cash flow statement starting from net income.
- Retained earnings
- Cumulative net income kept in the business after dividends.
- Schedule of completed contracts
- A supplementary schedule of jobs finished in the year with their final results.
- Review engagement
- A limited-assurance engagement by a public accountant based on inquiry and analysis.
- Audit
- A reasonable-assurance engagement based on testing records and evidence.
Practice problems
Work each problem on paper first, then reveal the answer to check.
What is Kestrel's working capital at the end of 2025?
Show answer
13,950,000 − 11,500,000 = $2,450,000.
What share of Kestrel's total assets is receivables, holdback and contract assets?
Show answer
(6,900,000 + 2,700,000 + 1,150,000) ÷ 17,150,000 = about 63 %.
If Kestrel's gross margin fell to 7.0 % on the same revenue and overhead, what would income from operations be?
Show answer
0.07 × 58,400,000 − 3,300,000 = $788,000.
What do contract liabilities represent?
Show answer
Amounts billed in excess of revenue earned; cash collected for work still to be done.
Why did Kestrel's operating cash flow differ from net income?
Show answer
Non-cash depreciation and the gain were adjusted, and growth in receivables, holdback and contract assets absorbed cash while payables and overbillings provided some back.
Name two supplementary schedules sureties request.
Show answer
The schedule of contracts in progress (WIP schedule) and the schedule of completed contracts.
What does the schedule of completed contracts reveal?
Show answer
Whether profit estimates made while jobs were in progress held up at completion.
Retained earnings open at $1.8 million; net income is $600,000; dividends are $150,000. What is closing retained earnings?
Show answer
$2.25 million.
Which level of assurance involves confirming balances with third parties?
Show answer
An audit.
Why might a surety deduct amounts due from related parties from working capital?
Show answer
They may not be collectable in the short term or at all if the firm fails.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.