
CHE-499 · Lesson 12 of 12 · 24 min
Economic evaluation, risk and the final report
Twenty-six weeks after Ingrid's brief, the design has to answer the question the board asked: should Kingfisher turn 100 million litres of its ethanol into jet fuel? This last lesson builds the capital and operating cost estimates from the equipment list and the balances, evaluates the project by discounted cash flow, tests how its value responds to the uncertainties the earlier lessons identified, and turns all of it into a recommendation, a report and a presentation. It ends with the professional obligations that come with putting an engineering recommendation in front of people who will spend real money on it, and with the team's reflection on the year.
The capital estimate
AACE International classifies estimates by the maturity of the design behind them. A class 4 estimate, typical of a feasibility study, rests on a design that is perhaps 1 to 15 % complete, a process flow diagram, a sized equipment list and a plot plan, and its expected accuracy is roughly −15 to −30 % on the low side and +20 to +50 % on the high side. That is the class the brief asks for. Liam builds it by the factored method that CHE-446 taught: estimate the purchased cost of each major item from cost correlations and the sizes of Lesson 8, escalate to 2026 with a cost index, and multiply the total by a Lang factor to cover installation, piping, instruments, electrical, buildings, offsites and engineering.
The total purchased equipment cost comes to about 40 million dollars, a third of it in the oligomerization section with its two large multitubular reactors, and the Lang factor brings the fixed capital to about 190 million. Liam adds a contingency of 20 %, higher than the 10 to 15 % usual for proven technology, because the ATJ sequence is close to first of a kind and the estimate rests on a generic design rather than a licensor's package. Working capital and start-up costs bring the total capital to about 245 million dollars, with a class 4 range of roughly 185 to 345 million.
Operating costs and revenues
The operating cost has two parts. Variable costs scale with production: ethanol, by far the largest item, then hydrogen, natural gas, electricity, catalysts and chemicals. Fixed costs do not: operating labour for a continuous plant with five shift crews, maintenance at about 3 % of fixed capital a year, insurance and local taxes at about 1.5 %, and overheads. Revenues are the SAF at the fossil jet price plus the offtake premium, the naphtha and diesel, and the credits Lesson 11 valued.
| Item | Basis | Million dollars a year |
|---|---|---|
| Ethanol | 100 million L at 0.62 per L | 62.0 |
| Hydrogen, gas, power, catalysts, water | Lessons 4, 7 and 11 | 6.2 |
| Labour, maintenance, insurance, overhead | 15 operators; 3 % and 1.5 % of fixed capital | 12.2 |
| SAF | 49.1 million L at 0.85 plus 0.60 premium | 71.2 |
| Naphtha and diesel | Kingfisher forecasts | 11.4 |
| Clean Fuel Regulations credits | 190,000 at 120 (with proposed multiplier) | 22.8 |
| EBITDA | Revenue less operating costs | about 25 |
Discounted cash flow
The cash flow model follows Kingfisher's economic basis from Lesson 2: two years of construction, with 40 % and 60 % of the capital spent; twenty years of operation; constant 2026 prices; a real after-tax discount rate of 8 %; income tax at 26.5 %; and the immediate expensing of manufacturing and processing machinery enacted by Bill C-15 in March 2026, applied to the 85 % of capital that qualifies, with the rest depreciated over the plant's life. Because Kingfisher has taxable income from its ethanol plant, the tax saving from expensing is used in the year it arises. The net present value and internal rate of return follow:
# Class 4 estimate, discounted cash flow, break-even premium and tornado for the ATJ plant (millions, 2026 dollars)
PEC = {'dehydration': 8.5, 'quench, compression, purification': 9.5, 'oligomerization': 11.0,
       'hydrogenation': 3.5, 'fractionation': 4.5, 'storage and loading': 3.0}
lang = 4.74                                     # fluid processing plant, ISBL plus OSBL
FC = sum(PEC.values()) * lang
cont = 0.20 * FC                                # contingency for a first-of-a-kind feasibility estimate
TCI_fixed = FC + cont
WC, startup = 12.0, 0.03 * FC
print(f"purchased equipment {sum(PEC.values()):.1f}; fixed capital {FC:.0f}; contingency {cont:.0f}; "
      f"total {TCI_fixed+WC+startup:.0f} (class 4 range {0.75*(TCI_fixed+WC+startup):.0f} to {1.40*(TCI_fixed+WC+startup):.0f})")
base = dict(eth=0.62, jet=0.85, prem=0.60, credit=120.0, cred=0.190, capex=1.0, hours=8000)
# cred: million credits a year from Lesson 11 (0.190 with capture and multiplier, 0.117 without the multiplier)
TAX, r = 0.265, 0.08
def cash(p):
    f = p['hours'] / 8000
    L_eth, L_saf = 100.0 * f, 49.1 * f                       # million litres a year
    credits = p['cred'] * f                                  # million credits a year
    rev = L_saf * (p['jet'] + p['prem']) + 5.2 * f + 6.2 * f + credits * p['credit']
    var = L_eth * p['eth'] + (2.56 + 0.48 + 1.09 + 1.8 + 0.3) * f
    cap = TCI_fixed * p['capex']
    fixed = 2.6 + 0.03 * FC * p['capex'] + 0.015 * FC * p['capex'] + 1.0
    ebitda = rev - var - fixed
    flows = [-0.4 * cap, -0.6 * cap - WC - startup]            # two construction years
    for yr in range(1, 21):
        dep = 0.85 * cap if yr == 1 else 0.0                  # immediate expensing of M&P machinery (85 % of capital)
        dep += 0.15 * cap / 20                                # buildings and other assets, straight line
        tax = TAX * (ebitda - dep)                            # negative tax = shield used against Kingfisher's other income
        flows.append(ebitda - tax + (WC if yr == 20 else 0.0))
    return ebitda, flows
def npv(flows, rate): return sum(c / (1 + rate) ** t for t, c in enumerate(flows))
def irr(flows):
    lo, hi = -0.5, 0.5
    for _ in range(100):
        mid = (lo + hi) / 2
        if npv(flows, mid) > 0: lo = mid
        else: hi = mid
    return mid
e, fl = cash(base)
print(f"base case: EBITDA {e:.1f} per year; NPV at 8 % {npv(fl, r):.0f}; IRR {irr(fl):.1%}")
for name, ch in (('no credit multiplier', {'cred': 0.117}), ('premium 0.90 per litre', {'prem': 0.90}),
                 ('no capture (with multiplier)', {'cred': 0.080})):
    e2, f2 = cash(dict(base, **ch)); print(f"{name:<29} EBITDA {e2:5.1f}; NPV {npv(f2, r):5.0f}; IRR {irr(f2):.1%}")
lo, hi = 0.0, 3.0                                              # break-even SAF premium per litre
for _ in range(60):
    mid = (lo + hi) / 2
    if npv(cash(dict(base, prem=mid))[1], r) > 0: hi = mid
    else: lo = mid
print(f"break-even premium over fossil jet: {mid:.2f} per litre (SAF price {base['jet']+mid:.2f} per litre plus credits)")
print('tornado (NPV at 8 %):')
rows = [('ethanol price +/-15 %', 'eth', 0.62 * 1.15, 0.62 * 0.85), ('SAF premium 0.40 to 0.80', 'prem', 0.40, 0.80),
        ('credit price 70 to 170', 'credit', 70.0, 170.0), ('capital +40 % to -25 %', 'capex', 1.40, 0.75),
        ('fossil jet price +/-20 %', 'jet', 0.68, 1.02), ('on-stream 7,500 to 8,300 h', 'hours', 7500, 8300)]
for name, k, a, b in sorted(rows, key=lambda x: -abs(npv(cash(dict(base, **{x[1]: x[2]}))[1], r) - npv(cash(dict(base, **{x[1]: x[3]}))[1], r))):
print(f" {name:<28} {npv(cash(dict(base, **{k: a}))[1], r):5.0f} to {npv(cash(dict(base, **{k: b}))[1], r):5.0f}")purchased equipment 40.0; fixed capital 190; contingency 38; total 245 (class 4 range 184 to 343) base case: EBITDA 25.0 per year; NPV at 8 % -16; IRR 7.0% no credit multiplier EBITDA 16.3; NPV -75; IRR 2.7% premium 0.90 per litre EBITDA 39.8; NPV 82; IRR 12.8% no capture (with multiplier) EBITDA 11.8; NPV -104; IRR 0.0% break-even premium over fossil jet: 0.65 per litre (SAF price 1.50 per litre plus credits) tornado (NPV at 8 %): capital +40 % to -25 % -107 to 41 SAF premium 0.40 to 0.80 -82 to 50 credit price 70 to 170 -80 to 47 ethanol price +/-15 % -78 to 46 fossil jet price +/-20 % -72 to 40 on-stream 7,500 to 8,300 h -32 to -7
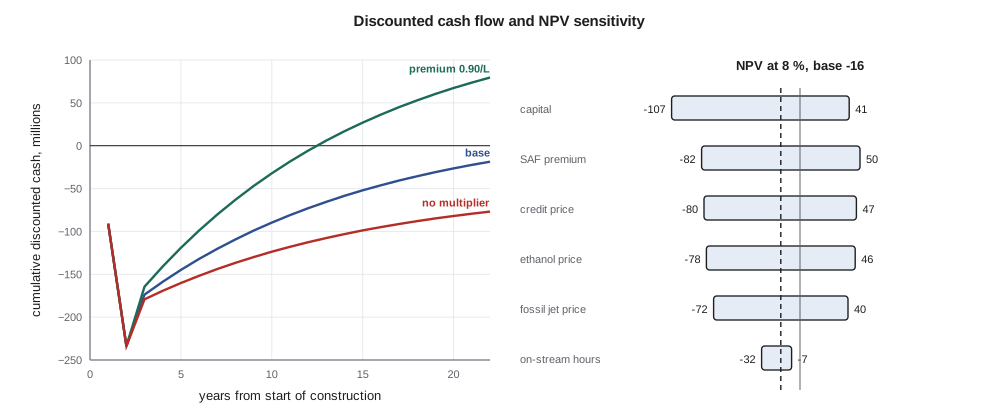
The base case does not quite pay. The NPV at 8 % is about −16 million dollars and the IRR about 7.0 %, just below Kingfisher's hurdle. The scenarios show how much hangs on policy. Without the proposed credit multiplier, the NPV falls to about −75 million and the IRR to under 3 %. Without the fermentation carbon dioxide capture, even with the multiplier, it falls to about −104 million. With an offtake premium of 0.90 dollars a litre instead of 0.60, the NPV rises to about +82 million and the IRR to about 13 %. The break-even premium, at which the NPV is zero, is about 0.65 dollars a litre, close to the base assumption.
Sensitivity and risk
The tornado chart ranks the uncertainties by their effect on NPV over plausible ranges. Capital, over the class 4 range, is the widest bar, followed closely by the SAF premium, the credit value and the ethanol price; each can move the NPV by more than 100 million dollars. On-stream hours matter much less. Two features are worth pointing out to the board. First, the bars are lopsided: the downside of capital is larger than the upside because class 4 estimates are more often low than high, especially for first-of-a-kind plants. Second, several of the inputs are correlated in ways a one-at-a-time tornado hides. A high ethanol price usually comes with high corn prices and often with high fossil fuel prices; credit prices depend on how many other low-carbon fuel projects are built. A Monte Carlo simulation that samples the inputs together, with their correlations, is the natural next step; the team lists it for FEL-2 rather than presenting a probability of success built on correlations it cannot yet estimate.
The team also writes a risk register: each risk with its cause, consequence, likelihood, owner and mitigation. The top entries are the technology risk in oligomerization scale-up, mitigated by licensing a proven process and obtaining performance guarantees; the policy risk in credits, mitigated by structuring offtake contracts so that buyers share it; the capture project dependency, mitigated by making the ATJ decision conditional on the capture project's own investment decision; and the market risk in the SAF premium, mitigated by a long-term offtake agreement before investment.
The recommendation
With a negative base-case NPV, the team cannot recommend that Kingfisher build the plant on the information available. Nor does it recommend dropping the idea: the project is close to break-even, its upside is large, the main uncertainties can be reduced before the next decision, and the market it serves is growing by policy. The recommendation is to proceed to the next stage of front-end design (FEL-2) with three conditions:
- A signed letter of intent from at least one SAF buyer at a premium at or above the break-even value, for a substantial share of output over at least ten years.
- A positive investment decision on the fermentation carbon dioxide capture and storage project, without which the product's carbon intensity does not justify the investment.
- Licensor proposals for the oligomerization step with performance guarantees, so that the next estimate can be class 3 with lower contingency.
The team adds that the final form of the October 2026 Clean Fuel Regulations amendments should be known before an investment decision, and that bio-ethylene, which shares the dehydration section and has a nearby market in Chemical Valley, remains a fallback that a smaller project could pursue.
The final report and presentation
The report follows the order of a professional feasibility study, not the order the work was done in. It opens with a two-page executive summary that states the recommendation and its conditions in the first paragraph, for readers who will read nothing else. Then come the basis, process selection, the process description with the flow diagram and balances, the reactor and separation designs, heat integration and utilities, equipment, control, safety, environment and carbon intensity, the cost estimate and economics, risks, and the recommendation. Appendices hold the stream tables, equipment list, data sheets, HAZOP worksheets, code and calculations. Every number in the summary can be traced to a section and every section to an appendix.
The presentation to the panel is twenty minutes plus questions. The team rehearses it four times, the last in front of Theo and two of his colleagues who play hostile reviewers. The questions they practise are the ones panels ask: what if the premium falls, why not bio-ethylene, how confident are you in the oligomerization kinetics, what happens to the plant if the credits disappear, who checked your LOPA. Professor Marchetti's advice is to answer each with a number from the report and its uncertainty, and to say 'we don't know' when that is the truth.
Worked problem
Annuity check on the NPV
A capital of 245 million dollars is spent over two years before operation. Roughly what constant after-tax cash flow over 20 years makes the NPV zero at 8 %?
Show solution
- Present value of the capital at the start of operation \(\approx 0.4 \times 245 \times 1.08^2 + 0.6 \times 245 \times 1.08 \approx 273\) million.
- Annuity factor for 20 years at 8 % \(= (1 - 1.08^{-20})/0.08 = 9.82\).
- Required cash flow \(\approx 273 / 9.82 \approx 28\) million dollars a year.
Answer: About 28 million dollars a year after tax, ignoring the early tax shield from expensing. The base case earns less than that, which is why its NPV is negative. Quick checks like this catch spreadsheet errors.
Professional practice and ethics
In the last week, Malik Osei, who will present the study to the board, asks the team whether the base-case premium could be set at 0.90 dollars a litre, since 'that is where the market will be by the time we build.' The team discusses it and declines. The premium forecast came from Kingfisher's own commercial team and is documented; a higher number without new evidence would make the recommendation look better by assumption. Instead, the higher premium appears as a scenario, clearly labelled, with the break-even value beside it so the board can judge for itself. Ingrid supports the team. That small episode is what the Code of Ethics in section 77 of Regulation 941 under Ontario's Professional Engineers Act means in practice: engineers are responsible for the honesty of their numbers, especially when someone they respect would prefer different ones.
Environmental claims carry their own obligations. Canada's Competition Act was amended in 2024 to require that claims about the environmental benefits of a product be based on adequate and proper testing or substantiation. A report or marketing text that calls the fuel 'sustainable' or 'low-carbon' must therefore rest on the verified carbon intensity, with its assumptions, not on the name of the product. The team's report states the carbon intensity with and without capture and avoids unqualified claims.
None of the students can seal an engineering document yet, and Theo, as an engineer in training, cannot either. If Kingfisher uses the study, Ingrid, as a P.Eng., will review the parts it relies on and take professional responsibility for them under the rules of Professional Engineers Ontario (PEO). The students' path to licensure starts now: they will need an accredited degree, a period of supervised engineering experience, and the professional practice examination, and the capstone is the first item on many of their experience records.
Reflection
Each student writes a short reflection, which counts towards the individual mark. Ana writes that the hardest part was keeping the design consistent as it changed: the change notes of Lesson 2 saved the team twice. Jonah writes that he expected the reactor kinetics to be the main uncertainty and found that the policy assumptions mattered more to the answer. Riya writes that pinch analysis was the most satisfying part, because the numbers made an intuition precise. Liam writes about the premium conversation, and about learning that a negative NPV, honestly presented with a path forward, is a useful result. Ingrid's own comment to the team, at the end of the presentation, is shorter: Kingfisher will fund the FEL-2 study, on the team's three conditions, and would like to interview any of them who are interested in doing it.
Common mistakes
MistakePresenting a class 4 estimate as a single number.
InsteadGive the expected range and the contingency, and say what drives it.
MistakeAdjusting assumptions until the NPV is positive.
InsteadKeep documented assumptions in the base case and show optimistic cases as labelled scenarios.
MistakeTreating tornado bars as independent.
InsteadNote correlations, such as ethanol with jet prices, and test them.
MistakeRecommending yes or no with nothing in between.
InsteadA conditional recommendation with clear gates is often the honest answer.
MistakeCalling the product 'sustainable' without substantiation.
InsteadState the verified carbon intensity and its assumptions.
Summary and key terms
- A class 4 estimate is factored from the equipment list, with contingency reflecting technology maturity, and has a wide accuracy range.
- Operating costs split into variable and fixed; ethanol dominates; revenues include premiums and credits.
- NPV and IRR follow from after-tax cash flows with the company's discount rate, tax rate and depreciation rules.
- The base case is close to break-even; capital, premium, credits and ethanol price dominate the uncertainty.
- The team recommends FEL-2 with three conditions: offtake, capture project and licensor guarantees.
- Engineers are responsible for the honesty of their numbers and claims; licensure follows degree, experience and examination.
- Class 4 estimate
- A feasibility-stage estimate with an accuracy of roughly −30 % to +50 %.
- Lang factor
- A multiplier from purchased equipment cost to fixed capital.
- Contingency
- An allowance for costs expected but not yet identified.
- Net present value (NPV)
- The sum of discounted cash flows at a chosen rate.
- Internal rate of return (IRR)
- The discount rate at which NPV is zero.
- Break-even value
- The value of an input at which NPV is zero.
- Risk register
- A list of risks with causes, consequences, owners and mitigations.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Purchased equipment costs 40 million and the Lang factor is 4.74. What is the fixed capital?
Show answer
About 190 million.
Why is the contingency 20 % rather than 10 %?
Show answer
The process is close to first of a kind and the design is generic, not a licensor's.
What is the annuity factor for 20 years at 8 %?
Show answer
About 9.82.
Which input has the widest tornado bar?
Show answer
Capital cost over the class 4 range.
Why did the team decline to raise the base-case premium?
Show answer
There was no new evidence; it would have improved the result by assumption.
Name the three conditions of the recommendation.
Show answer
An offtake letter of intent at or above break-even, the capture project's investment decision, and licensor guarantees for oligomerization.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.